
Import credit is credit used to support an importer’s purchases from overseas. It can provide funding for the buyer or form part of a bank-supported payment arrangement.
The term is also used more narrowly for a documentary credit opened at an importer’s bank in favor of a foreign seller. The contract matters: an ordinary loan and a letter of credit perform different jobs.
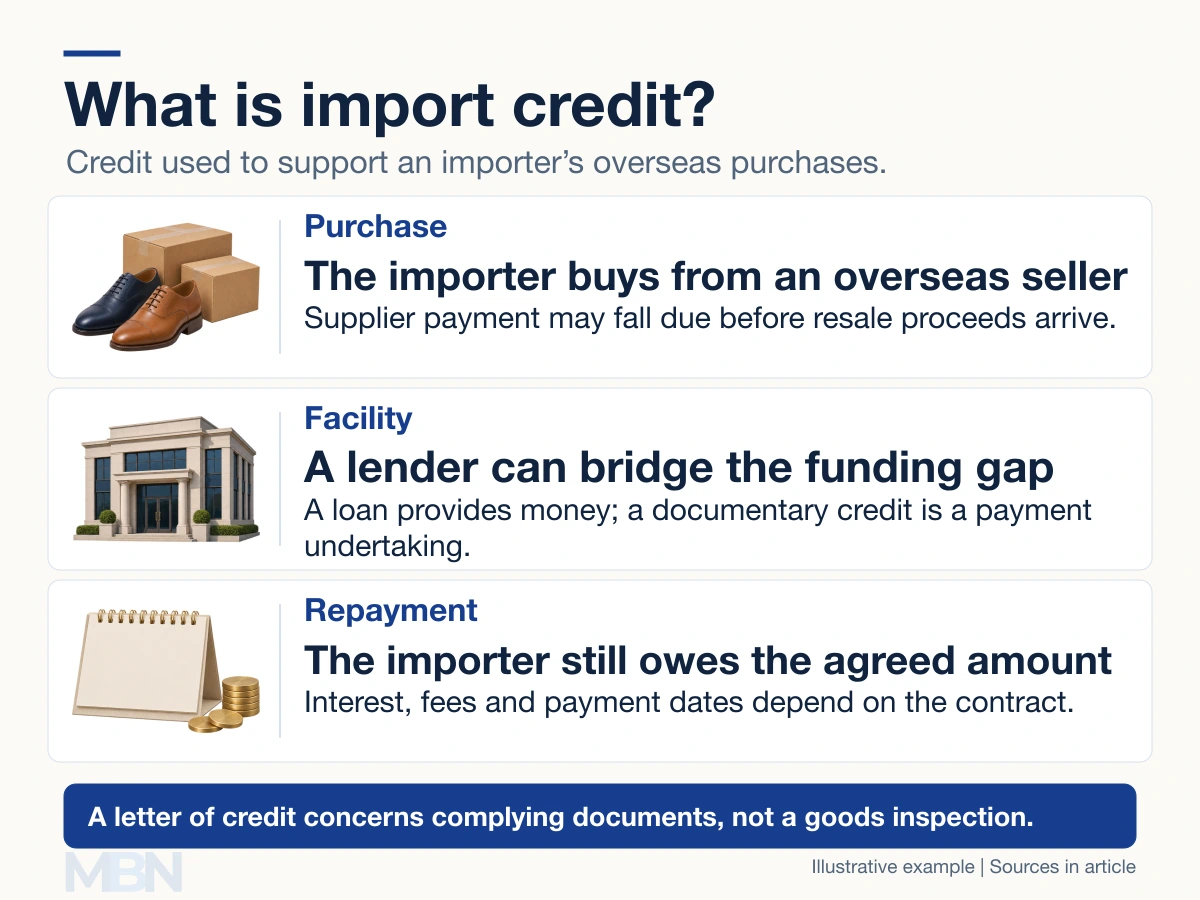
A loan and a letter of credit differ
A loan advances money that the importer must repay. A revolving credit line allows borrowing within an agreed limit under its terms.
A letter of credit, or documentary credit, is a bank’s undertaking to pay the seller when the specified complying documents are presented. It may be payable immediately against those documents or at an agreed later date.
The US International Trade Administration’s trade finance guide explains that banks deal with documents under a letter of credit. Payment is not universally triggered by the importer physically receiving or approving the goods.
A document-compliance check is not an inspection of product quality. The importer’s reimbursement obligations to the bank are also distinct from its contract with the supplier.
How import credit helps cash flow
Cash flow is the movement of cash into and out of a business. A timing gap can arise when a supplier must be paid before the business collects money from its customers.
Suppose a fictional importer pays $50,000 for goods today, using an approved loan. It sells the goods for $60,000 and receives the customer’s payment on day 60. Assume all amounts are in dollars and the customer pays on time.
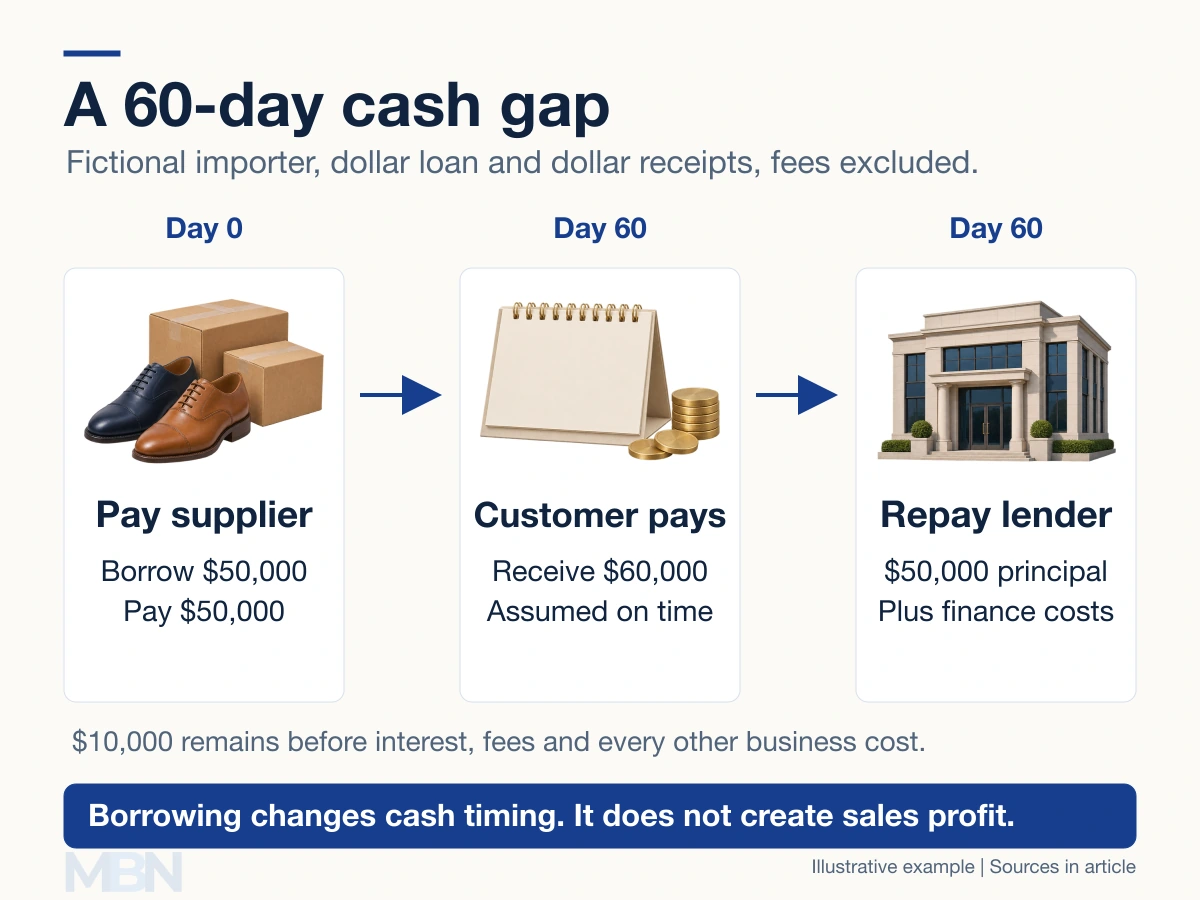
On day 60, repaying the $50,000 principal leaves $10,000 before interest, fees and all other business costs. That remainder is not net profit. The facility has bridged a payment gap rather than created additional sales revenue.
If the customer pays late, the lender’s repayment date does not automatically move. If the supplier invoice and customer receipt use different currencies, exchange-rate movements can change the amount needed to settle the debt.
Import and export finance can overlap
Import finance describes the buyer’s side of a transaction; export finance describes support for the seller or for the sale abroad. They are not separated simply by which country contains the bank.
For example, India Exim Bank’s buyer’s credit provides credit directly to eligible overseas buyers of Indian exports. From the buyer’s perspective, that supports an import.
US EXIM’s financial institution buyer credit insurance instead protects eligible lenders against specified foreign-buyer repayment risks. A loan, a guarantee and insurance are different instruments, even when they support the same trade.
Credit supplies finance, with conditions
Approval, the borrowing limit, collateral, charges and repayment schedule depend on the lender and agreement. A facility can ease a cash shortage, but it cannot establish that a purchase is profitable or that a customer will pay.
The trade finance guide’s payment-method overview also distinguishes cash in advance, open-account trade and documentary arrangements. Not every cross-border purchase needs the same instrument.
Last checked and updated on November 2, 2026 by the MBN editorial team.