
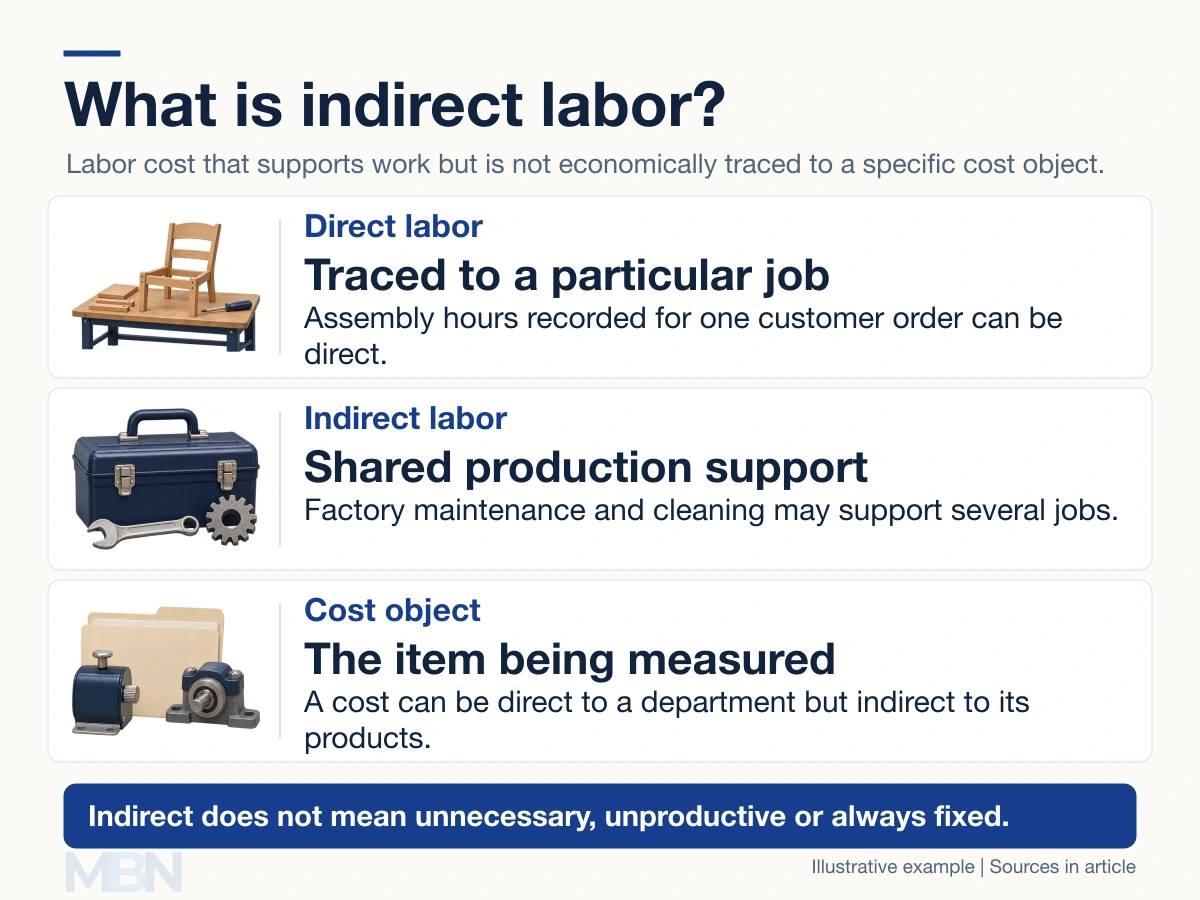
Indirect labor is the cost of work that supports an activity but is not economically traced to a particular product, job or other cost object. In manufacturing, common examples include shared factory maintenance, cleaning and supervision.
A cost object is whatever a business wants to measure the cost of, such as an order, product line or department. The distinction is about how costs are traced and assigned. It is not a judgment about how useful an employee’s work is.
How does it differ from direct labor?
Direct labor can be traced to the chosen job or product. Suppose a fictional furniture maker records two hours of assembly work on one customer order. If the relevant labor cost is $20 an hour, that order has $40 of direct labor cost.
A maintenance technician serving the whole factory may support several orders without a practical record of time for each. That cost can be indirect to those orders. OpenStax product-cost guidance explains that traceability, rather than job title alone, determines the classification.
A machine operator can therefore be direct labor when their time is reliably traced to a production job. Watching or operating automated machinery does not automatically make the labor indirect.
Does indirect labor become factory overhead?
Indirect production labor generally forms part of manufacturing overhead. That is the pool of production costs other than direct materials and direct labor. It can also include shared factory utilities, indirect materials and equipment depreciation.
Not all support salaries belong in that pool. Head-office administration and selling work are generally treated separately from manufacturing product costs. An accountant’s salary is not automatically factory overhead simply because the company makes goods.
It is also misleading to say that indirect labor cannot be included in product cost. The cost may be assigned through an allocation rather than traced directly.
How can the cost be allocated?
Allocation spreads a shared cost using a stated base. That base might be machine-hours, labor-hours or another measure appropriate to the activity. OpenStax explains overhead allocation and why businesses often use estimated rates that are later compared with actual costs.
For a simplified fictional example, a factory has $6,000 of shared indirect labor and 300 machine-hours across three jobs. Assume machine-hours are a suitable base. The rate is $6,000 ÷ 300 = $20 per machine-hour.
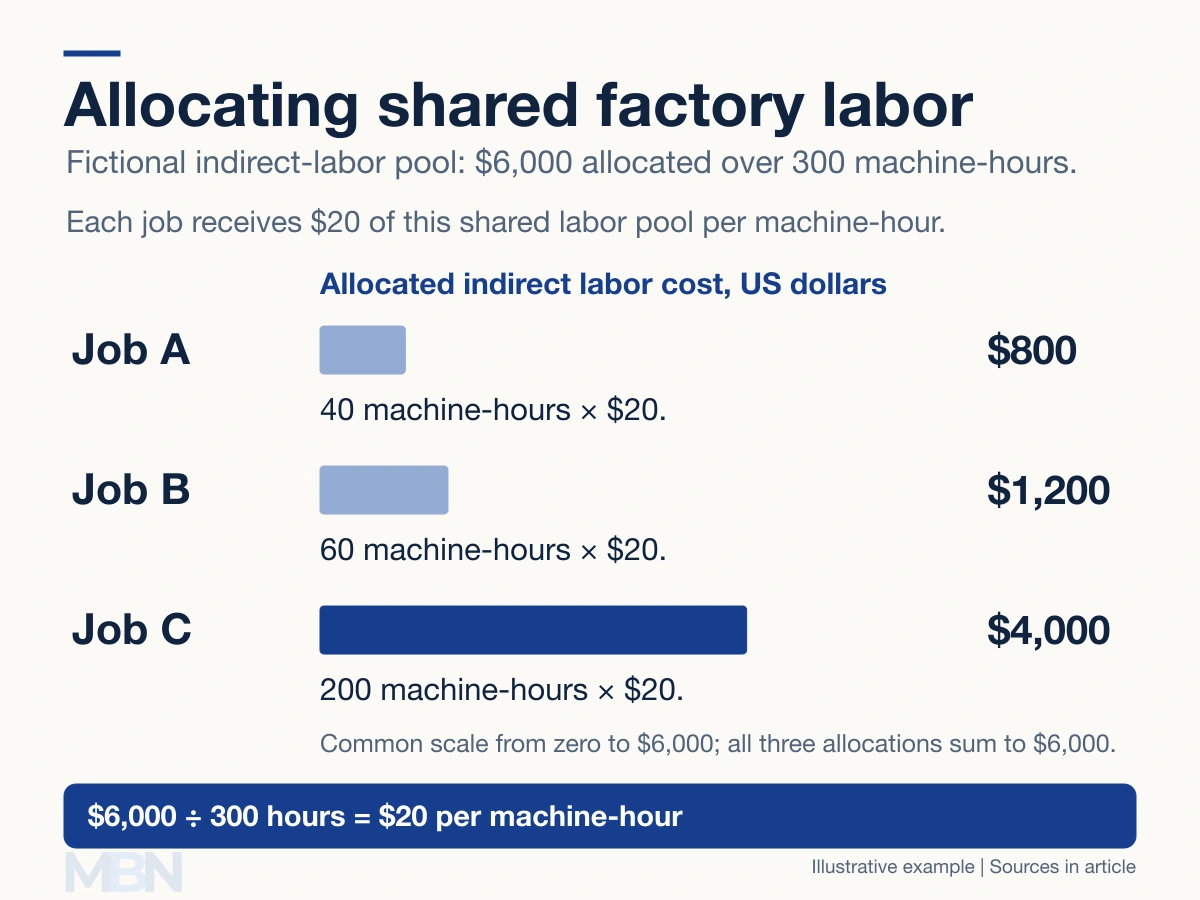
Job A uses 40 hours and receives $800. Job B uses 60 hours and receives $1,200. Job C uses 200 hours and receives $4,000. The hours total 300, and the allocations total $6,000.
This example allocates indirect labor only. Direct materials, direct labor and other overhead would still be considered in a complete manufacturing-cost calculation. The allocation is a costing convention, not a claim that each job caused precisely that amount of maintenance or cleaning work.
Is indirect labor always a fixed cost?
No. Direct versus indirect describes traceability. Fixed versus variable describes how a cost responds to activity over a stated period and range.
A supervisor’s salary might remain unchanged over a normal range of output. Some support work might instead increase with operating hours or require additional shifts once capacity expands. OpenStax cost-behavior guidance treats these as separate classifications.
Why does the distinction matter?
It helps a business understand how much cost it has traced to jobs and how much it has allocated. That matters when comparing product costs, estimating order margins or explaining changes in factory spending.
A higher allocated cost per unit does not by itself prove that support employees became less efficient. It can reflect a different allocation base, lower output or changes in the work performed. Any comparison needs the underlying quantities and costing method.
Last checked and updated on November 2, 2026 by the MBN editorial team.