
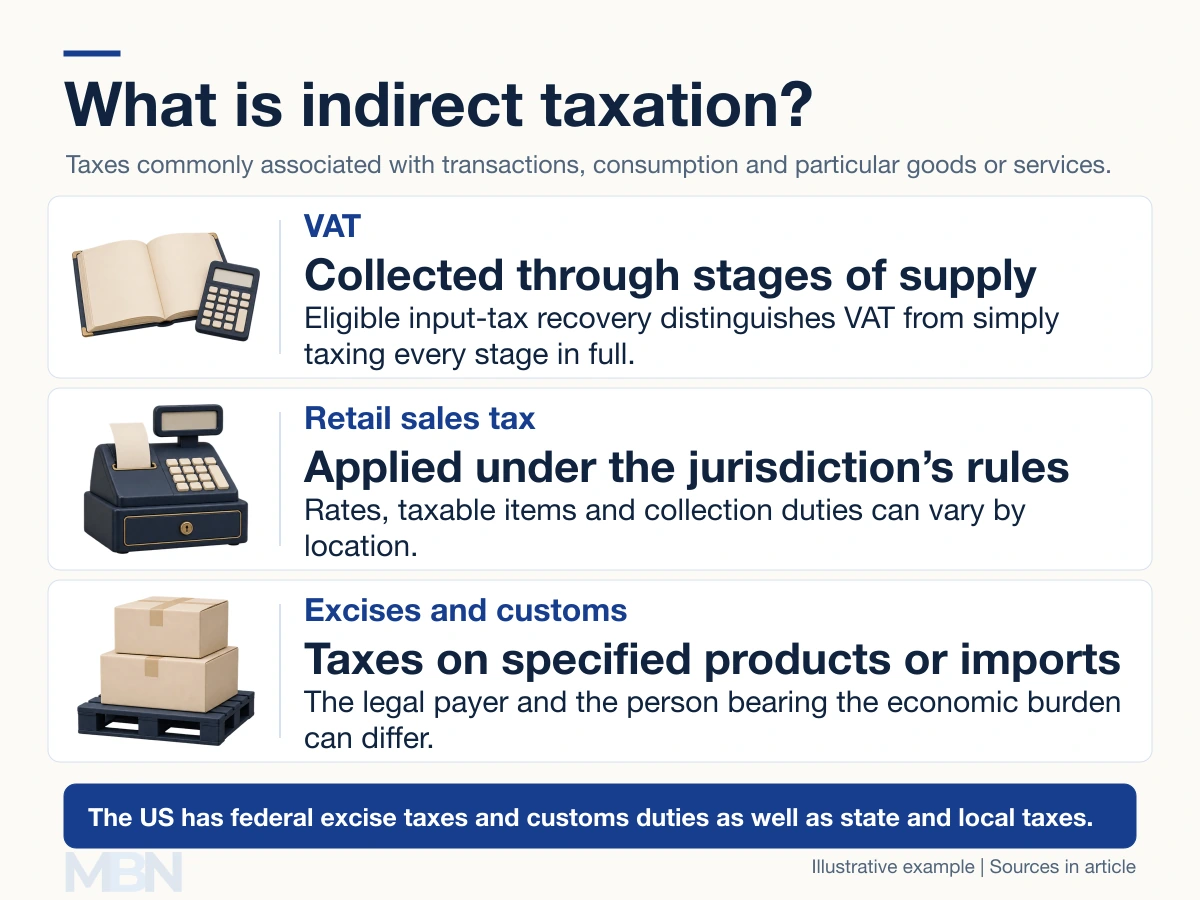
Indirect taxation commonly refers to taxes on transactions, consumption or particular goods and services, often collected and remitted by businesses. Examples include value added tax, retail sales tax, excise taxes and customs duties.
Direct taxes include taxes on personal income and company profits. The distinction is more useful than saying all tax on money coming in is direct and all tax on money going out is indirect. Collection rules and classifications depend on the jurisdiction.
The main mechanisms differ
Value added tax, or VAT, operates through stages of production and distribution. A registered business normally charges tax on taxable sales and can recover eligible tax on business purchases, subject to the rules.
Retail sales taxes generally apply at the taxable retail transaction under the relevant jurisdiction’s system. Excises concern specified products or activities. Customs duties concern covered goods crossing a border; US Customs and Border Protection collects duties on imports.
A tax may be a percentage of value, called ad valorem, or an amount per unit, called specific. Some systems combine these forms. These describe how a charge is calculated, rather than two exhaustive categories covering every indirect tax arrangement.
A UK VAT example
The UK standard VAT rate is 20%, although reduced rates, zero-rating and exemptions apply to different supplies. A zero-rated taxable supply is not the same as an exempt supply.
Suppose a fictional VAT-registered retailer buys goods for £50 plus £10 VAT, then sells them for £100 plus £20 VAT. Assume normal VAT accounting, valid invoices, full recovery of the input tax, both transactions in the same return and no other transactions.
Output VAT is £20 and recoverable input VAT is £10. The net VAT due from the retailer for these transactions is £10. Input-tax recovery has conditions and does not cover every business expense.
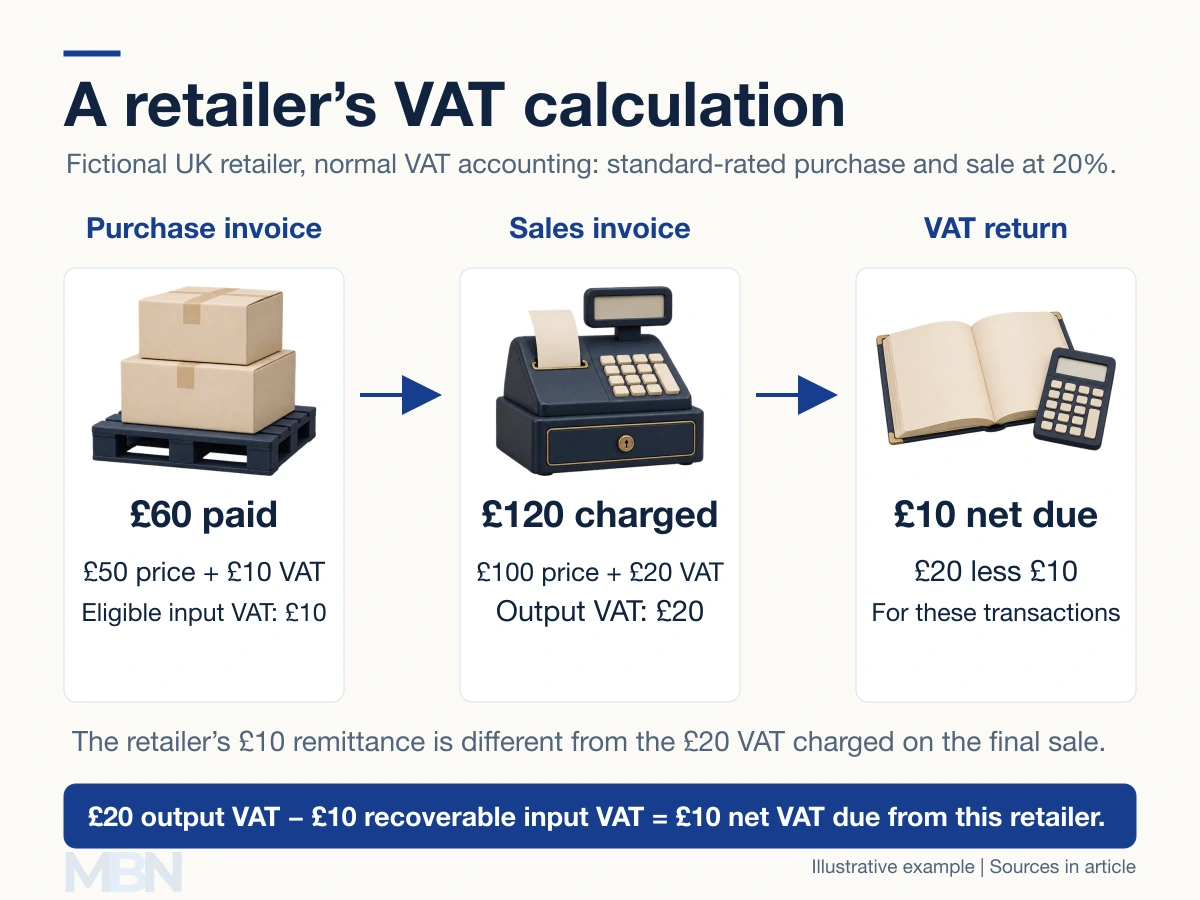
The final customer is charged £20 VAT on the £100 sale. That amount differs from this retailer’s £10 remittance because eligible tax was already charged at the earlier stage.
The US has federal indirect taxes
The US has a national tax system. The Congressional Budget Office describes federal excises on specific goods and services, including fuel, tobacco, alcohol and aviation. Customs duties are also collected federally.
Sales and use taxes operate mainly under state and local systems. A single historical state-rate range does not capture local additions, exemptions or changing collection rules. For example, California explains that district taxes can apply in addition to its statewide sales-and-use-tax rate.
Remitting tax and bearing its cost differ
The party legally responsible for paying a tax to the authorities does not necessarily bear its entire economic cost. Prices, margins and purchasing behavior can adjust.
An IMF working paper using 1999–2013 data from 17 euro-area countries found that VAT pass-through to consumer prices differed across types of tax change. That finding does not establish one pass-through percentage for every country, product or future reform.
Indirect taxes raise revenue and can also aim to change behavior. Describing them as necessarily unnoticed, unavoidable or deliberately concealed overstates what the category itself tells us.
Last checked and updated on November 4, 2026 by the MBN editorial team.