
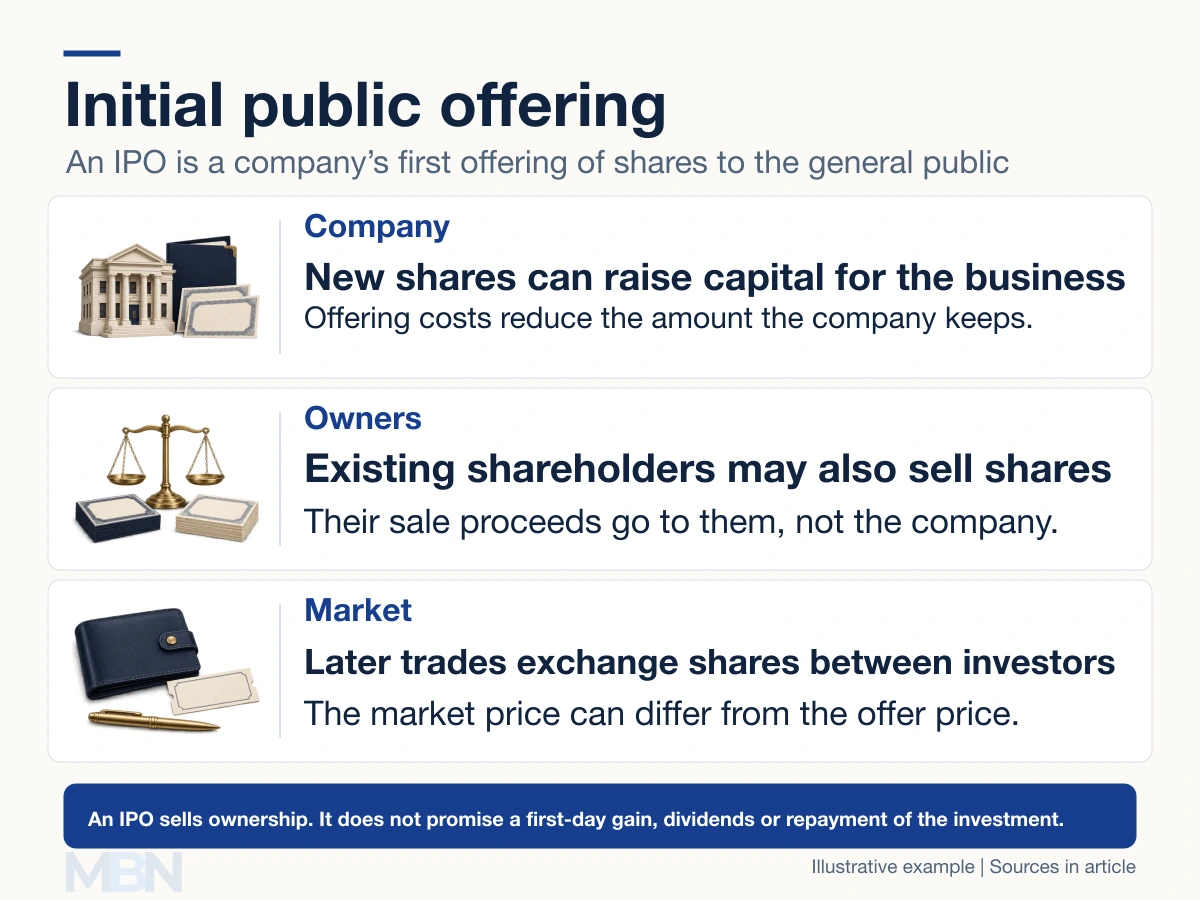
An initial public offering, or IPO, is a company’s first offering of shares to the general public. It can raise money for the business, allow existing owners to sell some of their holdings, or combine both. Buying shares means acquiring an ownership interest, with the possibility of gains and losses.
An IPO is commonly called “going public.” A stock-exchange listing often accompanies it, but an offering, a listing and the company’s public-reporting status are distinct concepts. The SEC explains that reporting obligations can arise without an IPO.
How the process works
In a conventional underwritten IPO, the company works with investment banks, lawyers and accountants to prepare the transaction. Underwriters help organize the sale and assess investor demand. Bookbuilding means collecting indications of how many shares investors want and at what prices.
In a US registered offering, the company files a registration statement, often Form S-1. Its prospectus describes the business, financial condition, management, risks and offering terms. The SEC describes the prospectus and audited financial statements included in this disclosure framework. Other countries have their own requirements.
The company and its advisers respond to regulatory comments before the sale proceeds. SEC effectiveness permits a registered offering to move forward; it is not an endorsement of the shares or an assessment that they are a good investment.
Who receives the proceeds?
Newly issued shares raise capital for the company. Shares sold by existing holders generate proceeds for those sellers. The SEC’s IPO bulletin distinguishes these selling-shareholder proceeds.
Consider a company with 4 million shares outstanding. It issues 1 million new shares at $10 each, raising $10 million before costs. Existing owners also sell 200,000 of their shares at $10, receiving $2 million before costs.
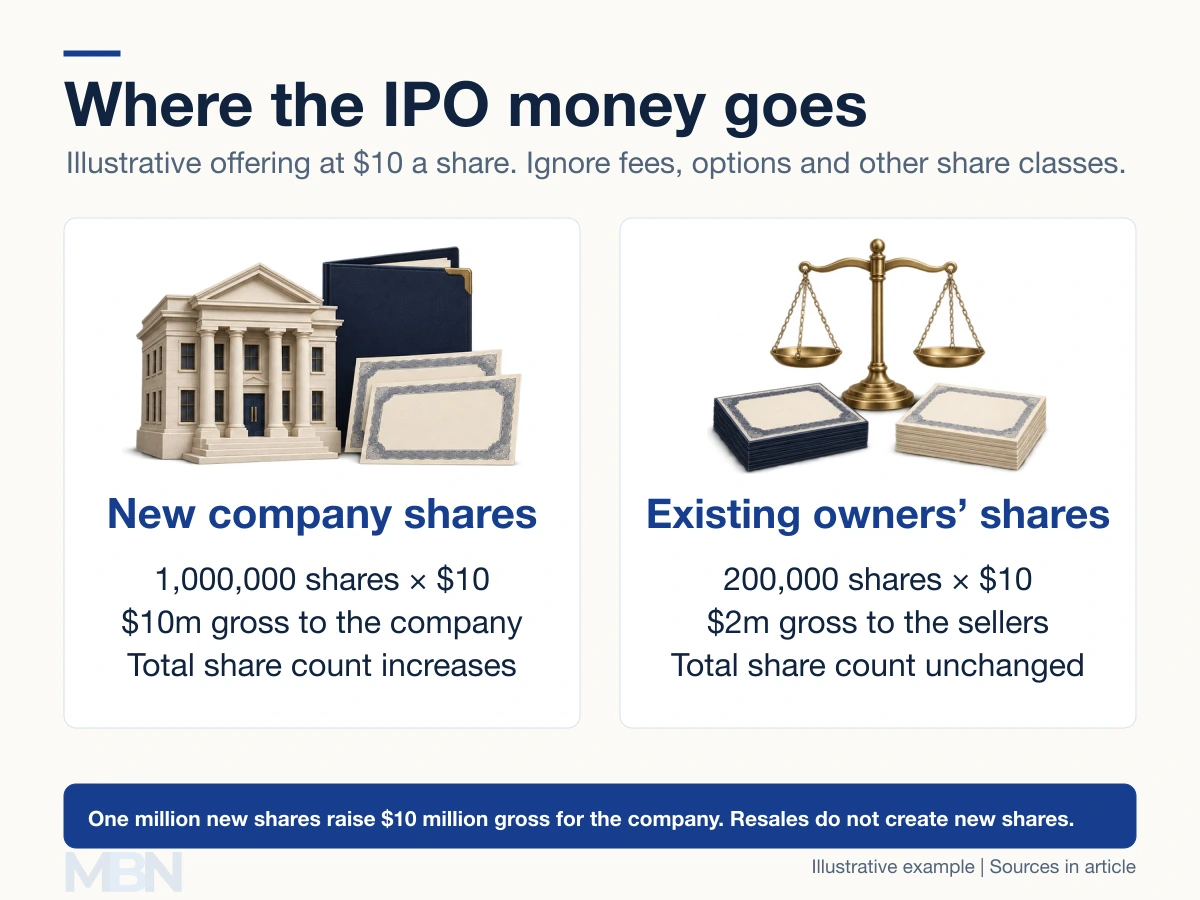
The offering’s combined gross value is $12 million, but the business does not receive all $12 million. It receives $10 million gross, from which its applicable expenses must be deducted. The resale moves ownership of existing shares without creating additional shares.
How dilution works
The new issue increases the share count from 4 million to 5 million. A shareholder retaining 1 million shares moves from 25% ownership to 20%, calculated as 1 million divided by 5 million.
This is ownership-percentage dilution. It does not by itself establish that the holding has lost value: the business has also received new capital. Voting rights may differ from ownership percentages where share classes have different votes.
Offer price versus market price
The offer price is the transaction’s agreed sale price for allocated shares. The opening and subsequent market prices reflect trading after that allocation. The SEC explains why IPO and secondary-market prices can differ.
For example, a $10 offer followed by a $13 market price is a 30% increase from the offer. Someone buying at $13 has not earned that increase. If the price later falls to $9, that buyer’s loss is about 30.8% before costs, calculated as $4 divided by $13.
Neither a first-day rise nor a later profit is assured. Access to an allocation at the offer price can also be limited. A highly publicized launch does not make every buyer’s purchase price the same.
What changes for the company?
Going public brings disclosure, governance and compliance obligations, alongside the costs of the transaction. It can broaden access to capital and provide a market for shares, but neither cheaper financing nor improved business performance follows automatically.
A public shareholding is not a loan that the company must repay at a fixed date. Dividends and returns depend on the security’s rights, the company’s decisions and subsequent performance.
Other routes to public trading
A direct listing follows a different process from a conventional underwritten IPO. Some allow existing holders to sell; permitted structures can also raise new capital. The NYSE describes its direct-listing routes. An IPO is therefore one route to public markets, rather than a synonym for every route.
Last checked and updated on November 11, 2026 by the MBN editorial team.