
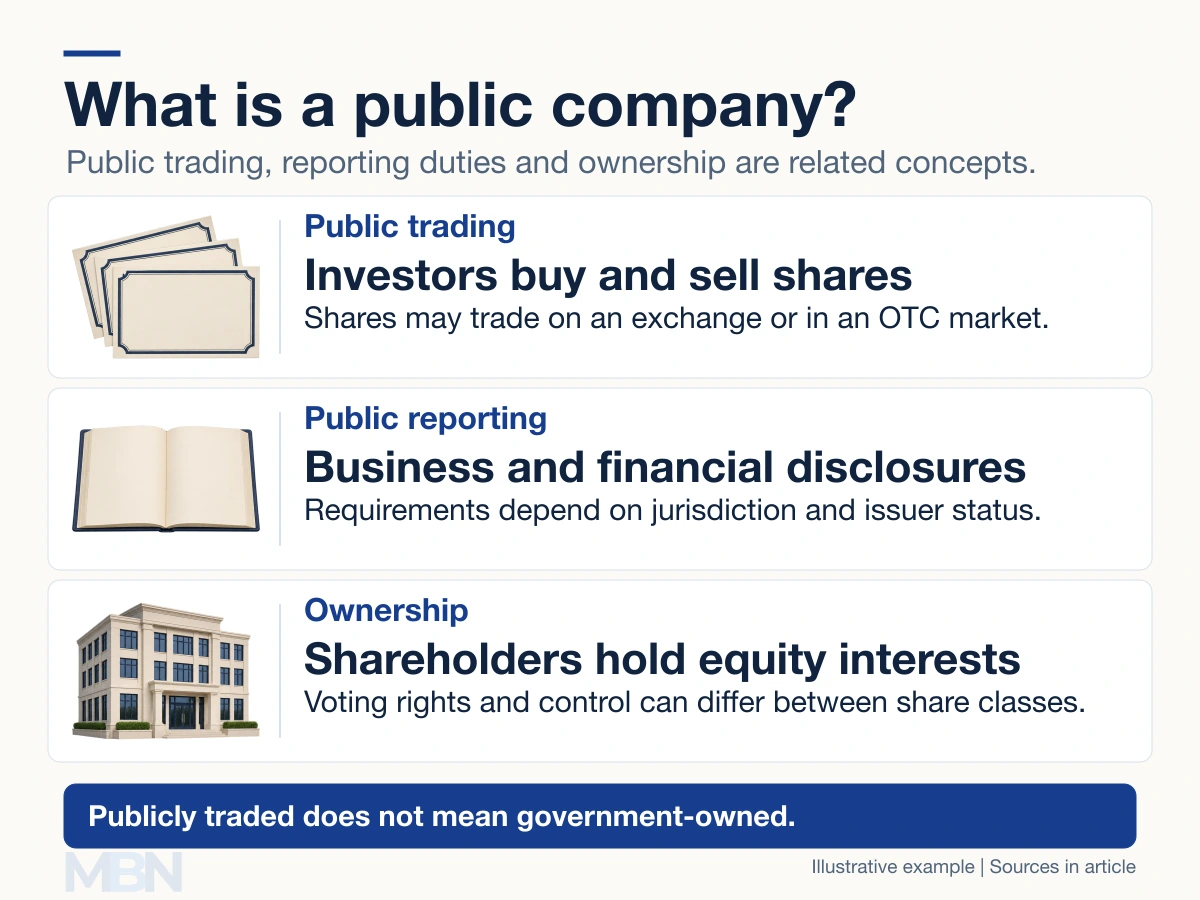
In ordinary business usage, a public company is one whose shares trade in public markets. In US securities regulation, the term is also used for companies with public reporting obligations, including some without an exchange listing.
The SEC distinguishes reporting-company status, securities offerings and exchange listings. Shares can also trade over the counter, or OTC, outside a national exchange. Public trading does not make a business government-owned.
How is it different from a private company?
Private-company shares are generally transferred through private arrangements rather than an open public market. Public trading can make ownership interests easier to transfer, but it does not guarantee a buyer, a stable price or unrestricted trading in every share.
Shareholder rights depend on the type of stock. A founder or controlling shareholder can retain substantial voting power. Management and boards run the business; required shareholder votes depend on the applicable rules and company documents.
What reporting is required in the United States?
US domestic reporting companies commonly file annual Form 10-K reports, quarterly Form 10-Q reports and Form 8-K reports for specified events. Foreign issuers and some other categories have different requirements.
The SEC’s registration guidance explains the current holder-of-record thresholds. One general Section 12(g) trigger combines more than $10 million of total assets with a class of equity securities held of record by at least 2,000 people, or at least 500 who are not accredited investors.
Exceptions and special rules apply, including separate treatment for banks and certain exempt offerings. Listing on a US exchange is another registration trigger. A blanket rule of more than 500 shareholders is therefore inaccurate.
Must a company use a traditional IPO?
No. An initial public offering, or IPO, is one route. The SEC also describes direct listings and combinations with special purpose acquisition companies, or SPACs. Reporting status can also arise through registration requirements rather than a conventional fundraising IPO.
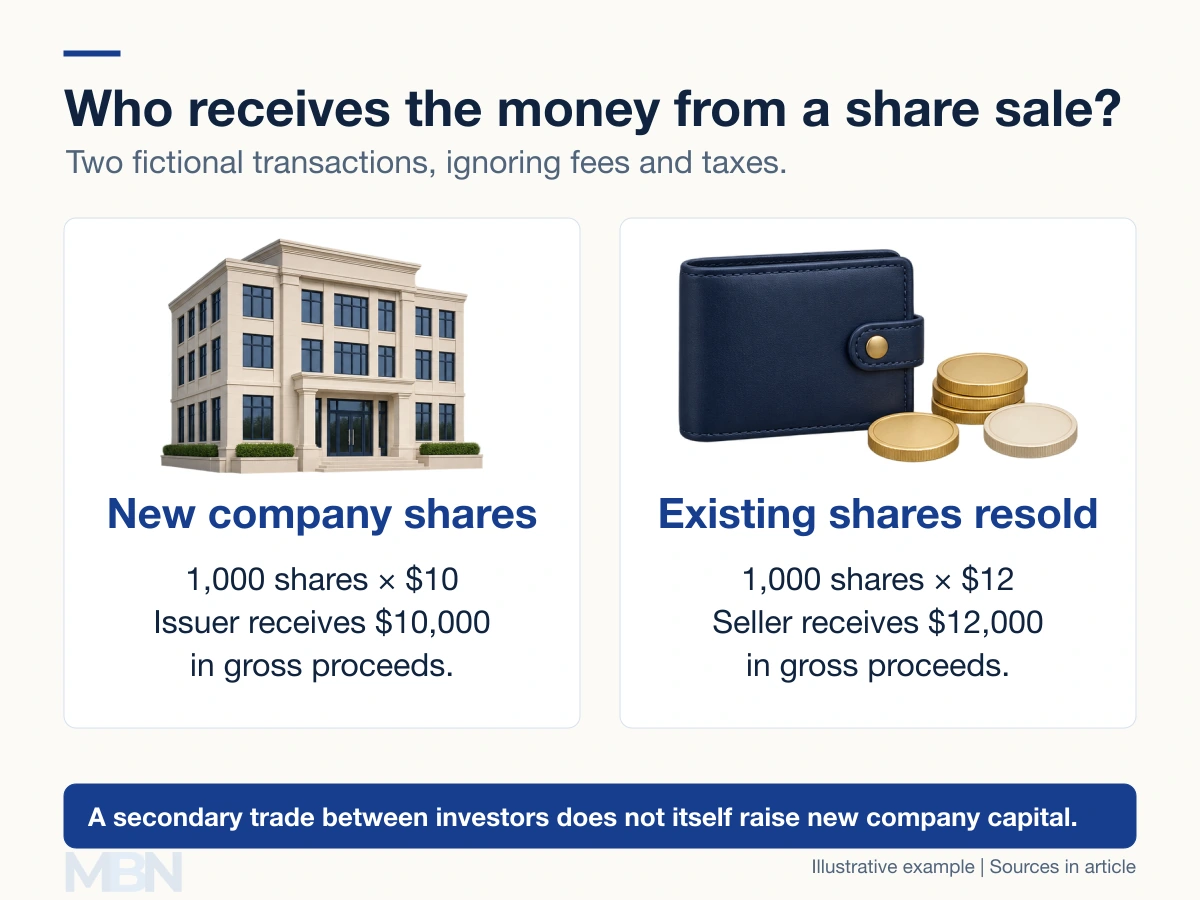
In a new share issue, the company receives the issue proceeds, before costs. When an investor resells existing shares to another investor, the seller receives that money. A public share purchase does not always put new cash into the company.
Can public and private status change?
Yes. Going-private transactions and returns to public markets can change a company’s status, subject to transaction and regulatory requirements. A change in controlling ownership alone does not automatically end reporting duties.
For a historical example, Dell Technologies announced regular-way NYSE trading in its Class C shares on December 28, 2018.
Our shares-outstanding explainer shows how share counts enter market capitalization. That calculation measures equity market value, rather than providing a complete valuation of every company asset and obligation.
Last checked and updated on November 3, 2026 by the MBN editorial team.