
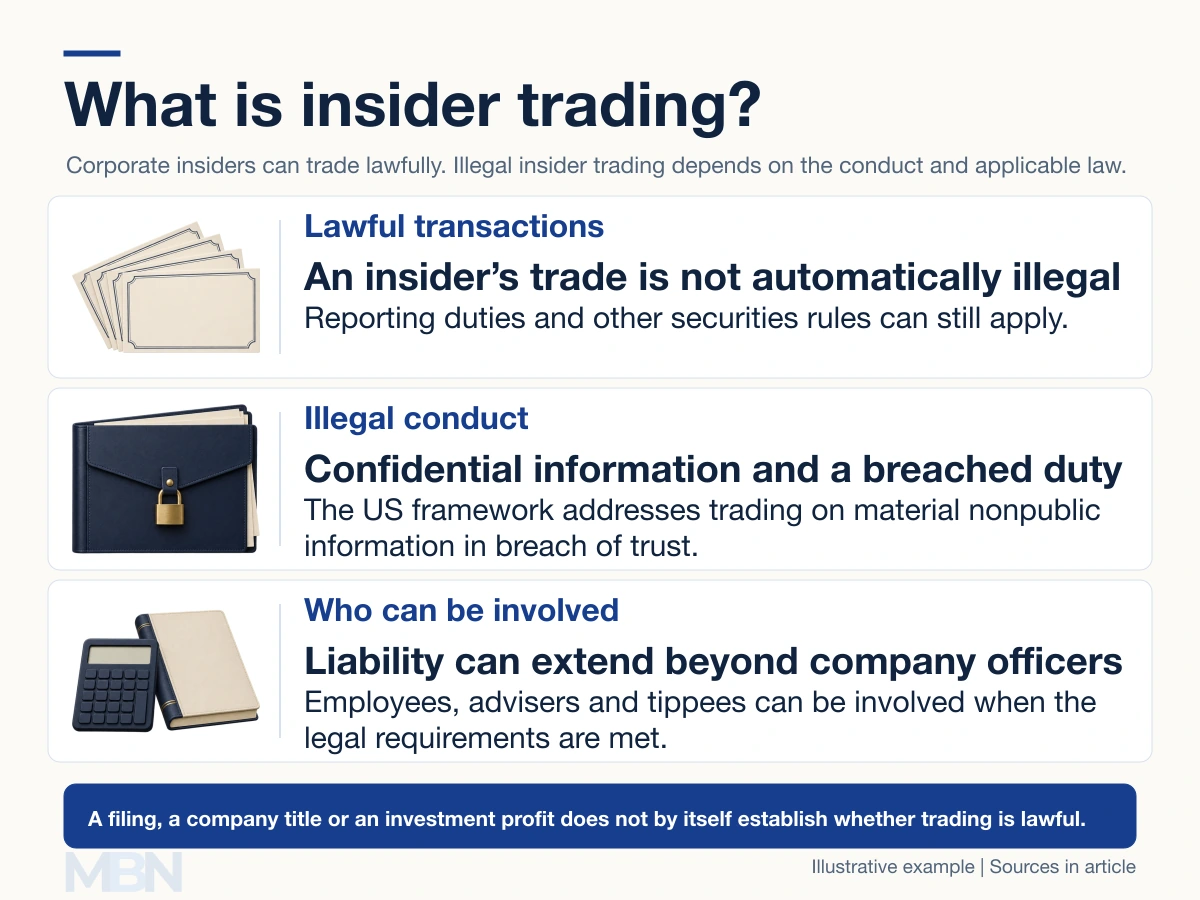
Insider trading concerns transactions in securities by people with access to information about a company. The phrase commonly refers to illegal trading on material nonpublic information, although company insiders can also buy and sell shares lawfully.
The distinction depends on the information, the trader’s duties and the applicable law. Being a director does not make every trade unlawful. Being outside the company does not automatically put a person beyond insider-trading rules.
What is material nonpublic information?
Material information is information a reasonable investor would consider important in an investment decision, assessed in context. Nonpublic information has not been generally disseminated to the market. Confidential earnings, a proposed acquisition or a major business setback can qualify, depending on the facts.
The SEC’s discussion of materiality emphasizes the information available to a reasonable investor. Materiality does not require a guaranteed price increase or fall after disclosure.
What is a corporate insider?
In US ownership reporting, covered insiders include specified officers, directors and beneficial owners of more than 10% of a covered registered class of equity securities. This is not a universal definition for every country or every employee.
SEC guidance explains the domestic-company reporting framework. Form 4 generally reports covered ownership changes within two business days. Filing a form does not authorize an otherwise unlawful trade.
Rules effective March 18, 2026 extended Section 16(a) reporting to directors and officers of covered foreign private issuers, with conditional exemptions for qualifying overseas reporting regimes. The extension does not generally cover a foreign private issuer’s shareholders solely because they own more than 10%.
What is an insider in an illegal-trading case?
A corporate title or ownership threshold is not the complete test. Investor.gov describes illegal insider trading as buying or selling on material nonpublic information in breach of a duty of trust or confidence. Conduct can involve employees, professional advisers or outsiders who misappropriate confidential information.
A person passing information is often called a tipper; a recipient is a tippee. Tipping and subsequent trading can produce liability when the applicable legal requirements are met. Receiving a piece of confidential information does not, by itself, settle every element of a case.
How the US rule treats prearranged trades
Under Rule 10b5-1, awareness of material nonpublic information when trading generally satisfies its “on the basis of” standard, subject to affirmative defenses. The rule also requires the relevant breach of duty; awareness is not the entire legal test.
A qualifying prearranged trading plan can provide a defense if adopted before the person became aware of the information and if the rule’s other conditions are satisfied. These include applicable cooling-off and good-faith requirements. Naming an arrangement a trading plan does not automatically protect it.
A trade can lose money and still be unlawful
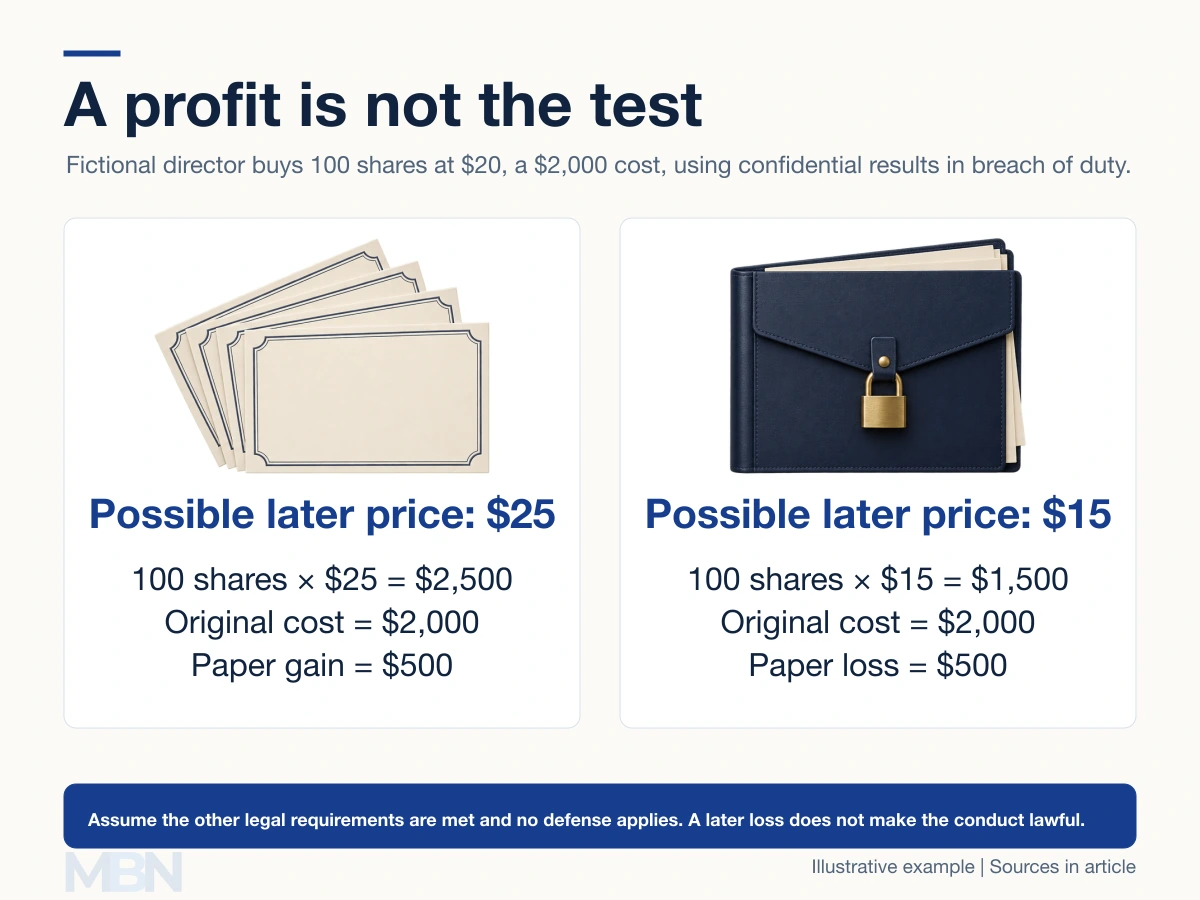
Imagine a director knowingly buys 100 shares at $20 using material, confidential results in breach of duty. Assume the other legal requirements are met and no defense applies.
If the price later reaches $25, the holding is worth $2,500, a $500 paper gain. At $15, it is worth $1,500, a $500 paper loss. Neither outcome changes the assumed wrongful conduct.
Enforcement differs between jurisdictions
In the US, the SEC brings civil enforcement actions; the Department of Justice prosecutes criminal insider-trading offenses. The UK Financial Conduct Authority addresses civil market abuse and can bring criminal proceedings. Reporting thresholds and legal tests should not be transferred wholesale between countries.
Last checked and updated on November 4, 2026 by the MBN editorial team.