
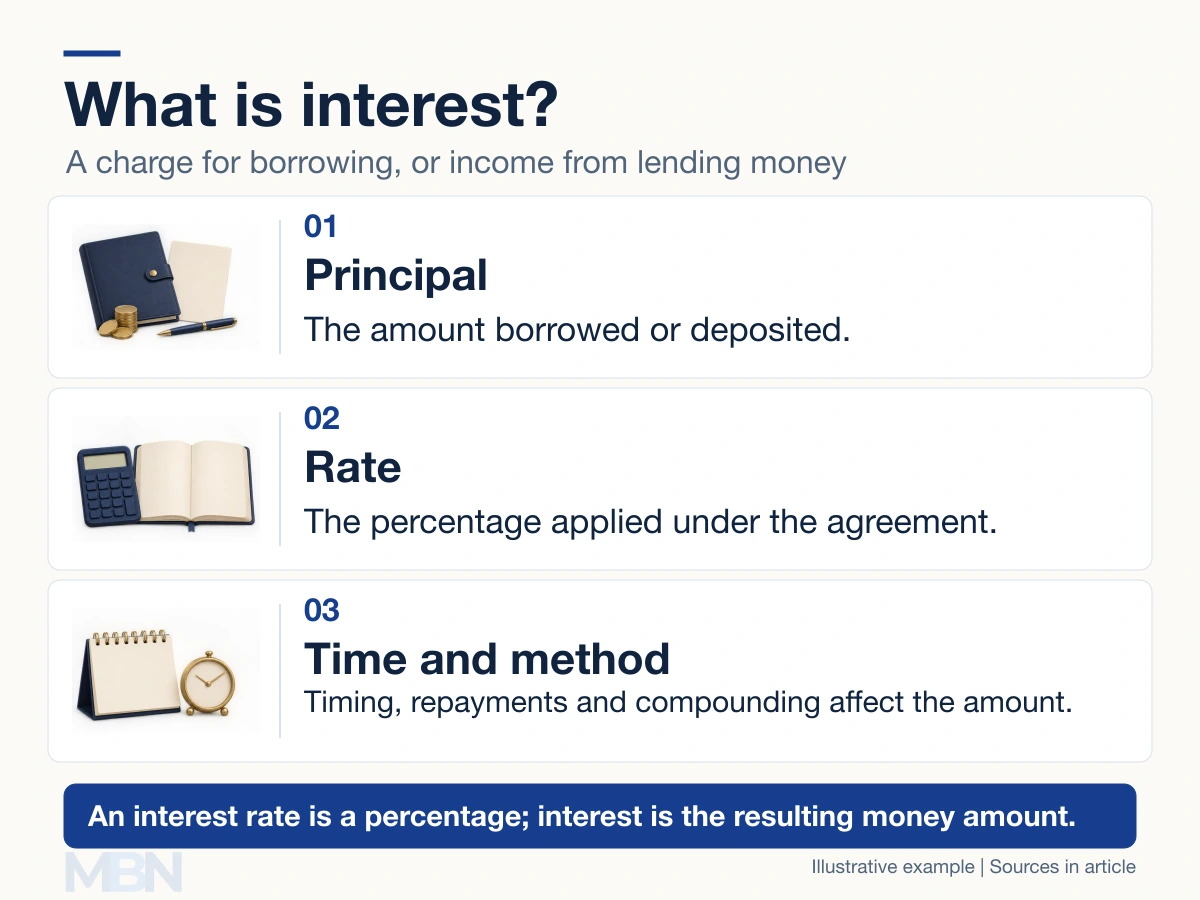
Interest is a charge for borrowing money or income earned by lending it. It is normally calculated by applying an agreed rate to the relevant balance over a period.
The principal is the amount borrowed or deposited. The interest rate is a percentage, while interest itself is a money amount. The European Central Bank’s explanation distinguishes borrowing costs, savings income and purchasing power.
What determines the interest amount?
The balance, rate, time period and calculation method all matter. With other terms unchanged, a higher rate increases the interest charge or receipt. A lower headline rate does not necessarily mean a lower total borrowing cost if fees or repayment terms differ.
A fixed rate stays unchanged for its stated fixed period. A variable rate can move under the agreement’s conditions. Rates are commonly quoted annually, even when calculations or payments occur daily or monthly.
If a £100 loan remains outstanding for one full year at 10% simple annual interest, the interest is £10. Principal plus interest totals £110, assuming no fees. Instalment repayments change the balance on which future interest may be calculated.
Simple and compound interest
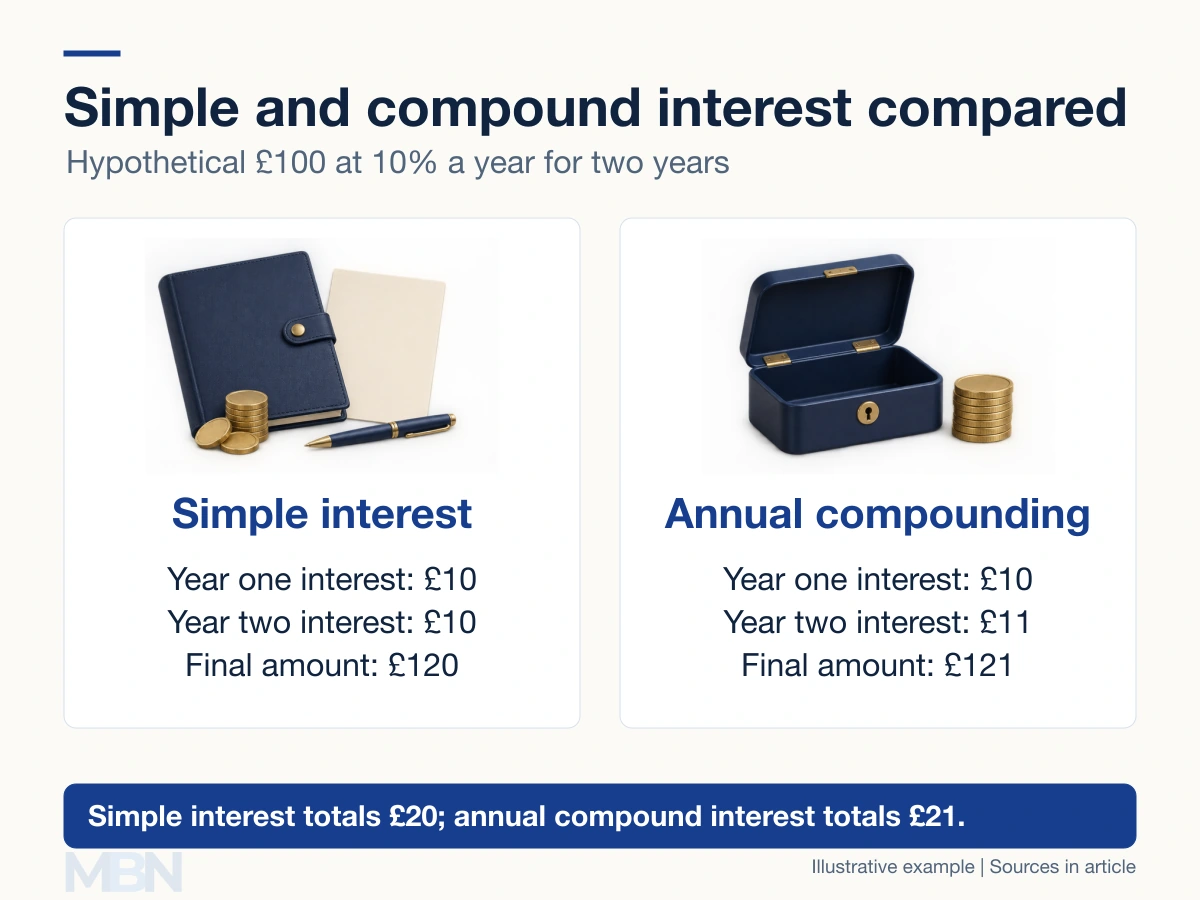
Simple interest uses the stated principal without adding unpaid interest to it for the calculation. At 10% a year, £100 produces £20 simple interest over two years, giving £120 in total.
With annual compounding, first-year interest of £10 is added to the balance. Second-year interest is 10% of £110, or £11. The final amount is £121, comprising £100 principal and £21 interest.
The CFPB explains interest earned on earlier interest. Compounding frequency matters, but a loan balance does not inevitably grow: repayments, withdrawals, fees and the contractual treatment of interest affect the outcome.
Interest on bank deposits
A bank deposit is generally a claim on the bank. Some accounts pay interest, while others do not. Minimum balances, promotional periods and other conditions can affect the rate actually received. The FDIC’s account guide notes that checking accounts may earn interest.
An interest-bearing account’s nominal balance can rise while its purchasing power falls if inflation is higher than its return. Fees and tax can reduce the net amount retained.
Interest rate, APR and APY
These measures answer different questions. For US mortgages, the CFPB describes annual percentage rate, or APR, as a broader borrowing-cost measure incorporating the interest rate and specified charges. Its rules and inclusions depend on the product and jurisdiction.
For US deposit disclosures, annual percentage yield, or APY, reflects both the interest rate and compounding under the applicable calculation rules. Comparing a nominal rate with an effective annual yield without checking the basis can be misleading.
Interest income is not the same as profit
A lender can earn interest revenue while also bearing funding costs, administration expenses and credit losses. Profit is the result after relevant income and expenses are accounted for. Receiving interest does not establish that the lending activity is profitable overall.
Interest is one application of the time value of money. Interest-free arrangements also exist, so lending does not logically require an interest charge in every case.
Video introduction
This older Wall Street Survivor introduction illustrates borrowing and compound savings. Its fixed annual loan-interest example assumes the principal remains unchanged. An amortising loan has a different balance and payment pattern. The quoted rates are illustrative.
Last checked and updated on November 5, 2026 by the MBN editorial team.