
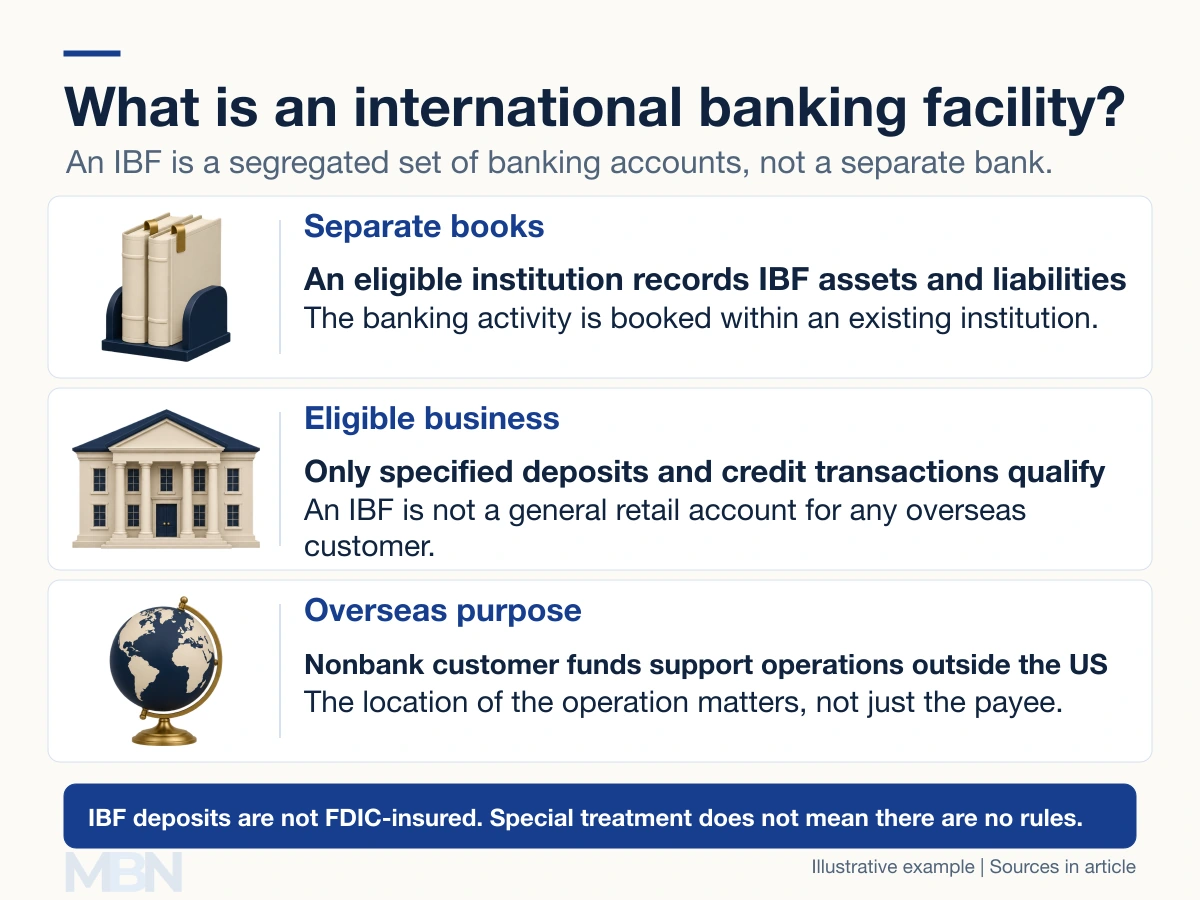
An international banking facility, or IBF, is a segregated set of asset and liability accounts within an eligible US banking office. It lets the institution record specified international deposits and loans separately from its other business.
The FDIC’s international-banking manual describes this bookkeeping structure. An IBF is not a separate legal bank, a foreign physical branch or simply one customer’s account. Its deposits are not insured by the Federal Deposit Insurance Corporation, or FDIC.
Who can establish and use an IBF?
Federal Reserve Regulation D sets the eligibility and transaction rules. Eligible operators include US depository institutions, US branches or agencies of foreign banks, and Edge or agreement corporations, which are specially authorized international-banking corporations.
Permitted counterparties include specified foreign banking offices, other IBFs, offices of the establishing institution and certain governmental or international bodies. Other eligible customers include non-US residents and foreign affiliates of US corporations, subject to the overseas-operation condition.
Eligibility therefore depends on the regulatory category and transaction purpose, rather than simply whether someone is an American citizen.
Deposit terms depend on the customer
For the nonbank-customer category, deposits generally require at least two business days’ maturity or withdrawal notice. Deposits and withdrawals must generally be at least $100,000, although a smaller withdrawal may close the account. Their funds must support operations outside the United States.
Specified banking and institutional counterparties have a separate category permitting deposits held at least overnight. The rules should not be summarized as a universal one-day minimum or unrestricted access.
What does financing overseas operations mean?
The Federal Reserve’s interpretations explain that the operation being financed matters. The recipient of a payment does not by itself determine whether a qualifying nonbank loan supports overseas activity.
For example, suppose a foreign manufacturer borrows to buy machinery from a US supplier for its factory outside the United States. Paying that supplier in the US does not itself defeat the overseas-purpose condition. Using the machinery in the borrower’s US factory would be a different case.
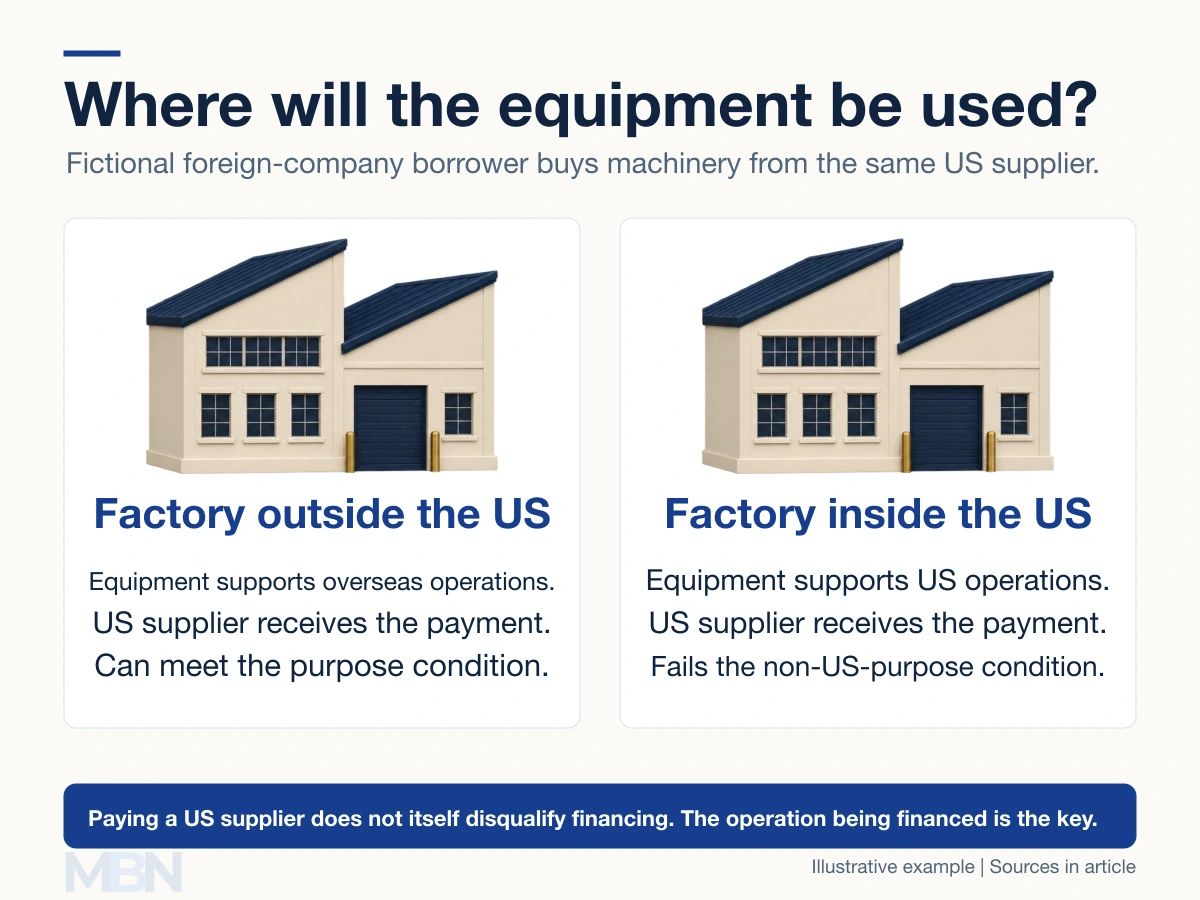
This is a purpose test, rather than automatic approval of either a customer or a loan. The other eligibility, documentation and transaction requirements still have to be satisfied.
Special treatment does not guarantee a higher return
IBFs began operating in December 1981. Federal Reserve research describes their historical reserve, interest-rate and state-tax treatment, in the context of the rules then in force.
Today, an IBF’s reserve exemption should not be presented as a unique advantage over ordinary US deposits: the Federal Reserve reduced reserve requirement ratios to zero effective March 26, 2020. Interest rates still depend on the product, institution and market.
The absence of FDIC insurance is a risk characteristic, not a promise of higher interest. Nor does IBF status establish a blanket state-tax exemption or remove the institution’s supervisory and recordkeeping obligations.
Last checked and updated on November 4, 2026 by the MBN editorial team.