
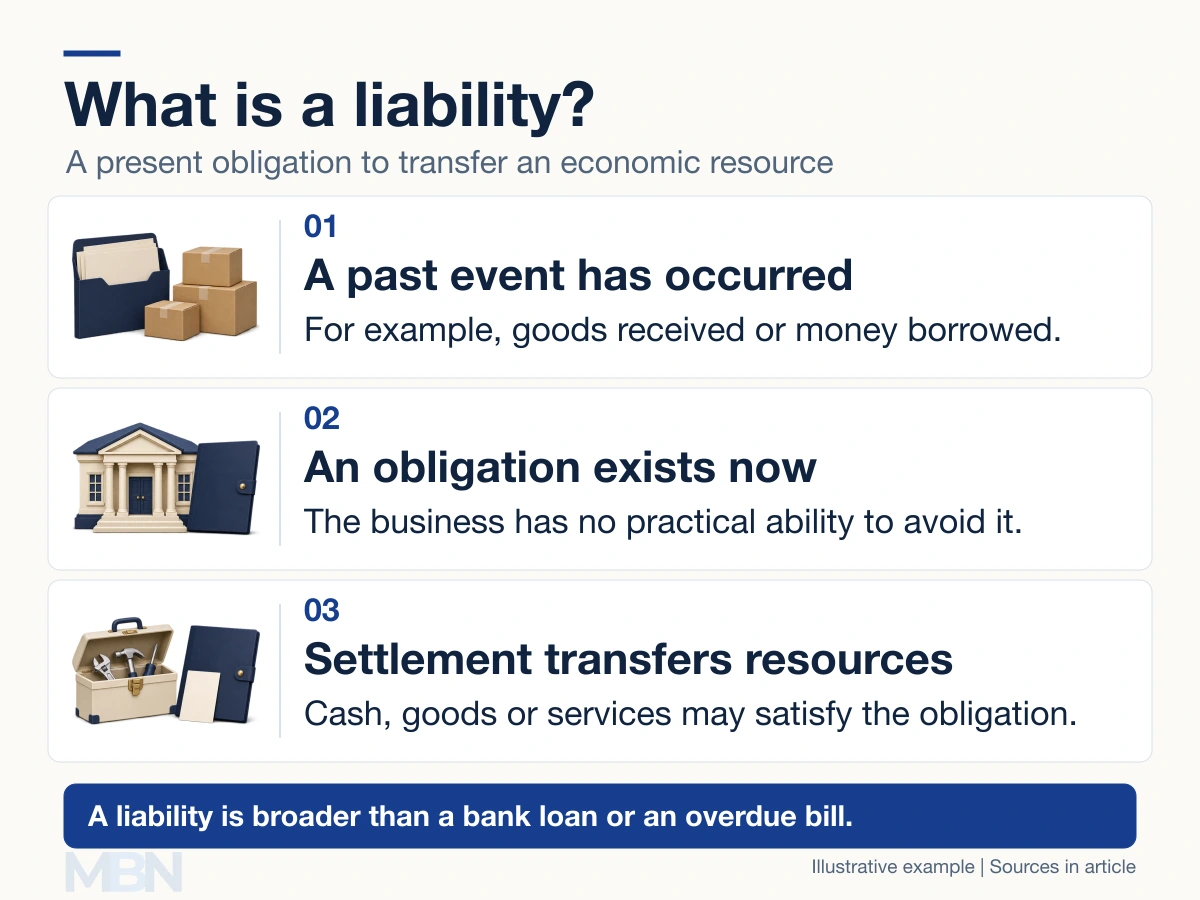
A liability is a present obligation to transfer an economic resource because of past events. It can involve paying cash, delivering goods or providing services, so the accounting meaning is broader than money borrowed.
The IFRS Conceptual Framework connects an obligation with having no practical ability to avoid the transfer. Liabilities can arise from contracts or legislation, and some arise from an entity’s actions or established practices. Recognizing and measuring them requires the applicable accounting standard.
Examples of liabilities
Bank loans, bonds payable, unpaid supplier invoices, accrued wages and taxes payable are familiar examples. An accrued expense is a cost already recognized for which payment remains due.
A customer advance can create an obligation to provide the promised goods or services. The cash received is an asset, while the unfulfilled obligation can be a liability. A bank deposit illustrates the same transaction from different sides: it is an asset of the depositor and a liability of the bank that owes the balance.
Liabilities differ from expenses. An expense affects reported performance for a period; a liability records an obligation at a date. Paying an existing supplier balance normally reduces cash and the payable, rather than recording the same expense again.
The accounting equation
Assets = liabilities + equity. Equity is the residual interest after deducting liabilities from assets. The SEC’s financial-statement guide explains this balance-sheet relationship. Liabilities do not have to appear physically on the right of every statement; layouts differ.
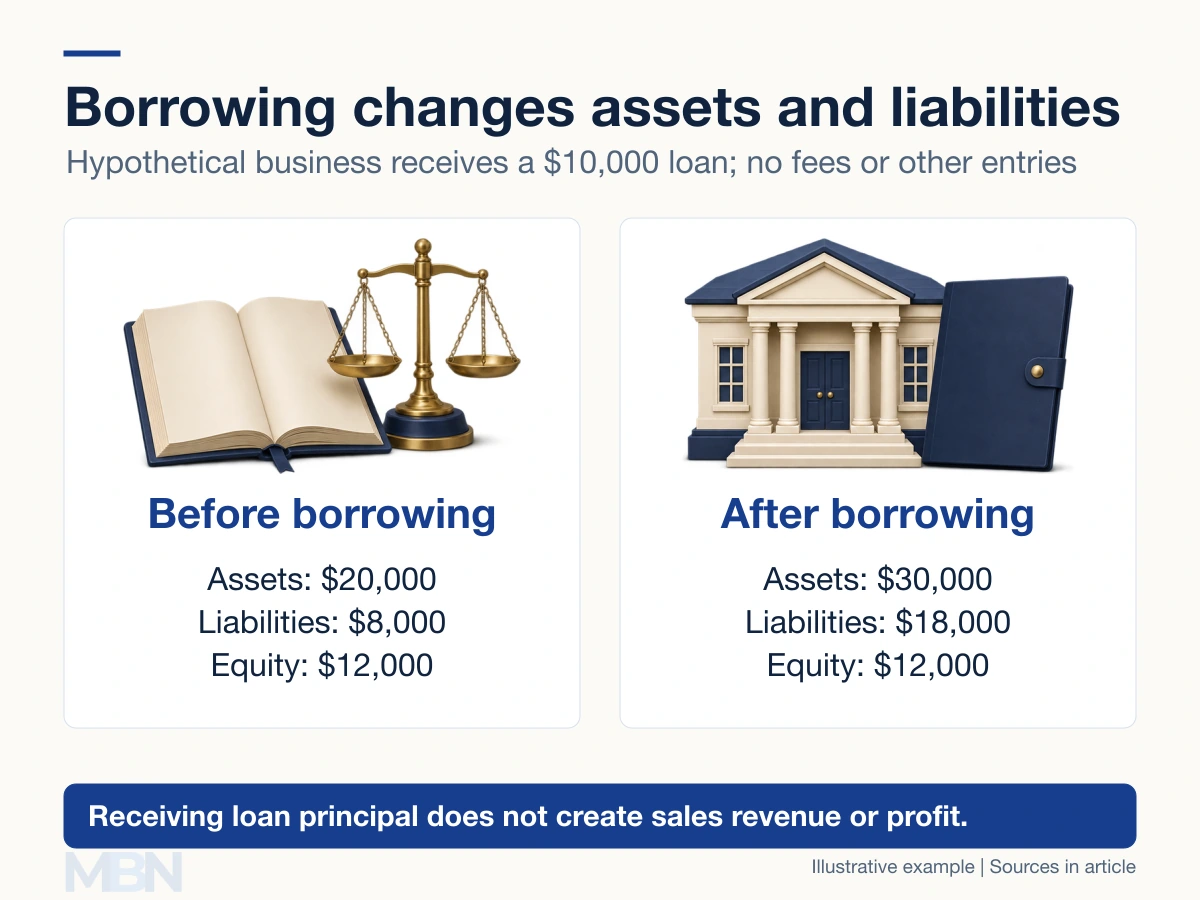
Suppose a hypothetical business has assets of $20,000, liabilities of $8,000 and equity of $12,000. It receives a $10,000 bank loan with no fees. Cash and total assets rise to $30,000, liabilities rise to $18,000, and equity stays $12,000.
Current and noncurrent liabilities
Current liabilities often include obligations due within 12 months, but the classification is not simply “this fiscal year.” Under IAS 1, the normal operating cycle, trading purpose and the right at the reporting date to defer settlement also matter.
A long-term loan may have both a current installment and a noncurrent balance. Lease and pension obligations can also contain amounts with different settlement timings. Classification is assessed under the applicable framework and contract terms.
Provisions and contingent liabilities
A provision is a liability whose timing or amount is uncertain. Under IAS 37, recognition generally requires a present legal or constructive obligation from a past event, a probable outflow and a reliable estimate. A qualifying warranty obligation is one example.
IAS 37 contingent liabilities are not recognized as provisions. They include possible obligations and certain present obligations that fail recognition conditions. Disclosure is generally required unless the possibility of an outflow is remote. Calling every probable, estimable obligation a “recognized contingent liability” mixes these categories.
A defined-benefit pension liability is also more than a comparison with cash on hand. IAS 19 uses the present value of the benefit obligation and the fair value of plan assets in determining the net position.
Liabilities and insolvency
Negative accounting equity can signal financial difficulty, but accounting balances alone do not establish every legal insolvency test. A business with assets exceeding liabilities may still lack the cash to pay debts when due.
For example, section 123 of the UK Insolvency Act addresses both inability to pay debts as they fall due and an assets-versus-liabilities assessment that includes contingent and prospective liabilities. Other jurisdictions have their own tests and procedures.
Outside accounting, legal liability means responsibility under the relevant law. Whether a contract clause excuses performance, or one person is responsible for another’s conduct, depends on the applicable legal rules and facts.
Last checked and updated on November 5, 2026 by the MBN editorial team.