
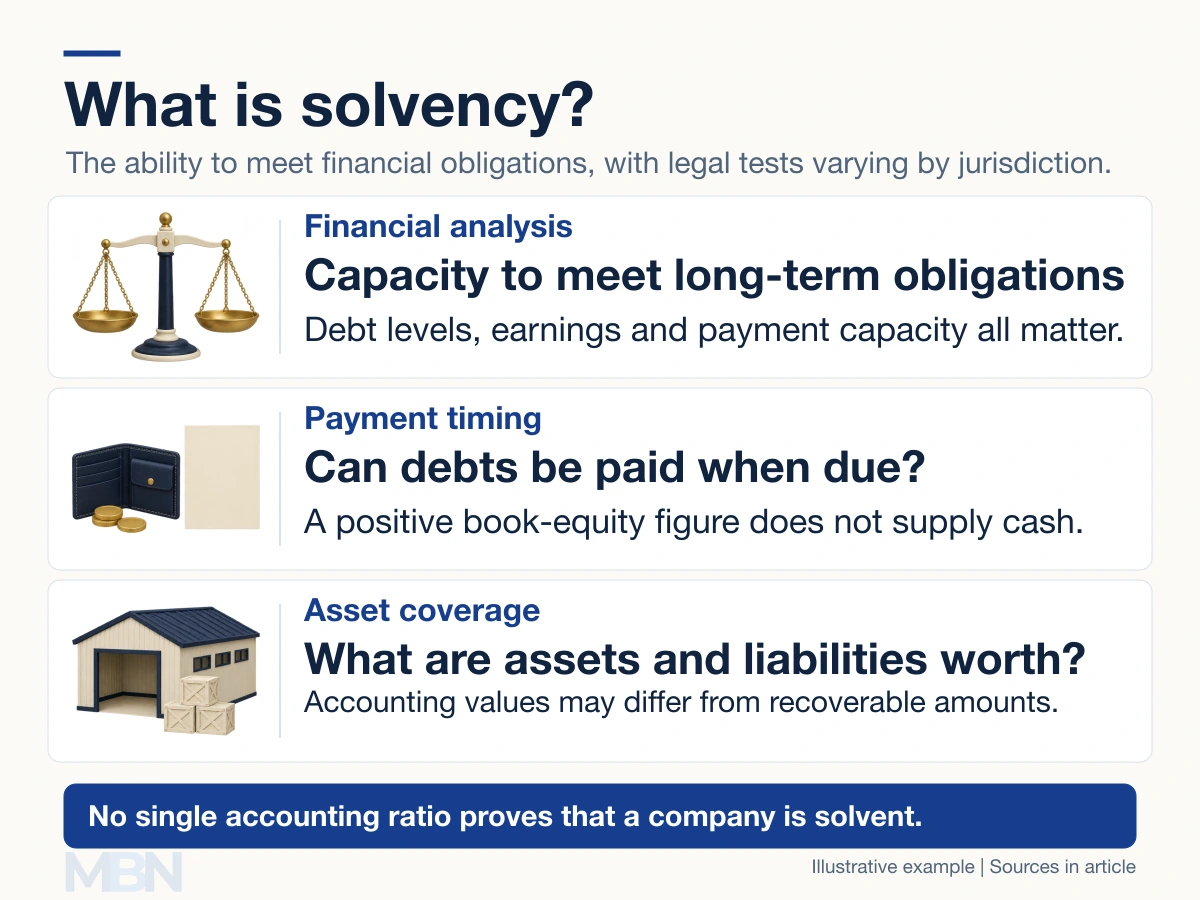
Solvency is the ability to meet financial obligations. In company analysis, it usually concerns longer-term financial strength. In law, insolvency can also arise when a company cannot pay debts as they fall due, even if its recorded assets exceed its liabilities.
A current ratio above one does not establish solvency. Nor does solvency guarantee expansion, a profit or access to a new loan.
Solvency and liquidity have different uses
CFA Institute distinguishes long-term solvency ratios from short-term liquidity ratios. Solvency measures include debt and interest-coverage ratios. Liquidity measures concern resources available for near-term payments.
A warehouse may be valuable yet impossible to sell before tomorrow’s bill falls due. Conversely, a heavily indebted business might have enough cash for today’s payments while facing difficulties later. Our liquidity explainer shows how payment timing creates a cash gap.
Why positive book equity is not conclusive
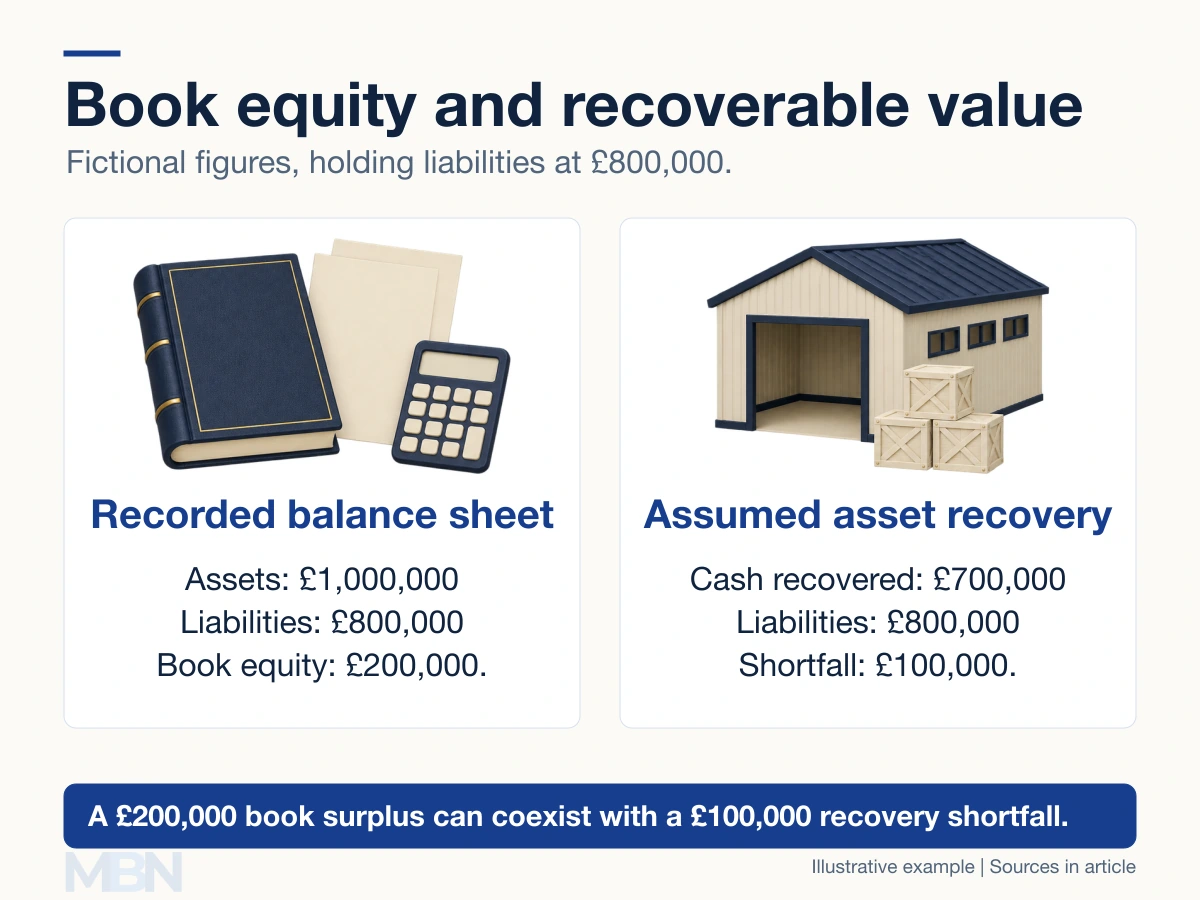
Suppose a fictional company records £1 million of assets and £800,000 of liabilities. Its book equity, the difference, is £200,000. That accounting surplus does not establish what its assets would realise in a sale.
If those assets instead produce £700,000 and liabilities remain £800,000, there is a £100,000 shortfall before costs. This is a valuation illustration, not a legal determination. Forecast receipts, enforceable funding, liability amounts and payment dates also matter.
Legal tests depend on the jurisdiction
The UK government’s September 2026 financial-distress guidance describes two tests for companies in England and Wales: inability to pay debts when due, and assets worth less than liabilities after accounting for contingent and prospective liabilities.
Contingent liabilities depend on an uncertain event; prospective liabilities concern future obligations. The tests involve more than copying totals from a published balance sheet. Either test can matter, and rules for other jurisdictions or types of entity may differ.
The House of Commons Library’s 2026 insolvency briefing distinguishes rescue procedures from liquidation. Insolvency does not invariably mean that a business immediately closes, or that simple cost reductions will restore it.
What do the ratios actually measure?
The current ratio divides current assets by current liabilities. Inventory classified as current is included. The usual quick ratio excludes inventory and prepayments, using cash, short-term investments and receivables.
The SEC describes financial statements as connected sources of information. Debt ratios show financing exposure; interest coverage relates earnings to interest expense. Their definitions, industry context and trends matter.
There is no universal ratio called simply “the solvency ratio” with a threshold that proves every company solvent. A single asset-to-liability calculation cannot replace cash-flow analysis, valuation work or the applicable legal tests.
Last checked and updated on November 3, 2026 by the MBN editorial team.