
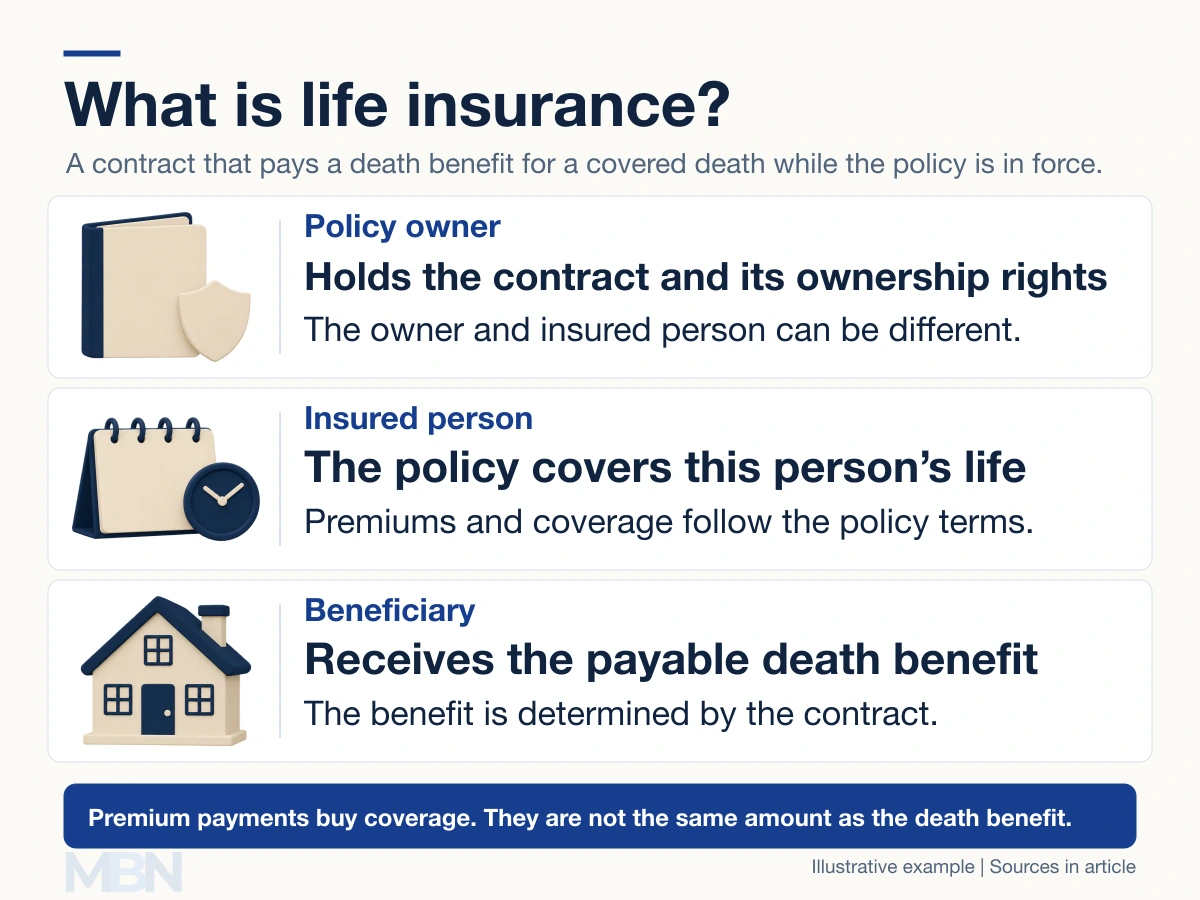
Life insurance is a contract under which an insurer pays a death benefit when the insured person dies while covered, subject to the policy’s terms. Premiums pay for that coverage. The person who owns the policy and the person whose life is insured need not be the same.
The beneficiary is the person or entity designated to receive the payable benefit. Ownership rights, beneficiary arrangements and consent requirements depend on the contract and applicable law.
How does term life insurance work?
The NAIC’s 2026 buyer’s guide distinguishes term insurance from cash-value insurance. Term insurance covers an agreed period. A level-premium term policy keeps the scheduled premium unchanged for a specified period, but not every term policy has this structure.
If the covered person survives a standard term with no return-of-premium feature, the policy ends without a maturity payment. Renewal or conversion may be available under stated conditions. Renewal premiums can be higher.
A term-policy example
Our fictional policy provides $300,000 of cover for 20 years at $25 a month. It has no cash value, return-of-premium rider or renewal. The premium is purely illustrative.
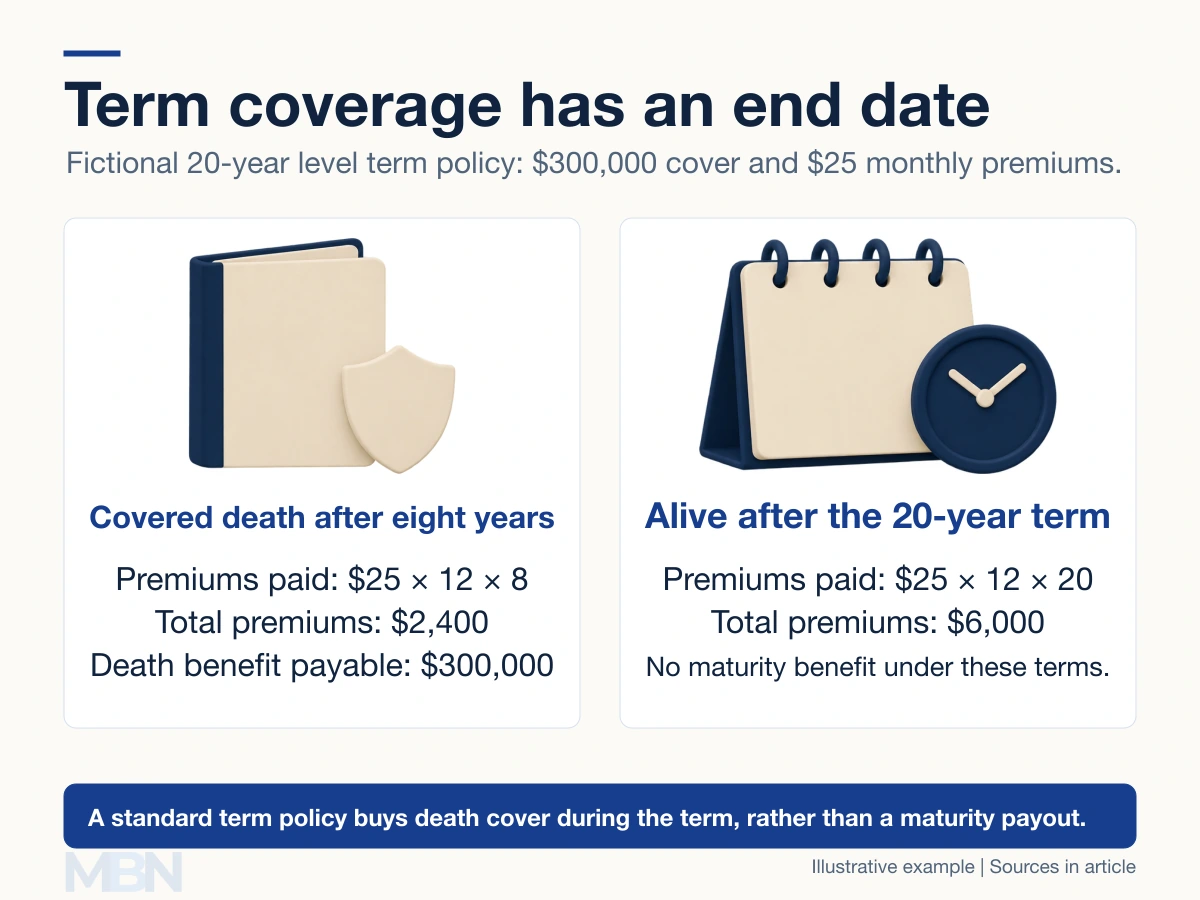
If a covered death occurs after eight full years of payments, premiums total $2,400 and the stated death benefit is $300,000. If the person survives the full term, premiums total $6,000 and there is no maturity benefit under these terms.
The death benefit is a contractual coverage amount, rather than a refund of accumulated premiums. A claim still depends on the policy being in force and its conditions being met.
What does permanent life insurance mean?
Permanent policies are designed for long-term coverage and commonly include cash value. Whole life typically has scheduled premiums and contractual cash-value guarantees. Universal life can allow flexible premiums, but changing payments affects the policy’s funding.
The Texas Department of Insurance explains that insufficient funding can cause a universal-life policy to lapse. A no-lapse guarantee, where offered, has its own conditions. Flexible premiums do not mean coverage continues indefinitely without adequate funding.
Cash value is distinct from the death benefit. Withdrawals, surrender charges and outstanding loans can affect the policy or eventual payment. Nonguaranteed illustrations and policy dividends are not promises of future results.
Are limited-pay and endowment policies different?
Yes. New York DFS describes limited-payment whole life as lifetime protection funded by a limited number of premiums. A ten- or twenty-year payment schedule does not mean the death benefit is automatically paid when those premiums end.
An endowment contract instead provides a specified payment on death within a stated period or survival to maturity. Availability and tax classification vary across markets. It should not be presented as the same arrangement as ordinary lifetime cover.
Are death benefits tax-free?
Tax treatment varies by jurisdiction and circumstances. The IRS says US beneficiaries generally exclude proceeds received because of the insured person’s death from gross income. Interest is taxable, and a transfer for value can limit the exclusion, subject to exceptions.
That US income-tax rule does not settle every estate, inheritance or foreign-tax question. Policy exclusions, application disclosures, lapse rules and claim procedures also require the relevant contract and local law.
Last checked and updated on November 3, 2026 by the MBN editorial team.