
Liquid assets are cash or assets that can be converted into cash quickly without materially moving their market price. Liquidity concerns access to money, including the time, cost and price impact of a sale.
There is no universal one-month cutoff. A readily saleable asset can also have fallen sharply in value since purchase. Liquidity does not mean its selling price will equal its original cost.
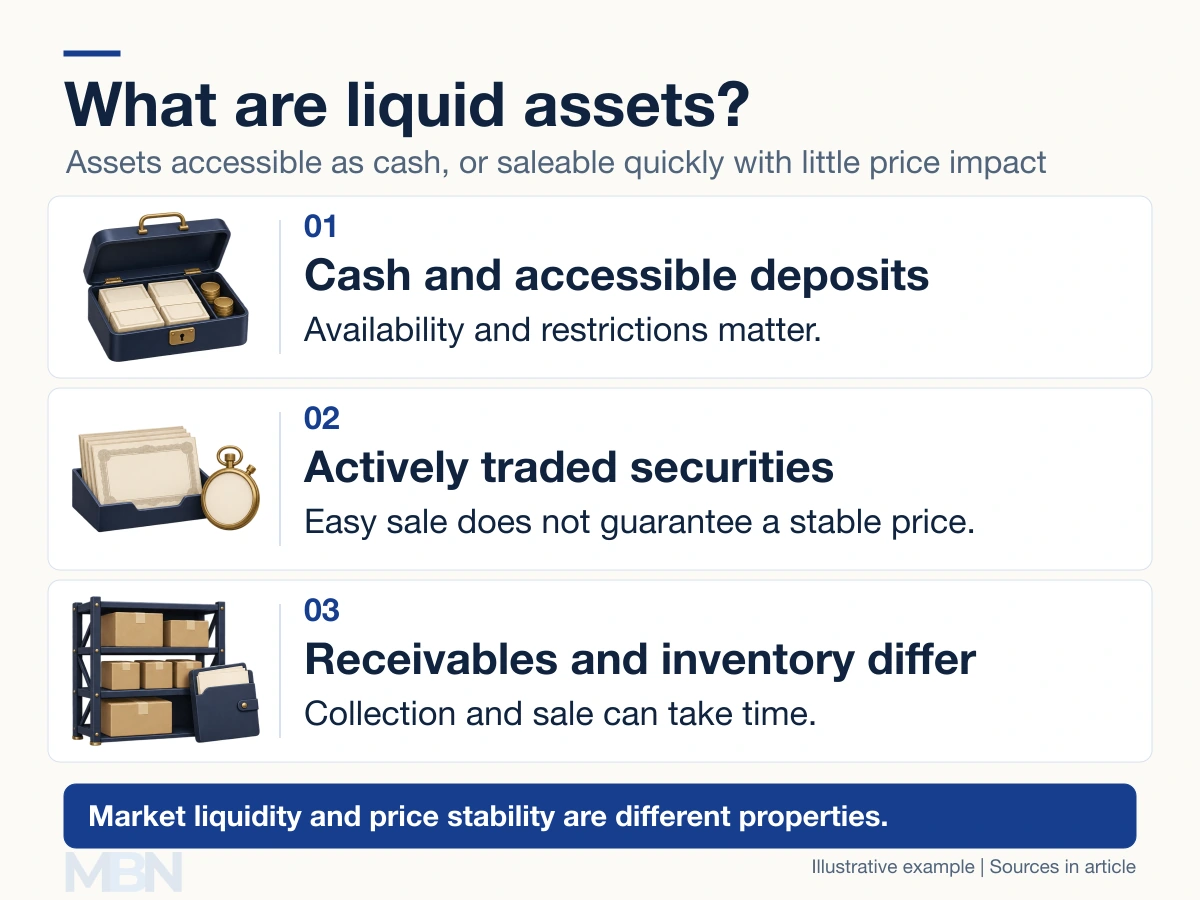
Examples and important limits
Cash and accessible demand deposits provide direct spending capacity. Widely traded government securities and actively traded shares can also be liquid, although their prices and trading costs vary. A small trade may be easy to execute while a much larger one moves the market.
Term deposits can have withdrawal restrictions or penalties. Gold’s liquidity depends on its form, the market and dealer spreads. A private-company share or an unusual collectible may take much longer to sell at an acceptable price.
A securities sale also has a settlement period before the transaction is completed. Investor.gov explains US T+1 settlement, generally one business day for covered transactions. That rule does not make every security equally saleable or establish an international settlement rule.
Liquid assets are not all cash equivalents
IAS 7 defines cash equivalents more narrowly as short-term, highly liquid investments convertible into known cash amounts with insignificant risk of changes in value. A volatile listed share can trade readily without qualifying as a cash equivalent.
Restrictions and pledged assets can also limit availability for paying bills. An investment’s quoted value alone does not establish that the holder can use that amount immediately.
Current assets and quick assets
Current assets form an accounting category that can include inventory, receivables and prepayments. They are not all immediately liquid. Inventory usually must be sold, and customers may pay receivables late or default.
Quick assets are used in a more selective liquidity calculation. They commonly include cash, short-term marketable investments and receivables, while excluding inventory and prepayments. Definitions differ, so the formula used should be stated. ACCA explains why its quick-ratio calculation excludes inventory and why operating context matters.
A worked liquidity-ratio example
Suppose a business has $20,000 cash, $30,000 short-term marketable securities, $40,000 receivables, $60,000 inventory and $10,000 prepayments. Its current assets total $160,000 and its current liabilities are $100,000.
The current ratio is 1.60. Excluding inventory and prepayments leaves $90,000 quick assets and a quick ratio of 0.90. If the securities are not cash equivalents, cash and cash equivalents total only $20,000, producing a cash ratio of 0.20 under that formula.
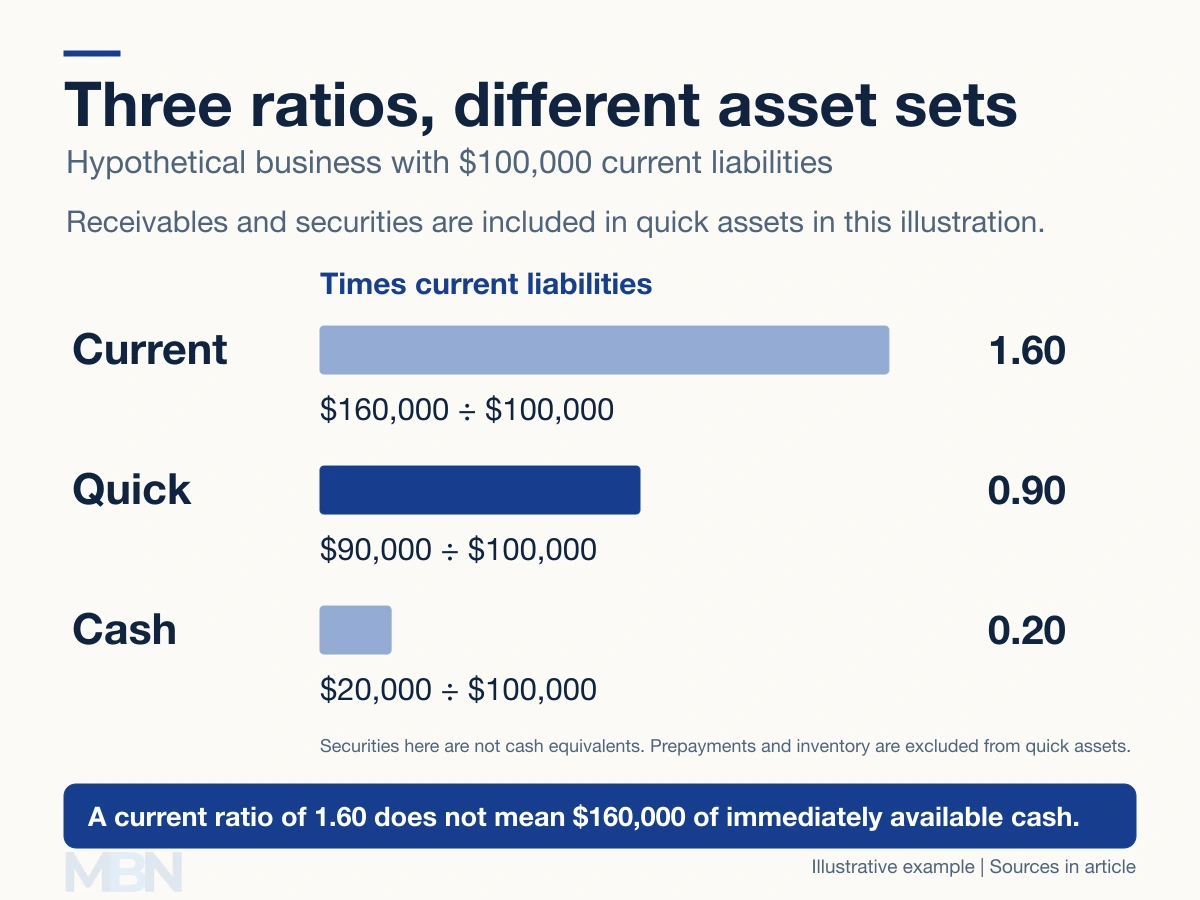
These ratios are snapshots. They do not reveal exactly when customers will pay or bills will fall due. A firm can have substantial assets and still face a cash shortage before those assets become usable money.
What bank regulations mean by liquid assets
The Basel liquidity coverage ratio framework uses a specialized category called high-quality liquid assets, or HQLA, for banks facing a prescribed 30-day stress scenario. Eligible assets have detailed conditions, with Level 1 and Level 2 classifications, valuation haircuts and limits.
Those regulatory categories are not a general definition for every company or household. They should be read alongside the applicable local banking rules.
Last checked and updated on November 5, 2026 by the MBN editorial team.