
Liquidity describes access to cash when needed and the ease of buying or selling an asset without a substantial price impact. A liquid asset can still be risky, and a valuable asset may be difficult to turn into cash quickly.
Investor.gov defines market liquidity in terms of how easily and quickly securities can be traded. For businesses and households, the term also concerns meeting payments as they fall due.
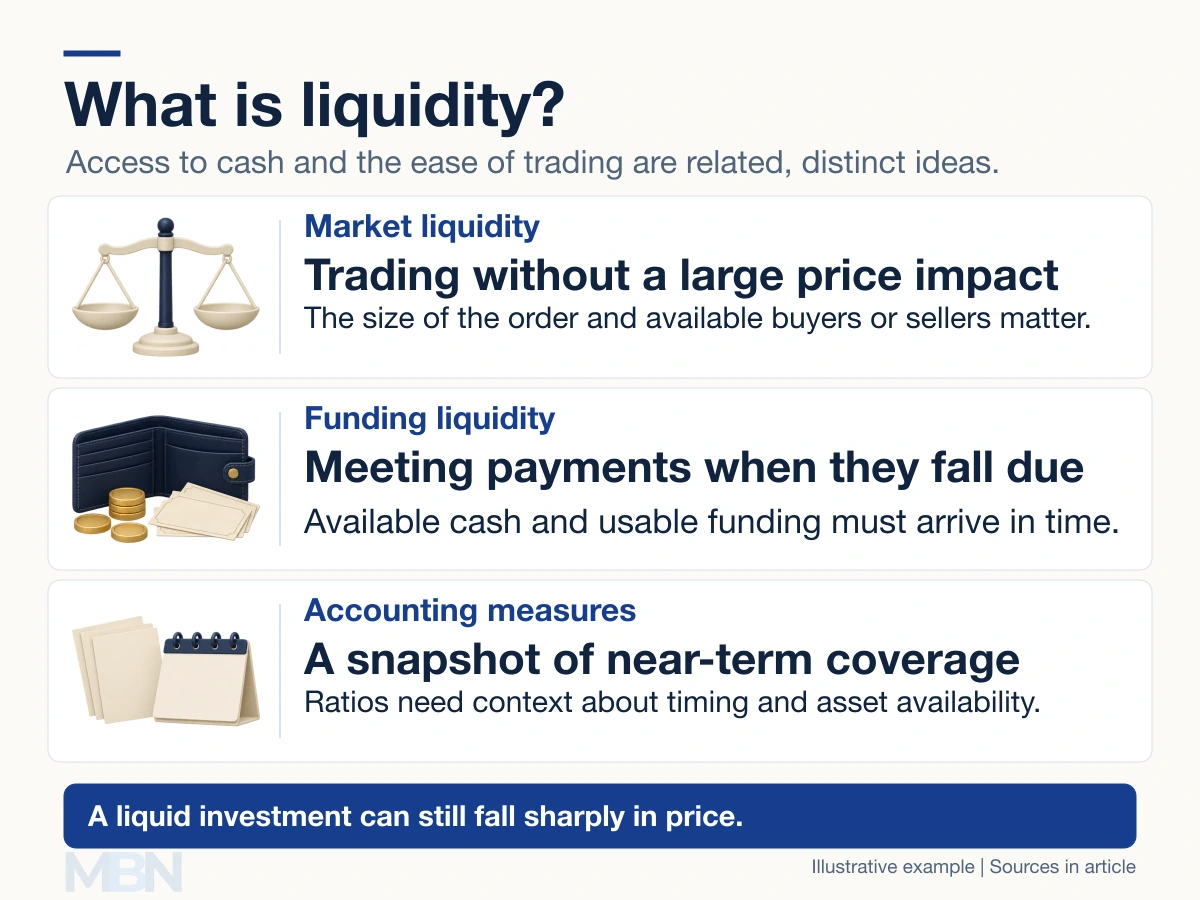
Market liquidity depends on price and trade size
A market may absorb a small order readily but require a price concession for a much larger one. A narrow bid-ask spread, the gap between buying and selling quotations, is one useful sign of trading conditions.
The SEC’s market-liquidity research also considers price impact and order-book depth. Trading volume alone is not a complete measure. Conditions can deteriorate during market stress, and liquidity can vary between instruments, currencies and trading hours.
High liquidity does not guarantee a stable price or a superior investment return. It describes the trading process, rather than protection against changes in the asset’s underlying value.
Payment timing can create a cash shortage
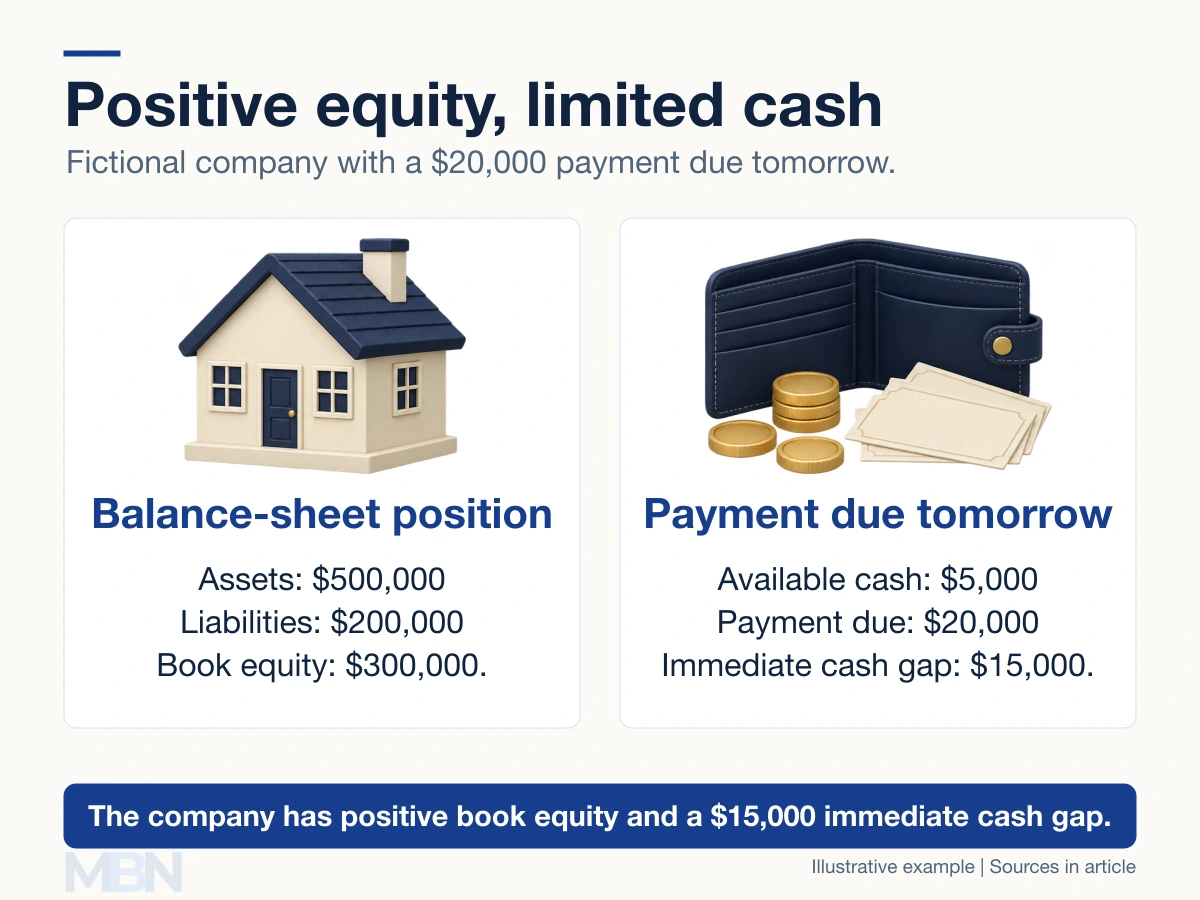
Suppose a fictional company records $500,000 of assets and $200,000 of liabilities, leaving $300,000 of book equity. It has only $5,000 immediately available, while a $20,000 payment falls due tomorrow.
It faces a $15,000 immediate cash gap unless it obtains funds in time. Buildings, equipment or customer invoices expected to be paid later cannot automatically settle tomorrow’s obligation.
Liquidity and capital answer different questions
The Federal Reserve distinguishes liquidity available for near-term payments from capital available to absorb losses. Strong book equity is not the same as readily available payment funds.
Solvency concerns the ability to meet obligations overall, with legal tests varying by jurisdiction. Positive book equity alone does not establish that every solvency test is met or guarantee access to borrowing.
What do accounting ratios show?
CFA Institute lists current, quick and cash ratios with different asset definitions. The current ratio uses current assets; the usual quick ratio includes cash, short-term investments and receivables while excluding inventory and prepayments.
Our cash-ratio explainer shows a narrower liquidity measure. Such ratios are snapshots. They need information about restrictions, collection dates, payment deadlines and future cash flows.
Can liquid bank assets earn interest?
Yes. The Federal Reserve pays interest on reserve balances held by or for eligible institutions. Liquid securities can also earn income. The idea that banks must minimize every liquid asset because none earns interest is therefore misleading.
Physical cash has no interest payment of its own, and inflation can reduce its purchasing power. Liquidity, income and purchasing-power risk are separate characteristics.
Last checked and updated on November 3, 2026 by the MBN editorial team.