
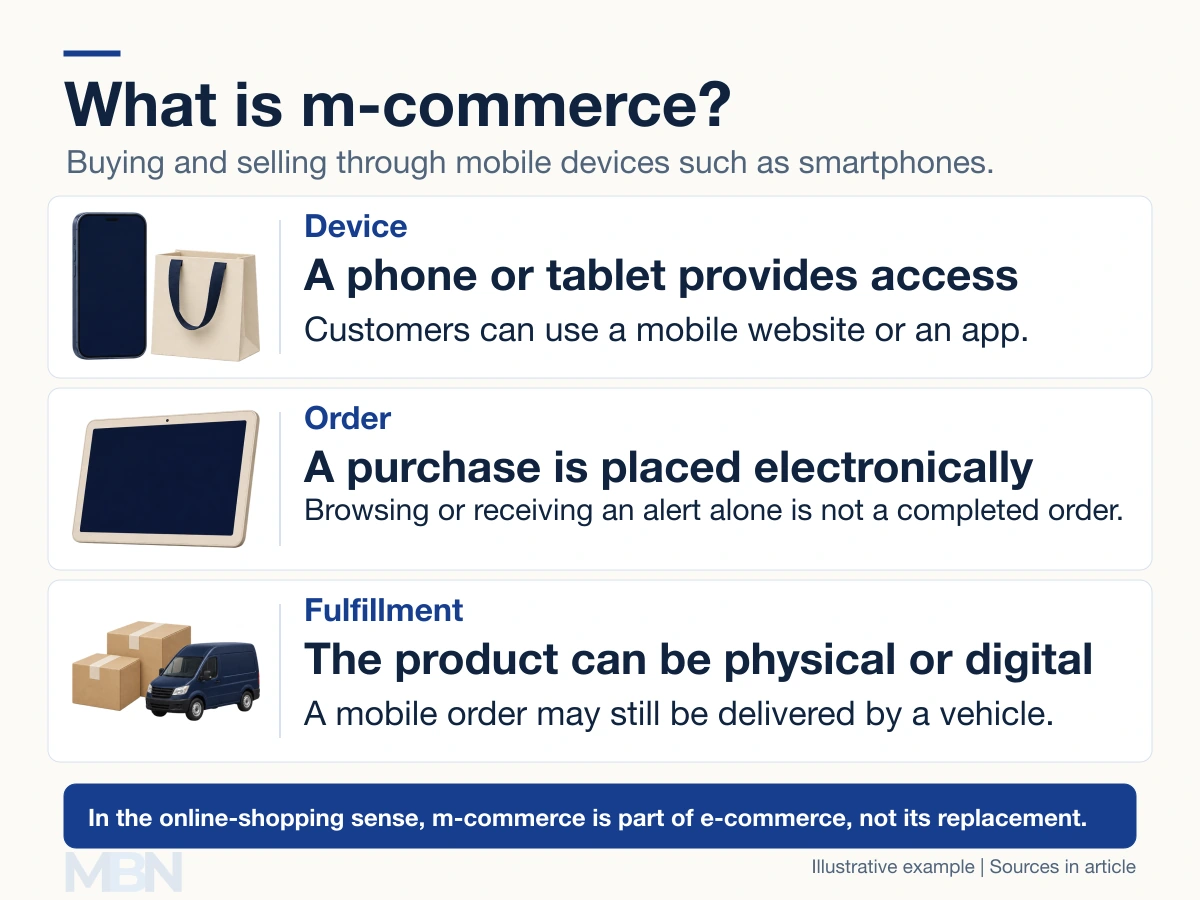
M-commerce means mobile commerce: buying and selling goods or services using a mobile device, usually a smartphone or tablet. In its online-shopping sense, it is the mobile part of e-commerce.
Customers can place orders through an app or a mobile website. They do not have to be moving: someone buying from a phone at home is still using a mobile device.
How does it fit within e-commerce?
E-commerce is broader than shopping from a desktop computer. The Office for National Statistics describes orders over the internet or other computer networks, with payment and delivery taking place online or offline.
The OECD’s 2025 framework also distinguishes the ordering method from payment and delivery. Its treatment of web-based commerce includes apps and access through devices such as phones, tablets and computers.
M-commerce describes the mobile-device channel within that broader activity. It does not mean that desktop users must visit a particular physical place to shop, or that mobile commerce has replaced e-commerce.
Examples of mobile purchases
A shopper may order shoes through a retailer’s phone app. Another customer might buy a train ticket through a mobile website, or purchase digital content inside an app.
The shoes require physical fulfillment, while a ticket or digital product can be delivered electronically. The type of device does not determine the type of product or how it reaches the buyer.
Browsing a catalog, receiving a discount notification or viewing a free news alert can support a sale. These activities are not, by themselves, completed purchases.
Mobile payments and mobile banking
Broader business discussions sometimes group mobile shopping with related payments, ticketing and financial services. These activities remain distinguishable. Checking a bank balance, transferring money and buying a product are different actions.
The Financial Consumer Agency of Canada describes mobile wallets as apps that store payment information. They can support contactless payments, online shopping and in-app purchases.
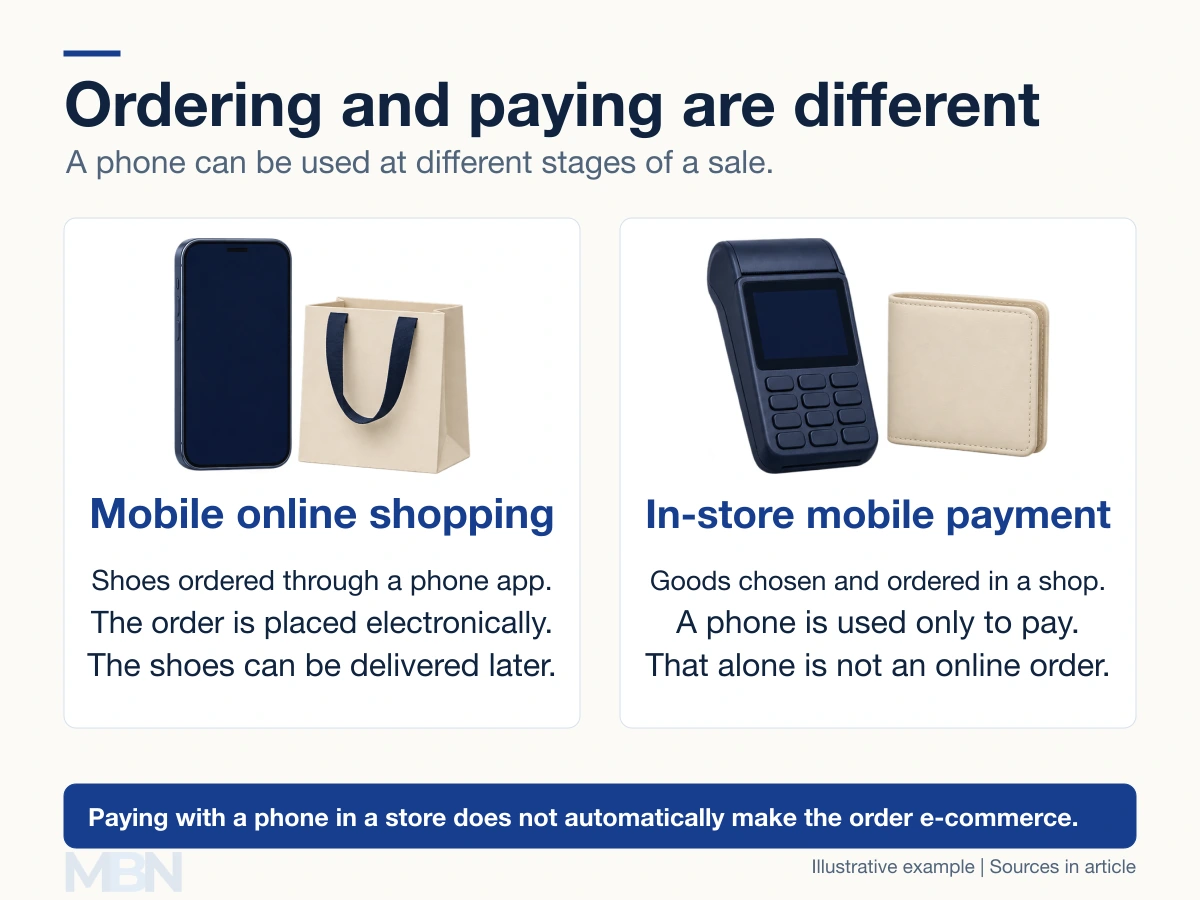
Suppose a customer selects and orders a sandwich at a shop counter, then taps a phone to pay. That is a mobile payment. It does not automatically become an e-commerce order under the OECD’s ordering-based definition.
If the sandwich is ordered through the shop’s app before collection, the ordering channel is different. Paying online, paying at collection and collecting the item in person are separate features of that transaction.
What changes for the customer and seller?
A smaller screen changes how products, forms and checkout steps are presented. Apps may use stored account details or device capabilities, while a mobile website can allow ordering without installing a dedicated shopping app.
Payment authentication and security features do not make every transaction risk-free. Canada’s consumer agency notes that a lost or stolen device can create fraud risks, and that wallet arrangements can store payment information in different ways.
Sales statistics also depend on their scope. A measure of mobile retail orders is not automatically comparable with one including banking transfers or every contactless payment. Country, period, transaction type and device definitions all matter.
Last checked and updated on November 3, 2026 by the MBN editorial team.