
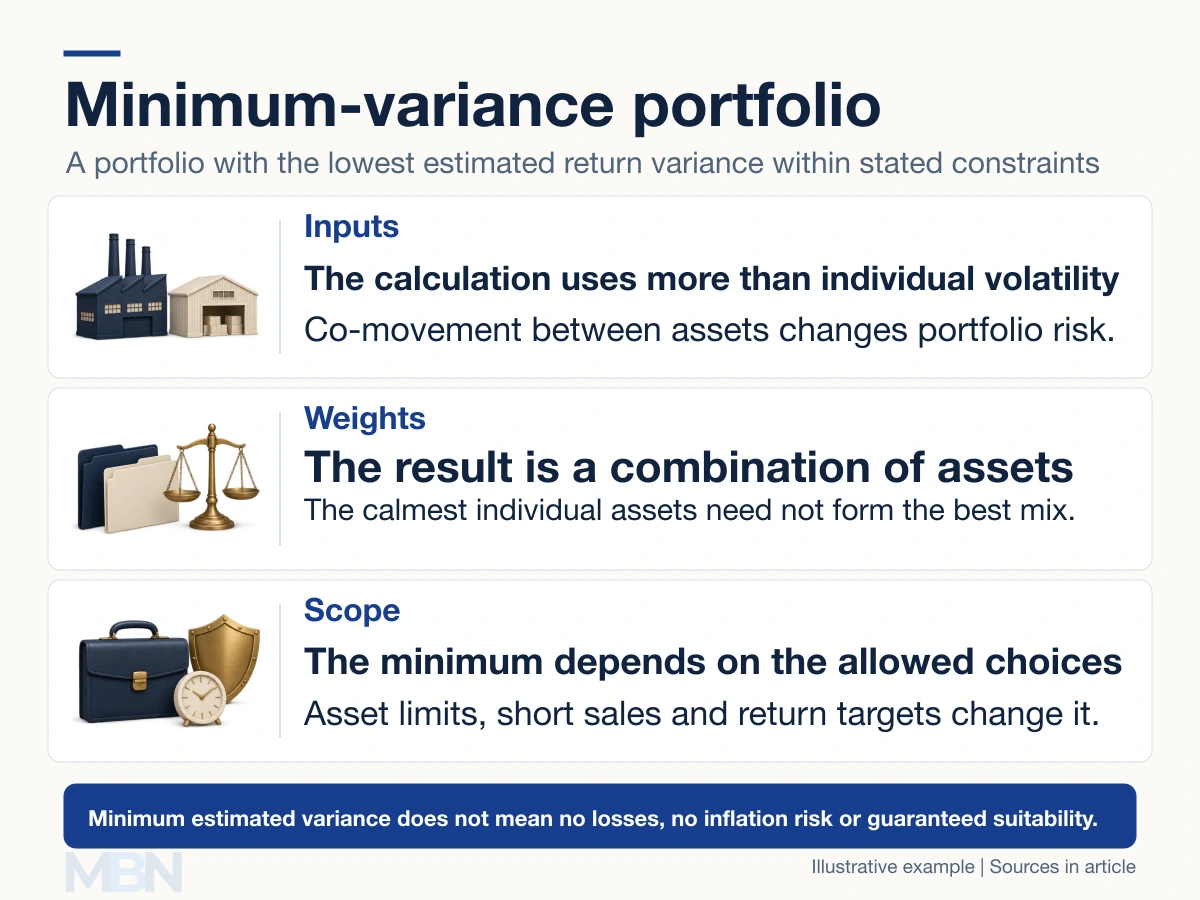
A minimum-variance portfolio is a combination of investments designed to have the lowest estimated variance of returns within a stated set of choices and constraints. It is a property of the whole portfolio, not simply a collection of the least volatile securities.
Variance measures how widely returns vary around their average. Its square root, standard deviation, expresses volatility in the same units as returns. Both describe variation, including above-average outcomes, rather than only the chance of losing money.
Global and target-return minimums
The global minimum-variance portfolio has the lowest estimated variance among all permitted portfolios, without a separate expected-return target. A minimum-variance portfolio for a specified return instead minimizes variance subject to reaching that target.
CFA Institute distinguishes minimum-variance and efficient frontiers. In the standard mean-variance setting, the global minimum is the leftmost point on a chart of return against standard deviation. The efficient portion extends upward from it.
It is therefore misleading to describe the global minimum as an alternative to every efficient portfolio. It is itself an efficient endpoint under the usual assumptions. Portfolios on the lower branch can offer less expected return than another feasible mix with the same risk.
Why co-movement matters
Portfolio variance depends on the assets’ weights, individual variances and covariances. Covariance measures how returns move together; correlation standardizes that relationship between −1 and +1.
With two assets, variance = wA²σA² + wB²σB² + 2wAwBρσAσB. The weights are wA and wB, the individual standard deviations are σA and σB, and ρ is their correlation. OpenStax explains multi-asset risk and return calculations.
For positive weights, correlation below +1 can reduce volatility below the weighted average of individual volatilities. That does not guarantee a result below the volatility of each asset separately.
A two-asset example
Assume Asset A has annual volatility of 10%, Asset B 20%, and their correlation is zero. Only these two assets are available, with no borrowing or short selling. The minimum occurs at 80% A and 20% B.
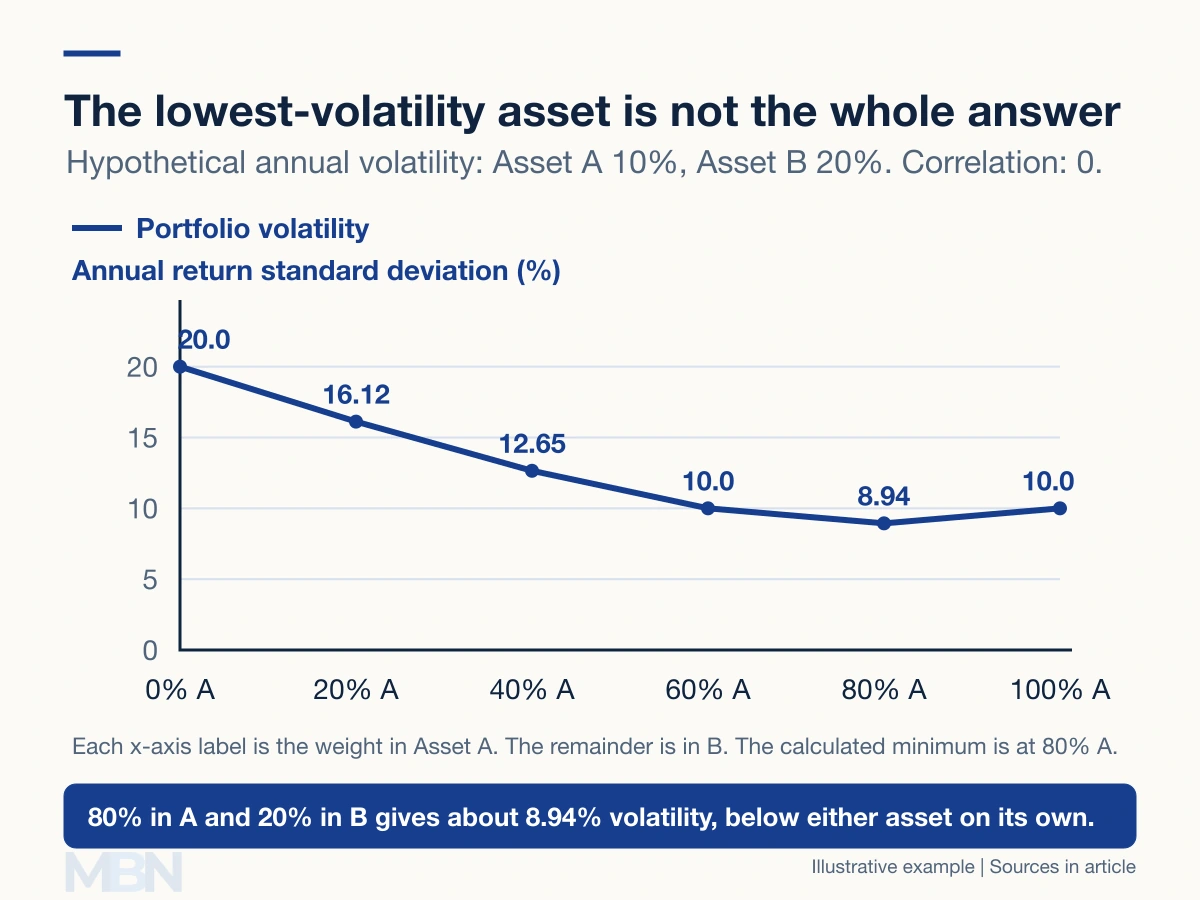
Using decimals, variance is 0.8² × 0.10² + 0.2² × 0.20² = 0.008. The square root is about 0.0894, or 8.94%. Thus, adding some of the individually more volatile asset reduces total volatility below A’s 10%.
If expected returns were 5% for A and 9% for B, this mix’s expected return would be 0.8 × 5% + 0.2 × 9% = 5.8%. That estimate is not needed to find this unconstrained-return minimum, and it is not guaranteed.
Constraints change the answer
A maximum holding size, a required sector balance, an expected-return target or permission to sell short changes the feasible portfolios. A mathematically unconstrained solution can contain large offsetting positions that a practical portfolio cannot use.
Commercial minimum-volatility products also use specified universes, risk models and construction rules. MSCI publishes a methodology for its minimum-volatility indexes. Their label does not mean they are the lowest-risk investment among every asset available.
What the model cannot guarantee
Estimated volatilities and correlations can change. Concentration, illiquidity, transaction costs and unusual losses can matter even when the variance estimate is low. Capital preservation, retirement income and inflation protection are separate objectives.
The approach belongs to mean-variance portfolio theory, associated with Harry Markowitz’s 1952 paper Portfolio Selection. It provides a framework for comparing combinations under assumptions. It does not make one portfolio automatically suitable for everyone approaching a particular age.
Last checked and updated on November 11, 2026 by the MBN editorial team.