
Modern portfolio theory, or MPT, compares portfolios using expected return and the variability of returns. It seeks the highest expected return for a given level of risk, or the lowest risk for a specified expected return, within a defined investment set.
The 1990 economics-prize announcement identifies Harry Markowitz’s 1952 portfolio-selection paper and 1959 book as foundations of the approach. It distinguishes his portfolio-choice work from William Sharpe’s asset-pricing work and Merton Miller’s corporate-finance contributions.
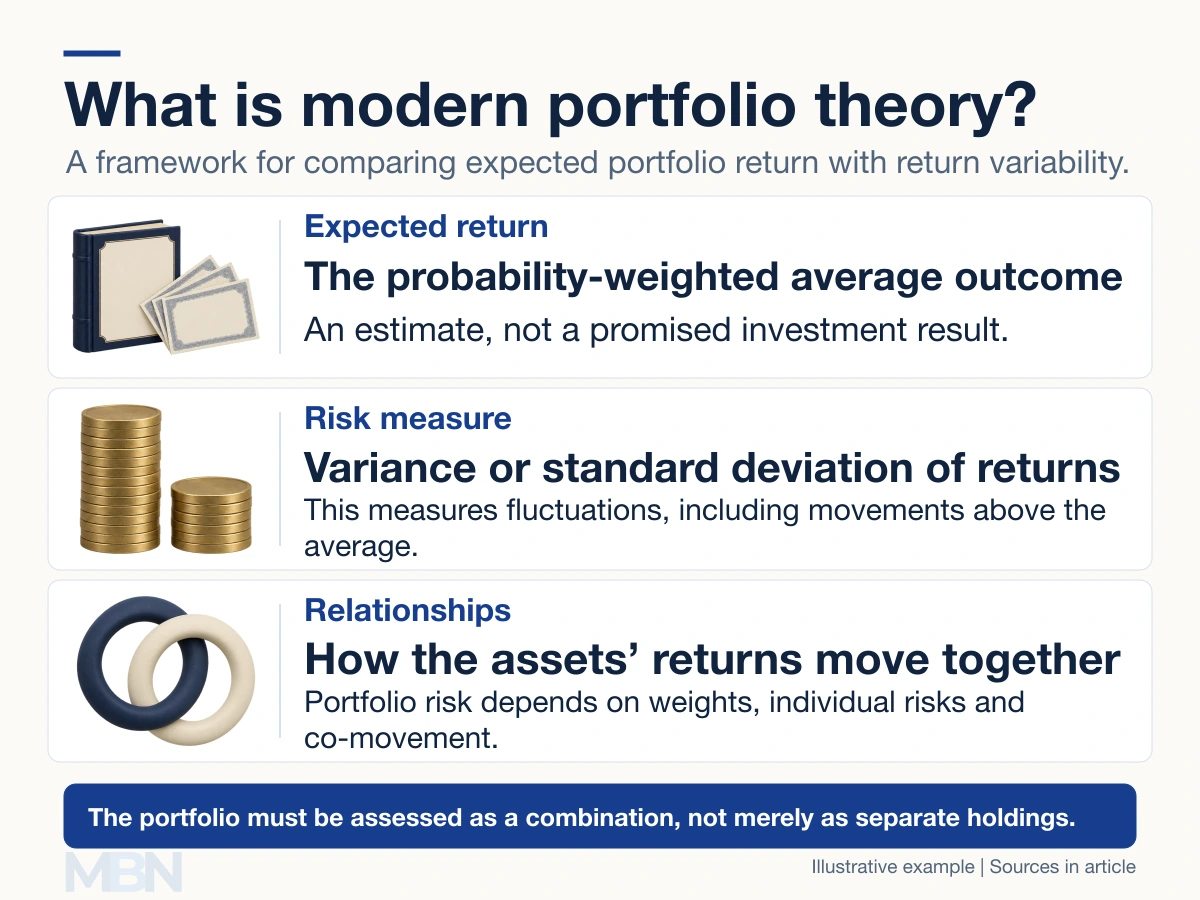
The inputs describe a model
Expected return is a probability-weighted average of possible outcomes. It is not a guarantee. In the basic mean-variance framework, variance or its square root, standard deviation, represents risk.
The CFA Institute’s portfolio-mathematics overview explains these return, variance and covariance measures. Covariance and correlation describe how assets’ returns move together. Portfolio weights determine how much of each exposure is held.
Standard deviation counts deviations both above and below the average. The CFA Institute’s risk explanation describes that two-sided variability. It is not a complete measure of default, illiquidity or the chance of failing to meet a particular financial goal.
Diversification does not require opposite movements
Diversification can reduce return variability even when their correlation is positive, provided it is below perfect positive correlation and the weights and risks support that result. Shares and bonds do not have to move in opposite directions.
The CFA Institute describes portfolio risk as a function of asset weights, individual standard deviations and correlations. Simply adding more holdings does not establish an efficient portfolio.
The efficient frontier
A feasible portfolio is one permitted by the model’s investment choices and constraints. An efficient portfolio has no feasible alternative offering higher expected return without more risk, or lower risk without less expected return.
The efficient frontier collects those combinations. The global minimum-variance portfolio has the lowest variance among the feasible portfolios. The efficient part of the risky-asset boundary extends toward higher expected returns from that point, rather than being defined by a minimum number of stocks.
A fictional two-asset illustration
Assume A has an expected annual return of 5% and B of 9%. Both have annual return standard deviations of 20%, and their correlation is zero. Only long positions adding to 100% are allowed, with no borrowing.
A 50% allocation to each has expected return of 7%. Its variance is 0.5² × 0.20² + 0.5² × 0.20² = 0.02, giving standard deviation of about 14.14%. It is the minimum-variance mix under these particular assumptions.
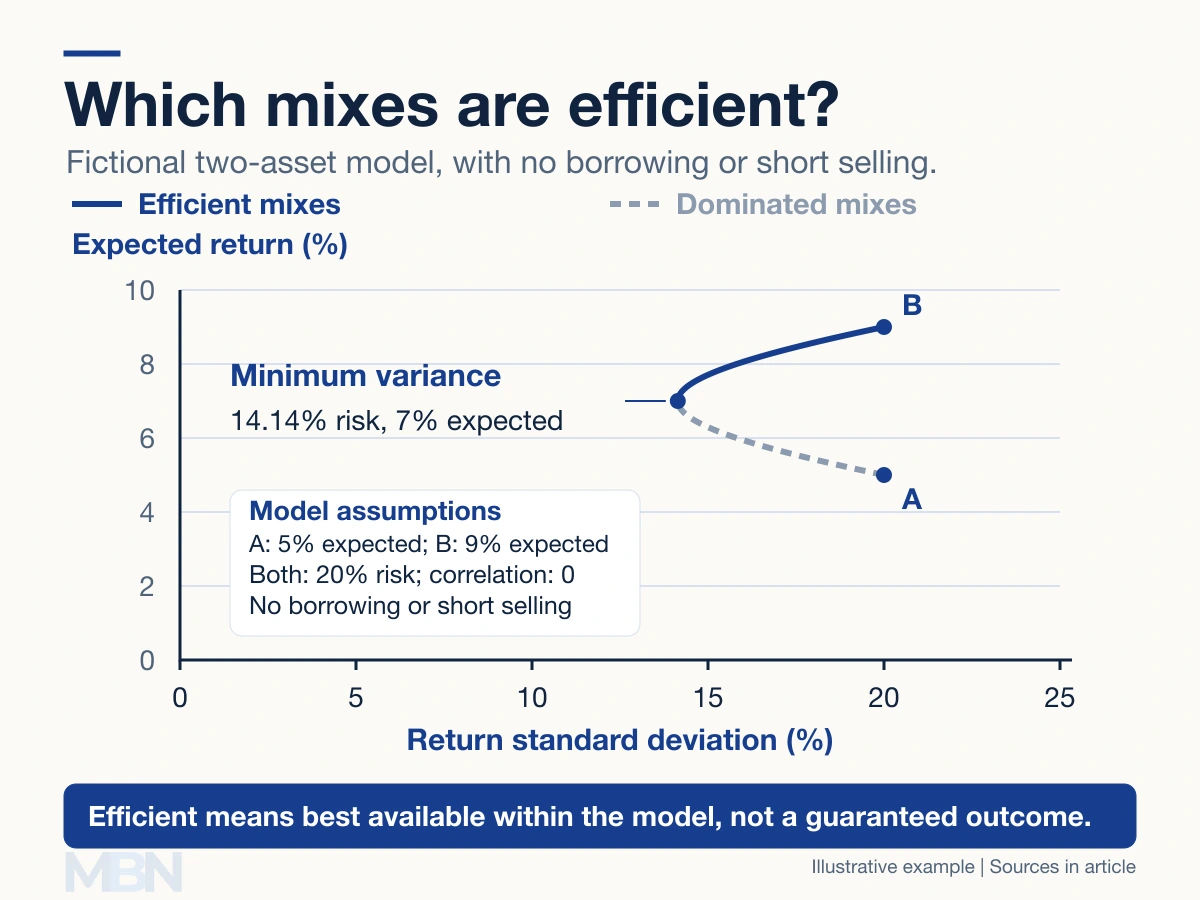
The upper blue branch offers higher expected return for a given risk than the corresponding lower branch. These are calculated possibilities inside an invented model, not forecasts or observed fund performance.
The limits of an optimized result
Expected returns, risks and correlations must be estimated and can change. Different constraints or inputs produce different portfolios. Investors can also have different risk preferences; the same model does not prescribe one allocation for everyone.
The CFA Institute distinguishes portfolio theory from the additional assumptions used in asset-pricing models. Optimization can organize a decision, but cannot promise the best realized return or eliminate market losses.
Last checked and updated on November 4, 2026 by the MBN editorial team.