
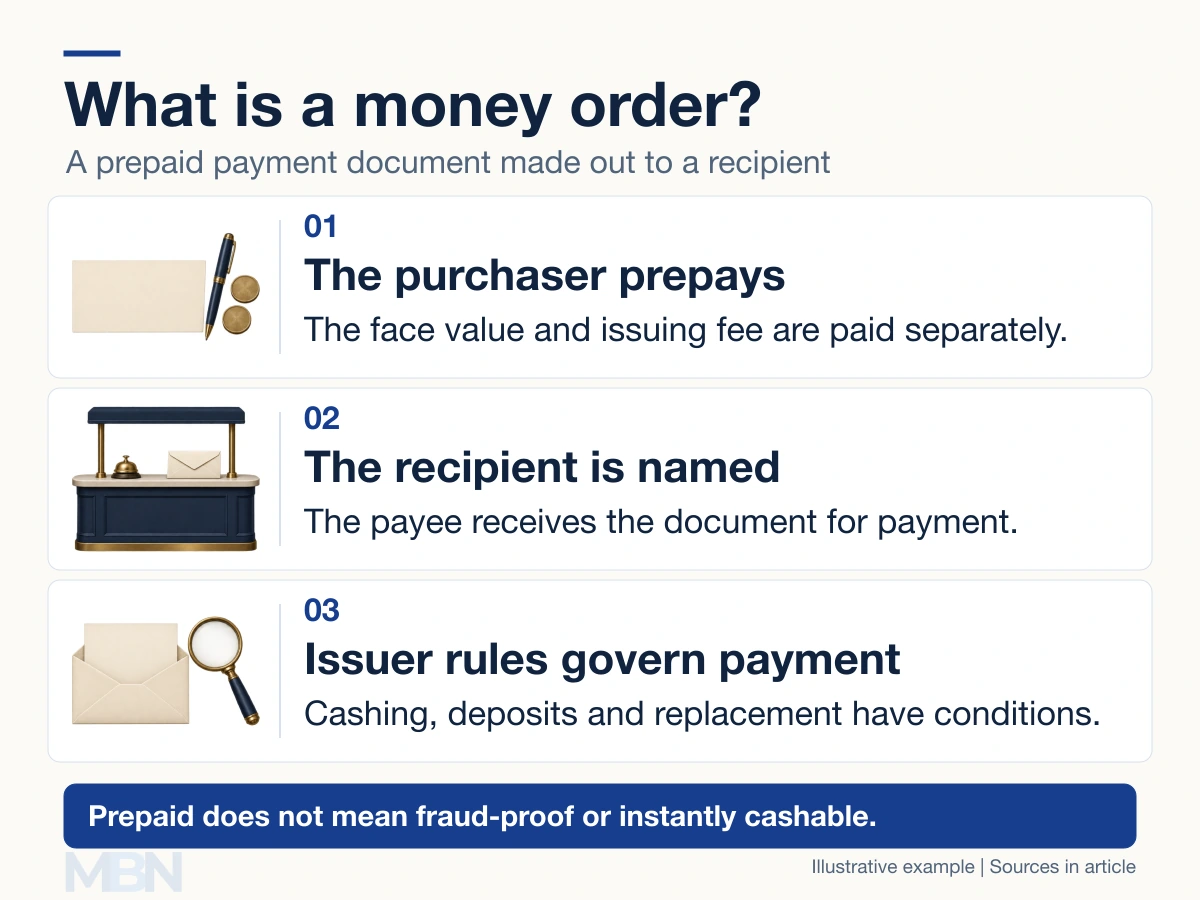
A money order is a prepaid payment document for a specified amount, generally made payable to a named recipient. The purchaser pays its face value plus any issuing fee before passing the document to the recipient.
Issuers can include postal operators, banks and payment businesses. A money order is not simply a personal cheque drawn against the purchaser’s current account. Its acceptance and redemption follow the issuer’s rules and applicable law.
How the value and fee work
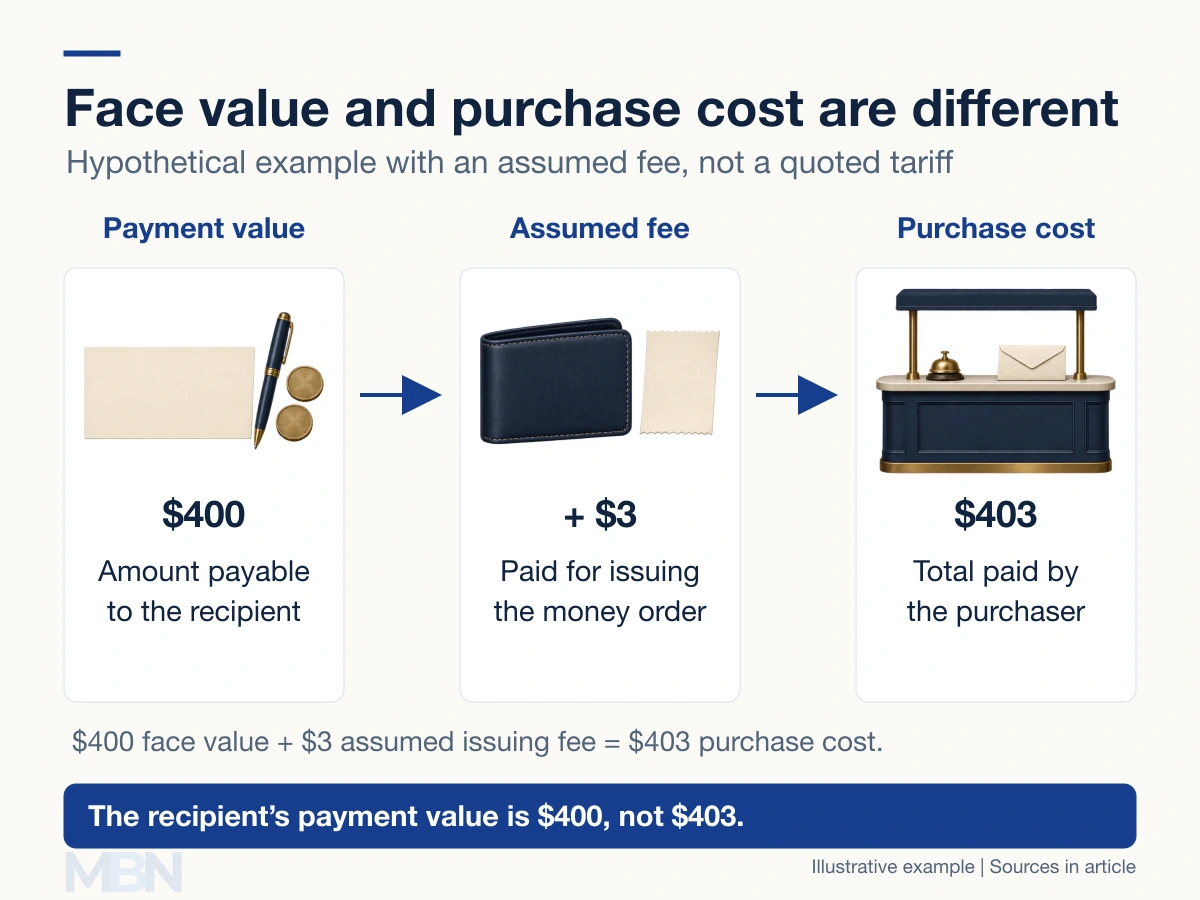
Imagine a person needs to pay a $400 bill, and the recipient accepts a money order. With an assumed $3 issuing fee, the purchaser would pay $403. The document’s payment value would remain $400. These figures illustrate the distinction, not a particular provider’s tariff.
A money order can help someone make a paper-based payment without sharing a personal cheque’s account details. That does not establish that every biller accepts it, or that every retailer will cash it.
US postal money orders
USPS permits up to $1,000 on a single domestic money order and states that its postal money orders never expire. It does not accept credit cards to purchase them. The purchaser should retain the receipt.
USPS also says postal money orders cannot be stopped through a stop-payment instruction. Lost or stolen orders have a separate inquiry and replacement process, with a fee and investigation time. Other issuers’ cancellation arrangements may differ.
Cashing is not an unconditional promise of immediate cash from any participating outlet. Identification, validity and local procedures matter. The USPS money-order FAQ notes that cashing at a Post Office depends on funds available there.
UK postal orders have different conditions
The UK Post Office offers postal orders from 50p to £250. A crossed order must be paid through a bank rather than cashed in a branch. Naming a payee does not, by itself, mean an order has been crossed.
Unlike US postal money orders, UK postal orders expire six months after issue. Payment afterwards is at Post Office Ltd’s discretion. Its purchasing fee is an administration charge, not insurance against loss.
International services are not universal
USPS no longer sells international money orders and stopped cashing international money orders on 1 October 2025. An older description of buying and cashing them through that service is therefore outdated.
Providers’ electronic remittances are separate products. A promise of near-instant electronic delivery should not be applied to a paper order travelling by post. Availability, currencies, delivery times and redemption rules need to be checked for the particular service.
Prepayment does not eliminate fraud
A genuine prepaid document avoids dependence on the purchaser’s personal cheque balance. It can still be forged, altered or stolen. The Federal Trade Commission explains that fraudulent instruments may look convincing and that an available bank balance does not establish authenticity.
In an overpayment scam, a seller receives an apparently valid £500 order for a £300 item and is asked to return £200. If the document is counterfeit, the seller can lose the returned money and remain responsible to the bank. Prepayment claims do not protect that transaction.
Last checked and updated on November 6, 2026 by the MBN editorial team.