
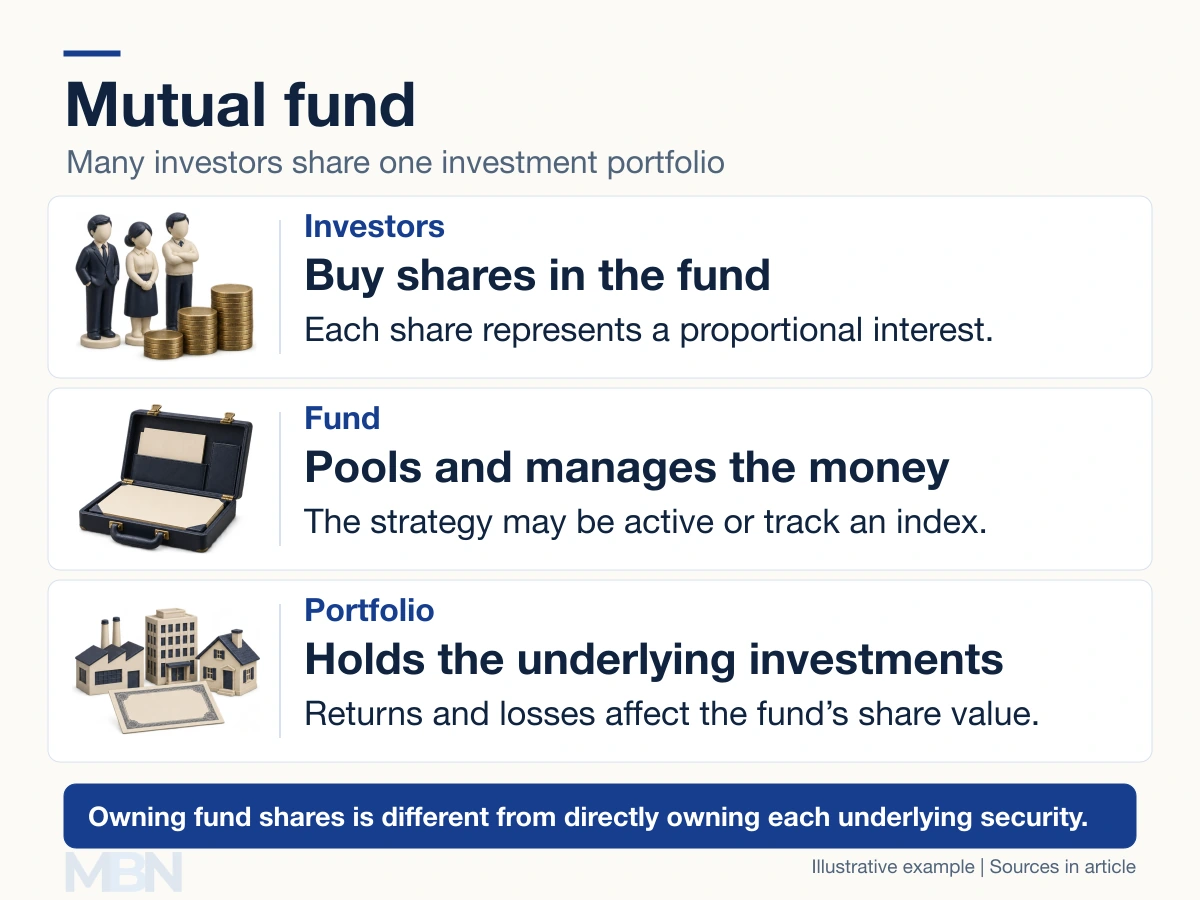
A mutual fund pools money from investors to buy a portfolio of securities, such as stocks, bonds or short-term debt. Investors buy shares in the fund and participate proportionally in its investment results.
The US Securities and Exchange Commission (SEC) describes each share as part ownership of the fund’s portfolio and the income it generates. Investors hold fund shares, rather than directly owning or choosing each underlying security. They do not thereby own shares in the separate business that manages the fund.
How the pooled portfolio works
A fund follows an investment objective set out in its prospectus. An actively managed fund uses investment decisions made by its managers. An index fund seeks to track a specified market index.
Returns can come from income distributions, capital gains distributions and changes in share value. Payments can be taken as cash or reinvested where the fund permits. Neither income nor growth is guaranteed.
How mutual fund shares are priced
For a conventional US open-end mutual fund, purchases and redemptions use the next calculated net asset value (NAV), with applicable charges added or deducted. NAV is generally calculated at least once each business day, rather than continuously as an exchange-traded share price.
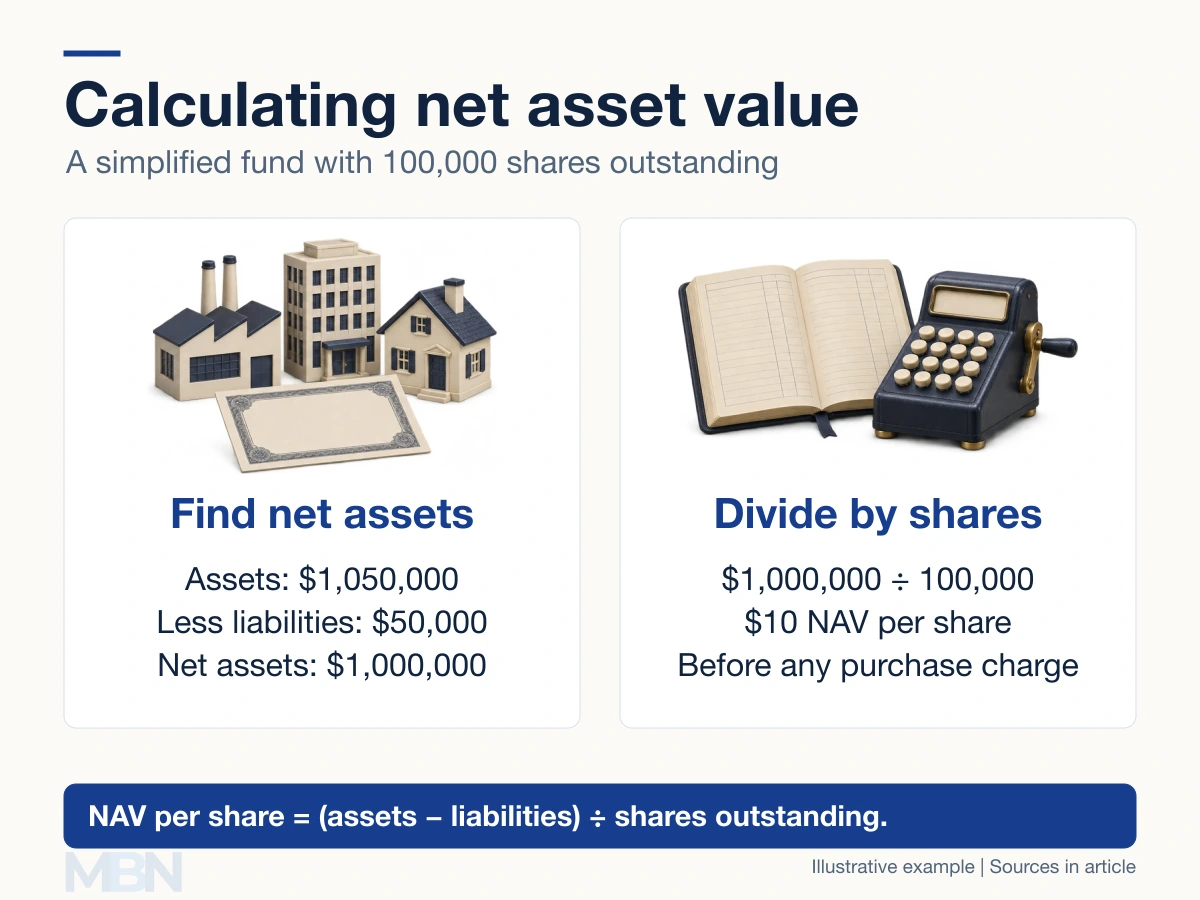
NAV per share equals the value of the fund’s assets minus its liabilities, divided by shares outstanding. Assets include investments and cash; liabilities include amounts the fund owes.
For example, $1,050,000 in assets minus $50,000 in liabilities leaves $1,000,000 in net assets. Dividing by 100,000 shares gives a NAV of $10 per share.
At that NAV, a $500 purchase buys 50 shares if there are no purchase charges. The final price depends on the next valuation, not necessarily the NAV displayed when the order is placed.
Fund types and risks
Stock funds invest mainly in shares; bond funds mainly in debt. Money market funds hold short-term instruments. Target-date funds change their investment mix over time toward a stated retirement date, but do not guarantee a retirement income or prevent losses.
A broad portfolio can reduce exposure to one company’s failure. A sector or concentrated fund may provide much less diversification. Diversification does not eliminate market losses, and a bond fund is not guaranteed to outperform a money market fund.
Fees and legal structures matter
A sales load is a selling charge. A no-load fund has no sales load but can still charge operating expenses or other fees. The expense ratio describes annual fund operating expenses relative to average net assets. Different share classes can have different costs.
Names and structures vary by country. UK pooled funds include unit trusts and investment companies with variable capital; Irish funds also have several legal forms. “Mutual fund” is therefore not simply another name for every unit trust.
Unlike ordinary mutual fund shares, exchange-traded fund shares and many closed-end fund shares trade at market prices that can differ from NAV. Mutual funds are investments, not FDIC-insured deposits, even when sold through a bank.
Video introduction
This brief Marketing Business Network introduction explains pooling and fund ownership. The sections above add the pricing, cost and risk distinctions.
Last checked and updated on November 10, 2026 by the MBN editorial team.