
A mutual savings bank is a deposit-taking bank organized in mutual form, without ordinary outside stockholders owning the bank directly. Depositors have membership or mutual ownership interests under the institution’s charter and applicable law.
This article focuses on US institutions. A savings bank may be mutual or stock-owned, so the words savings bank alone do not establish its ownership. A federal mutual savings association is a related charter form with its own legal framework.
What does depositor ownership mean?
A depositor’s rights are not equivalent to owning a transferable share in a listed bank. Membership can carry governance rights, but it does not provide an unrestricted right to withdraw a portion of the bank’s accumulated capital.
The Office of the Comptroller of the Currency (OCC) explains that a federal mutual’s charter and bylaws establish members’ rights. Some state savings banks instead use corporators and trustees in their governance; Massachusetts regulations recognize corporators as a distinct part of a mutual savings bank’s structure.
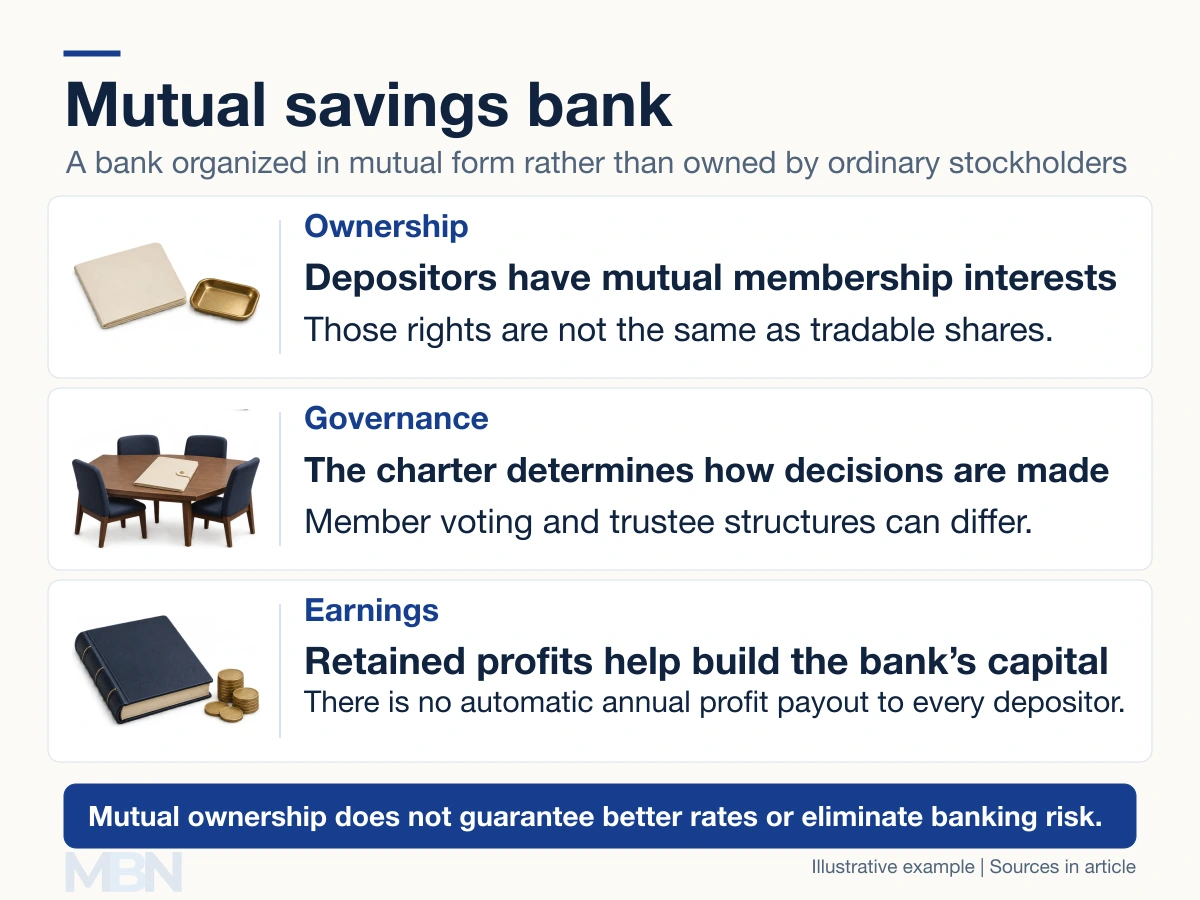
Deposits remain obligations the bank owes its customers. They are different from equity, the bank’s residual financial cushion after liabilities. A $1,000 savings deposit is not a $1,000 purchase of common stock.
What happens to the profits?
Mutual banks need earnings to pay expenses and strengthen their finances. They may use their structure to support customers and communities, but there is no automatic rule requiring all remaining profits to be divided among depositors.
Retained earnings are profits kept in the institution. In a 2025 discussion of mutual banks, Federal Reserve Governor Michelle Bowman explained that their ownership structure typically makes them heavily reliant on retained earnings to raise capital.
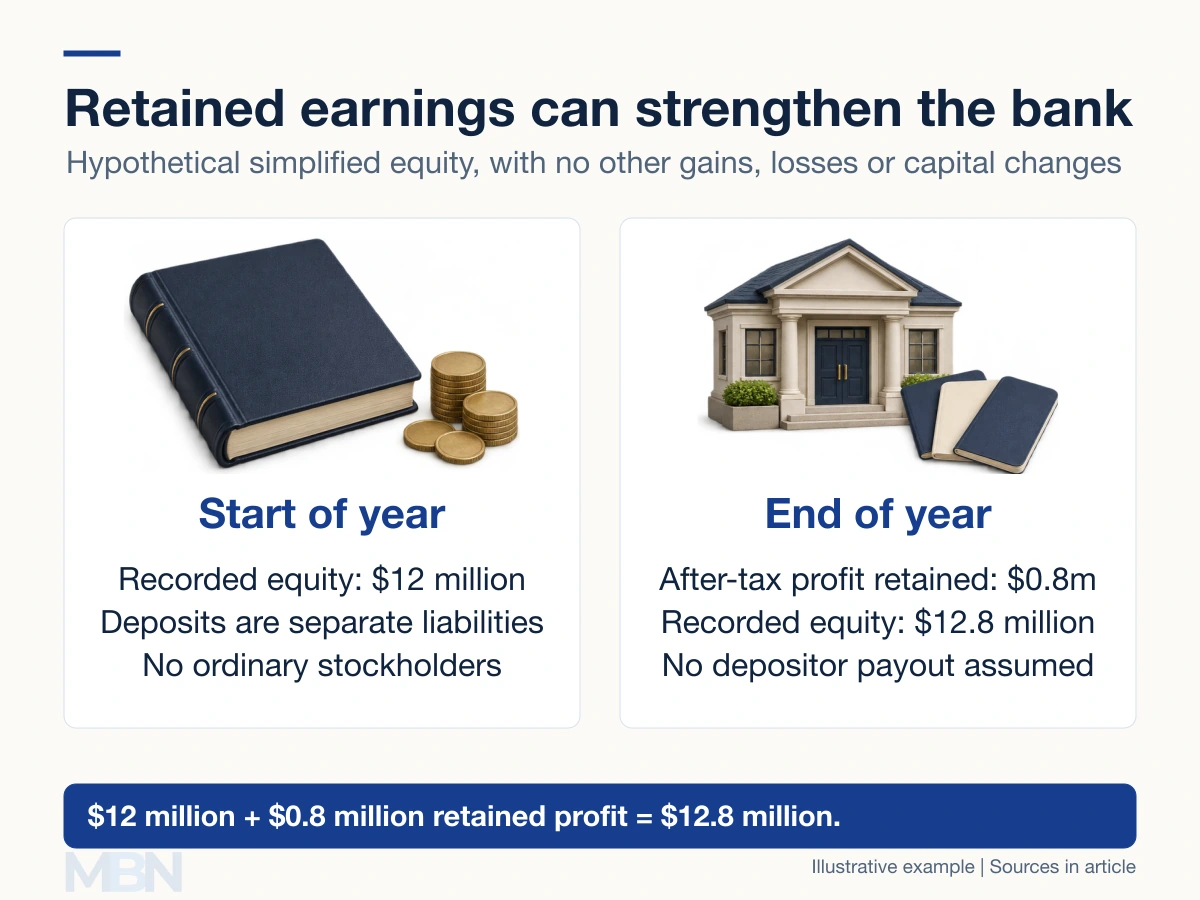
For example, imagine a mutual bank starts with $12 million of recorded equity and retains $800,000 of after-tax profit. With no other equity changes, it ends with $12.8 million. Depositors’ individual balances do not automatically increase by a share of that profit.
How do mutual banks operate?
They accept deposits and provide banking services such as mortgages and other loans, subject to their charter and permissions. Their income can include interest on lending and fees; their costs include deposit interest, staff, systems and credit losses.
The absence of ordinary stockholders changes ownership incentives, but does not make credit losses, interest-rate movements or liquidity problems disappear. Customer rates, fees, service quality and financial condition differ between institutions.
Are they the same as credit unions?
No. Mutual banks and credit unions can both have member-based structures, but they have different charters and legal rules. The National Credit Union Administration describes federal credit unions as member-owned, not-for-profit cooperatives with defined membership eligibility and one vote per member.
It is unsafe to apply those credit-union rules automatically to every mutual bank. Deposit insurance also follows the institution and account rules. US bank deposits at an FDIC-insured institution are covered under FDIC limits and ownership categories; credit-union share insurance uses a separate framework.
Where did the savings-bank movement begin?
Mutual savings banks developed to make saving accessible to ordinary households. The Boston Fed traces an influential early institution to Henry Duncan’s Savings and Friendly Society in Scotland in 1810, with early American institutions emerging in Philadelphia and Boston in the following decade.
The historical mission does not establish a bank’s present size, products or ownership. Old counts of institutions quickly become outdated through mergers and conversions.
Can a mutual bank change its structure?
Yes, subject to the relevant rules and approvals. Some convert to stock ownership. A mutual holding company structure can also retain a mutual parent above a stock banking subsidiary. Such arrangements require a more precise description than assuming every mutual-related institution has no shares anywhere in its group.
Last checked and updated on November 10, 2026 by the MBN editorial team.