
Neoclassical economics is a broad approach to explaining how people and businesses make choices under constraints, and how those choices influence prices, production and the allocation of resources.
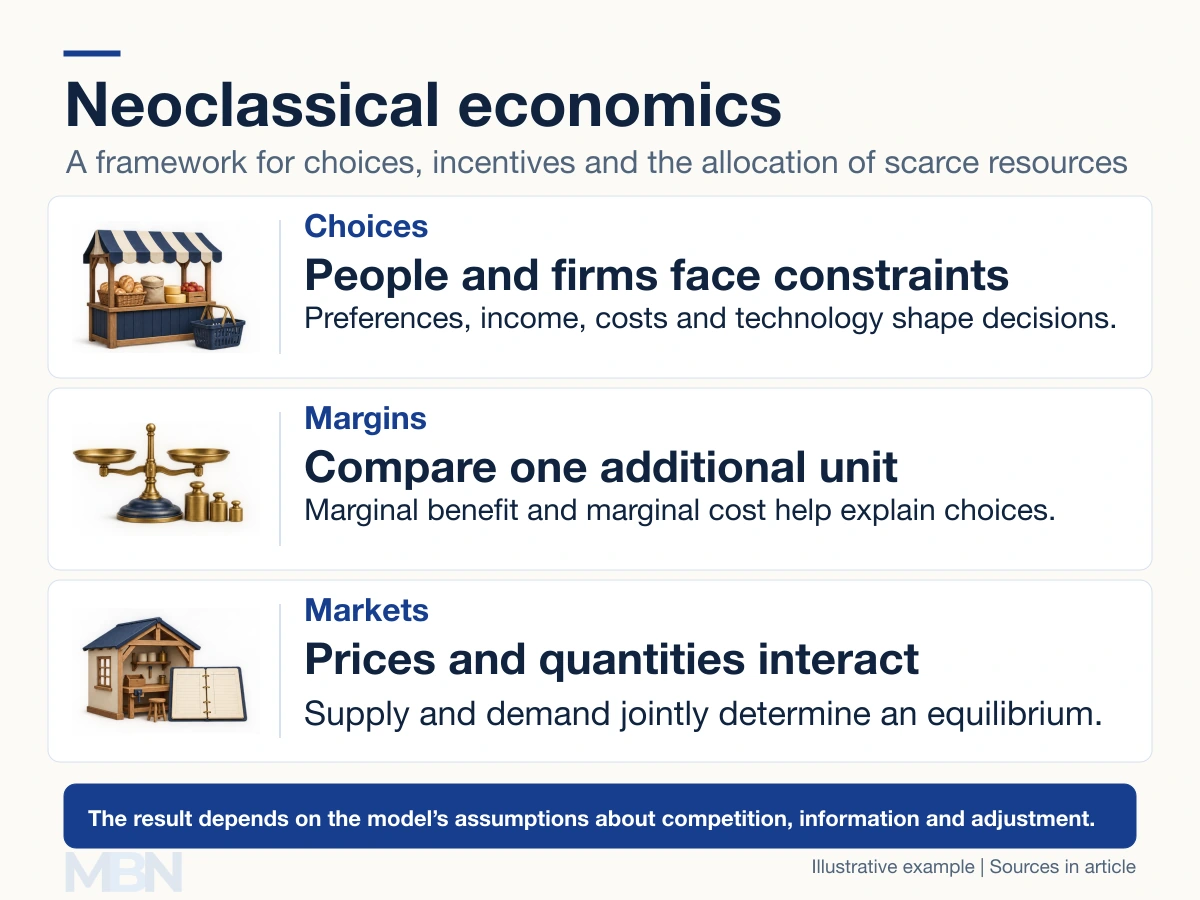
Its models commonly use preferences, incentives, marginal comparisons and equilibrium. Consumers are modeled as choosing among affordable options, while firms choose production or inputs subject to costs, technology and market conditions.
Choices at the margin
Utility means the satisfaction or value a person gets from an outcome. Maximizing utility within a budget does not mean buying the most goods or always choosing the cheapest product. Different preferences can produce different choices.
Marginal means the change associated with one additional unit. If another unit costs a business $8 to produce and adds $10 to revenue, it adds $2 to profit under those assumptions. If the next unit costs $11 and adds only $10, it reduces profit by $1.
Such comparisons underpin many models of consumer demand and firm behavior. They are conditional explanations, rather than proof that people calculate perfectly or that every manager always maximizes profit.
Both supply and demand matter
Buyers influence demand, but costs, technology and sellers’ decisions also influence supply. Alfred Marshall’s Principles of Economics brings production and demand together in the analysis of value. It does not make the consumer the sole driver of every market outcome.
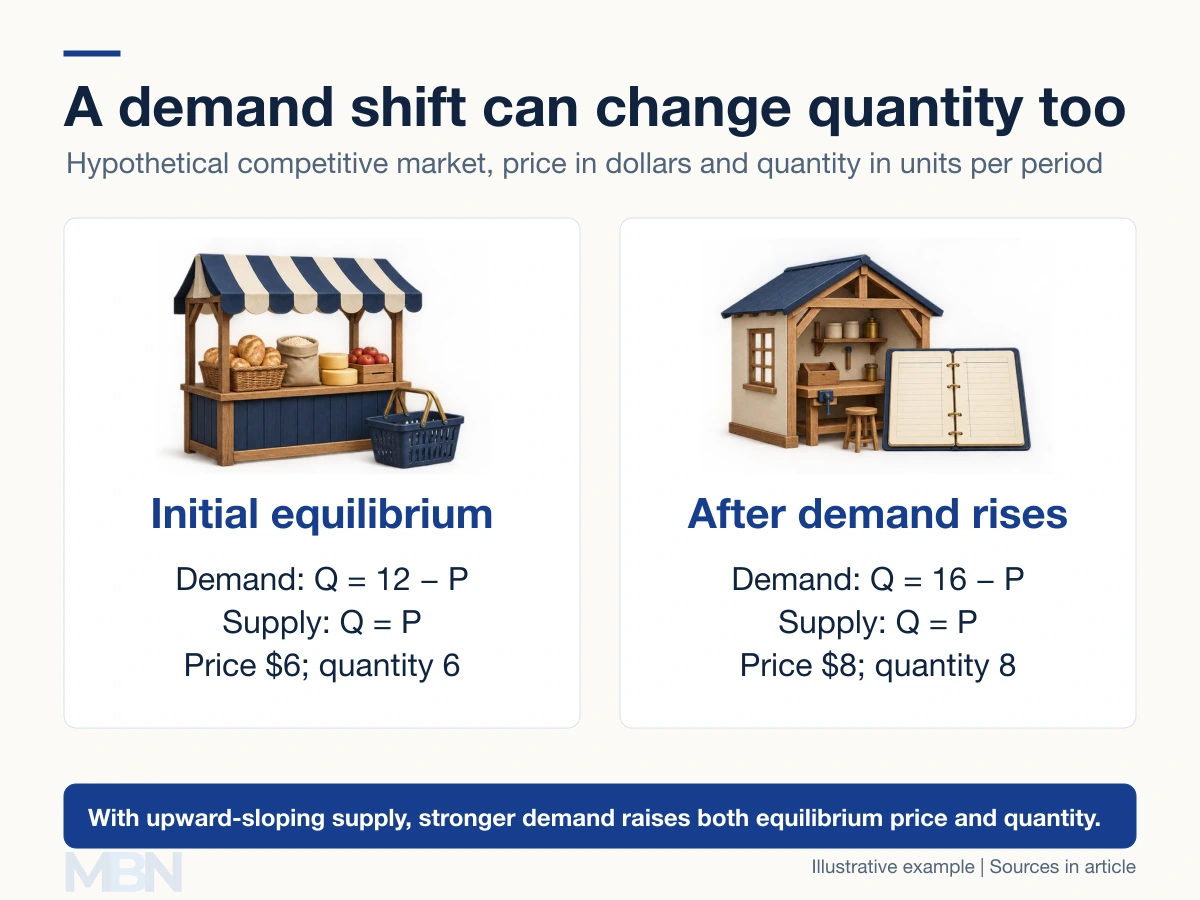
Consider a simple market where quantity demanded is 12 minus price and quantity supplied equals price. At a price of $6, both quantities are 6 units per period.
If demand increases to 16 minus price while supply is unchanged, equilibrium becomes $8 and 8 units. Both price and quantity change. The outcome would differ with a vertical supply curve, which fixes quantity in the period being modeled.
Equilibrium means the modeled choices are mutually consistent. It does not itself prove that adjustment is immediate, that the result is fair or that every real market reaches a unique stable outcome.
Where the approach came from
Nineteenth-century economists including William Stanley Jevons, Carl Menger and Léon Walras helped develop marginal analysis. Marshall’s work combined marginal reasoning with the study of costs and supply. These contributions were related but did not form one identical theory.
The shift placed more emphasis on choices and the value of additional units than earlier classical accounts associated with production, distribution and costs. Classical economics and neoclassical economics are therefore related historical categories, not interchangeable names.
Neoclassical and Keynesian analysis
In macroeconomics, some neoclassical models emphasize long-run productive capacity and flexible prices. Keynesian analysis emphasizes how weak total spending and slow price or wage adjustment can leave resources unused in the shorter run.
The IMF describes how Keynesian economics evolved and incorporated later critiques. Modern approaches can combine optimizing households and firms with market imperfections and sticky prices. It is misleading to reduce the distinction to quantities always fixed in one school and prices always fixed in the other.
Similarly, saving equals investment in the basic closed-economy national accounting identity after the fact. A theory about how interest rates, income or expectations bring planned saving and investment into line is a separate causal claim. Open economies also allow cross-border financing.
Assumptions, market failures and limits
Perfect information and perfect competition are assumptions in some benchmark models, not requirements of every model using neoclassical tools. Economists can analyze monopoly, pollution and unequal information with choice and equilibrium methods.
The 2001 economics prize explanation describes how asymmetric information can alter market outcomes, including credit rationing and unemployment. Asymmetric information means one side knows more than the other.
Market failures can provide a case for intervention, but the effects of a particular tax, regulation or public service still need analysis. Neoclassical reasoning does not establish that less regulation automatically raises wages, GDP or life expectancy.
Critics question assumptions about rational choice, distribution, institutions and adjustment. Useful evaluation asks which model is being used, which conditions it assumes and whether its predictions fit the evidence.
Last checked and updated on November 10, 2026 by the MBN editorial team.