
Net worth is total assets minus total liabilities at a specified date. It measures the balance between what a person or entity owns and what it owes. It is different from income, the cash available today and the price someone might pay for an entire business.
Assets can include cash, investments, property and vehicles. Liabilities include outstanding loans and other amounts owed. The SEC’s Investor.gov explanation calculates net worth by subtracting liabilities from assets.
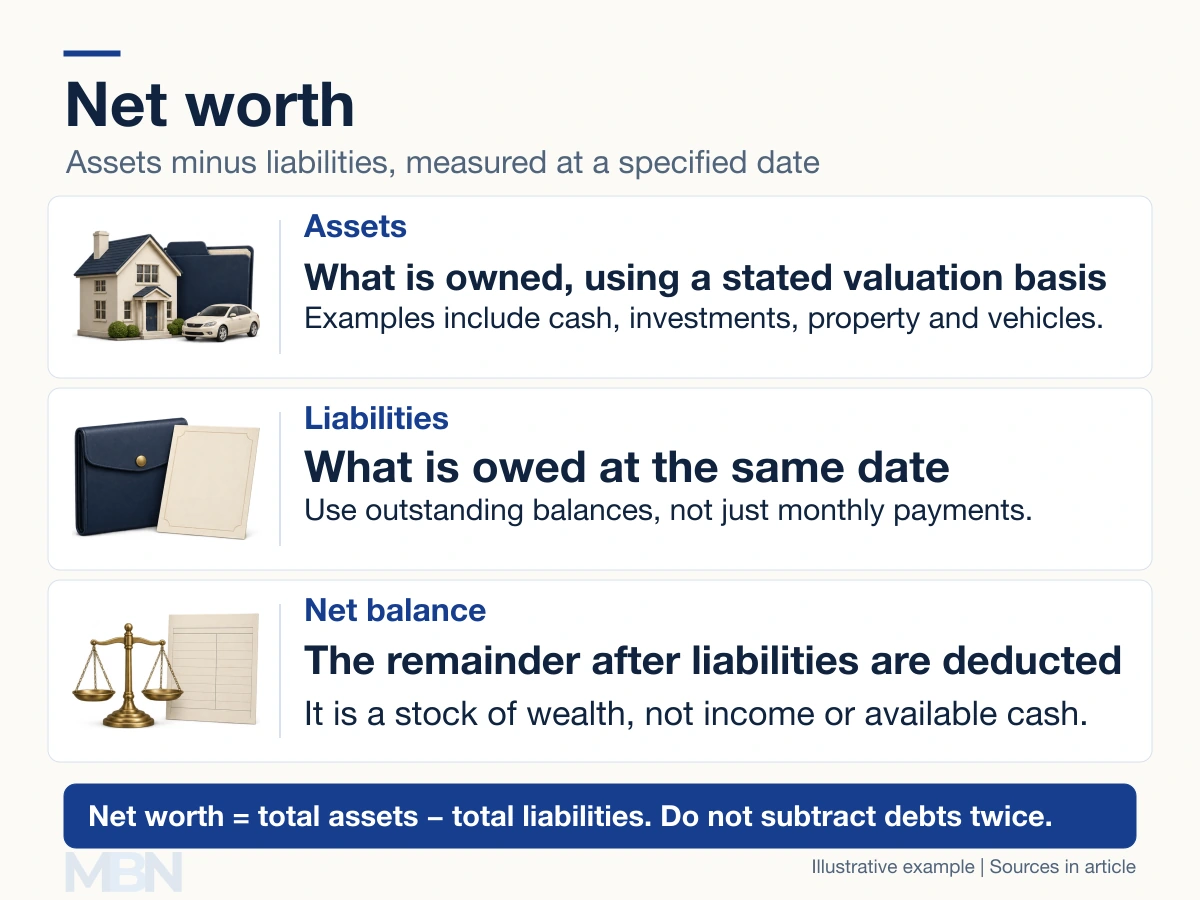
How to calculate net worth
Use values belonging to the same person or entity and the same date. A personal statement commonly uses reasonable current estimates for property and investments, together with current debt balances. Estimates should state their basis and material uncertainty.
Suppose someone owns a house valued at $300,000, investments worth $50,000, and vehicles and other property worth $15,000. Total assets are $365,000. Outstanding liabilities are a $50,000 mortgage and a $4,000 car loan, totalling $54,000.
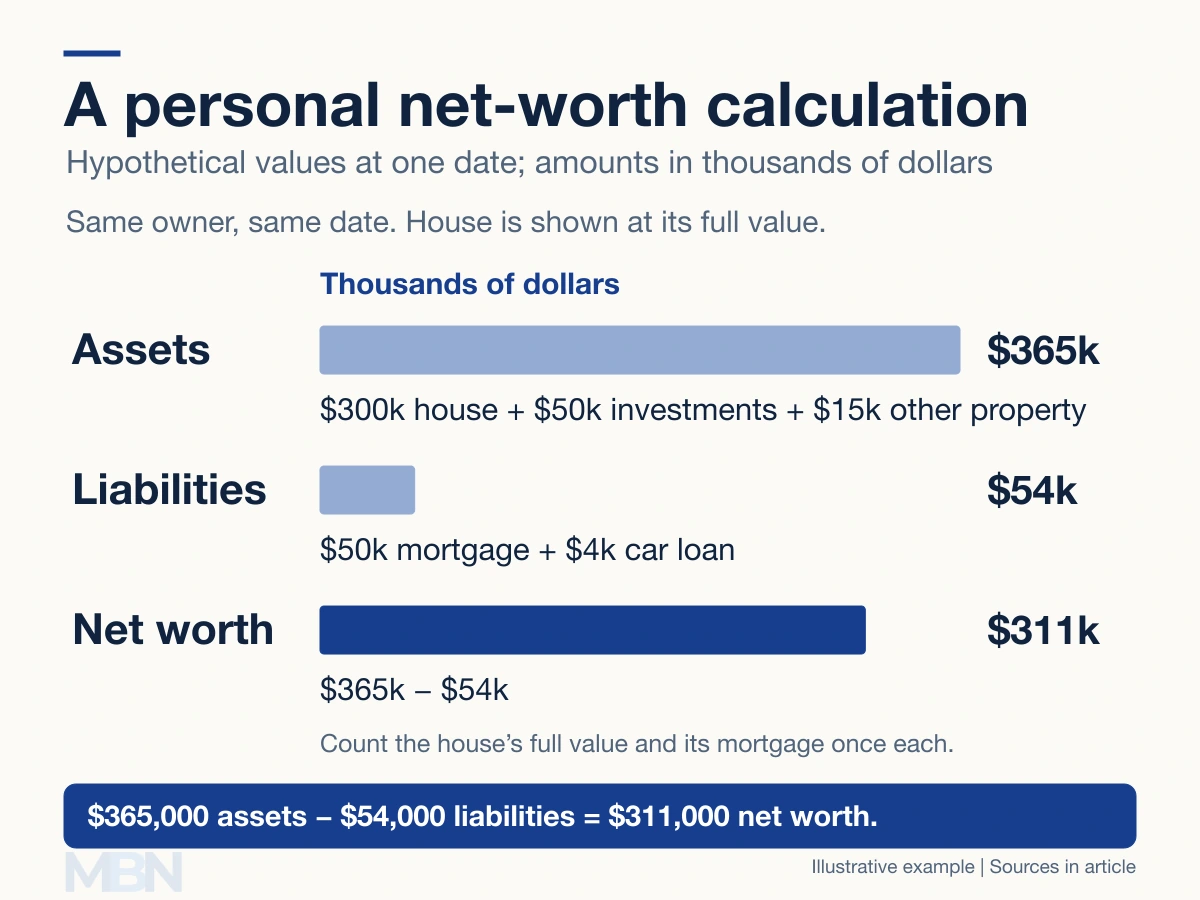
Net worth is $365,000 − $54,000 = $311,000. Calling the $365,000 figure net assets would be misleading here: it is total assets before liabilities are deducted.
Include the house at its full value and the mortgage as a liability, or present home equity, the value after that mortgage, consistently. Do not use the home-equity figure and subtract the same mortgage again. Jointly owned assets and shared debts also require a consistent ownership basis.
What changes net worth?
Saving income can increase assets and net worth. Asset-price changes can also alter the balance without cash changing hands. If the example’s house estimate falls by $30,000 and everything else is unchanged, net worth falls to $281,000.
Borrowing $10,000 and keeping the proceeds as cash adds $10,000 to assets and $10,000 to liabilities. It does not initially increase net worth. Spending existing cash to repay $10,000 of loan principal reduces both assets and liabilities by the same amount, leaving net worth unchanged before interest or charges.
Those examples describe balance-sheet arithmetic, not a recommendation about borrowing or repayment. Interest, fees, taxes and later changes in asset values can affect the eventual result.
Positive net worth does not guarantee liquidity
A person can own substantial home equity yet have little cash for the next bill. Property may take time to sell and a sale can involve costs. Retirement accounts and other assets can also have access restrictions or tax consequences.
Income and spending are flows over time. Net worth is a position at a date. The CFPB separates cash-flow timing from broader measures of financial wellbeing. Payment deadlines, income reliability, debt costs and access to cash are additional parts of the picture.
Negative net worth means measured liabilities exceed measured assets. It does not alone explain the cause or determine legal insolvency. A student loan, an asset-price decline and accumulated business losses can produce very different circumstances.
Company net worth and market value
For a company, accounting net assets normally equal the residual equity after recognized liabilities are subtracted from recognized assets. The SEC explains this relationship in its balance-sheet guide.
Book equity follows accounting recognition and measurement rules. It is not automatically the market value of shareholders’ holdings or a liquidation estimate. Internally developed assets, future earnings expectations, selling costs and market conditions can make those values differ.
Net worth also does not provide a complete credit assessment or an accurate history of every investment. Lenders can consider income, cash flow, debt servicing, collateral and credit records alongside balance-sheet amounts.
The purpose determines the scope
A household wealth estimate and a regulatory eligibility test can use different definitions. For example, the SEC’s Regulation Crowdfunding bulletin excludes the primary residence from its specified net-worth calculation and sets related mortgage rules. That specialized test should not be substituted for an ordinary household statement without explanation.
Comparisons are strongest when they use the same date, currency, ownership scope and valuation method. An estimated property value should remain identified as an estimate, rather than being presented as cash already realized.
Last checked and updated on November 11, 2026 by the MBN editorial team.