
The neutrality of money is the proposition that a change in the level of the nominal money supply leaves real economic quantities unchanged after the relevant adjustment. In models with long-run neutrality, money and prices can change without a lasting change in real output or employment.
This is a statement about a model and its assumptions, not a rule that every monetary-policy action has no real effect. The short-run transition and the meaning of money supply both matter.
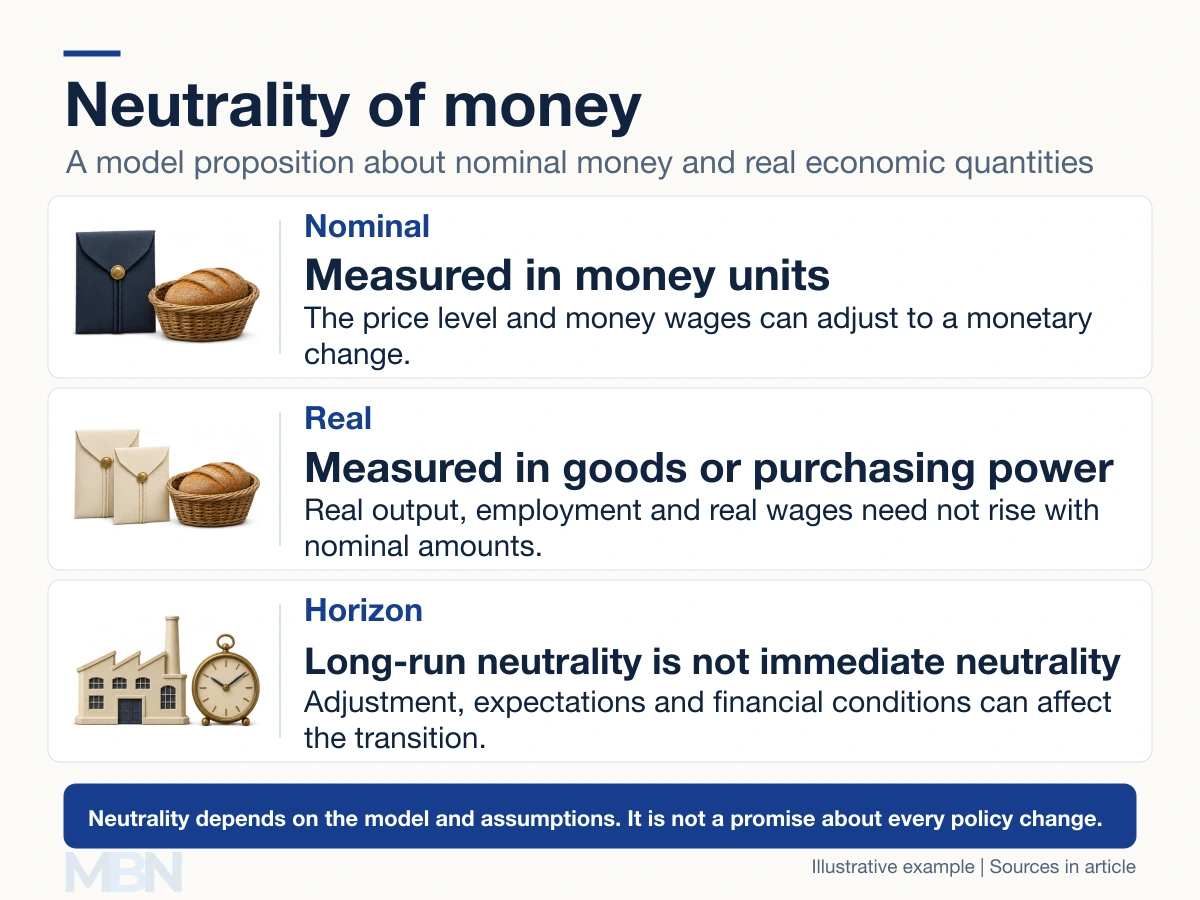
Nominal and real variables
A nominal wage is expressed in currency, such as dollars per hour. A real wage measures the goods and services that wage can buy. Nominal GDP values production at current prices; real GDP adjusts for price changes.
The ECB’s account of monetary-policy scope distinguishes short-run transmission from long-run neutrality. A rise in nominal income is not automatically an increase in real living standards.
A proportional-adjustment example
Suppose an economy’s money stock doubles once, while the model holds real production and the relevant money-demand conditions unchanged. In a simple neutral equilibrium, the price level and nominal incomes double too.
A person with $20 of nominal income could initially buy ten loaves at $2 each. After proportional adjustment, $40 of income buys ten loaves at $4 each. The dollar amounts doubled, but the quantity affordable did not.
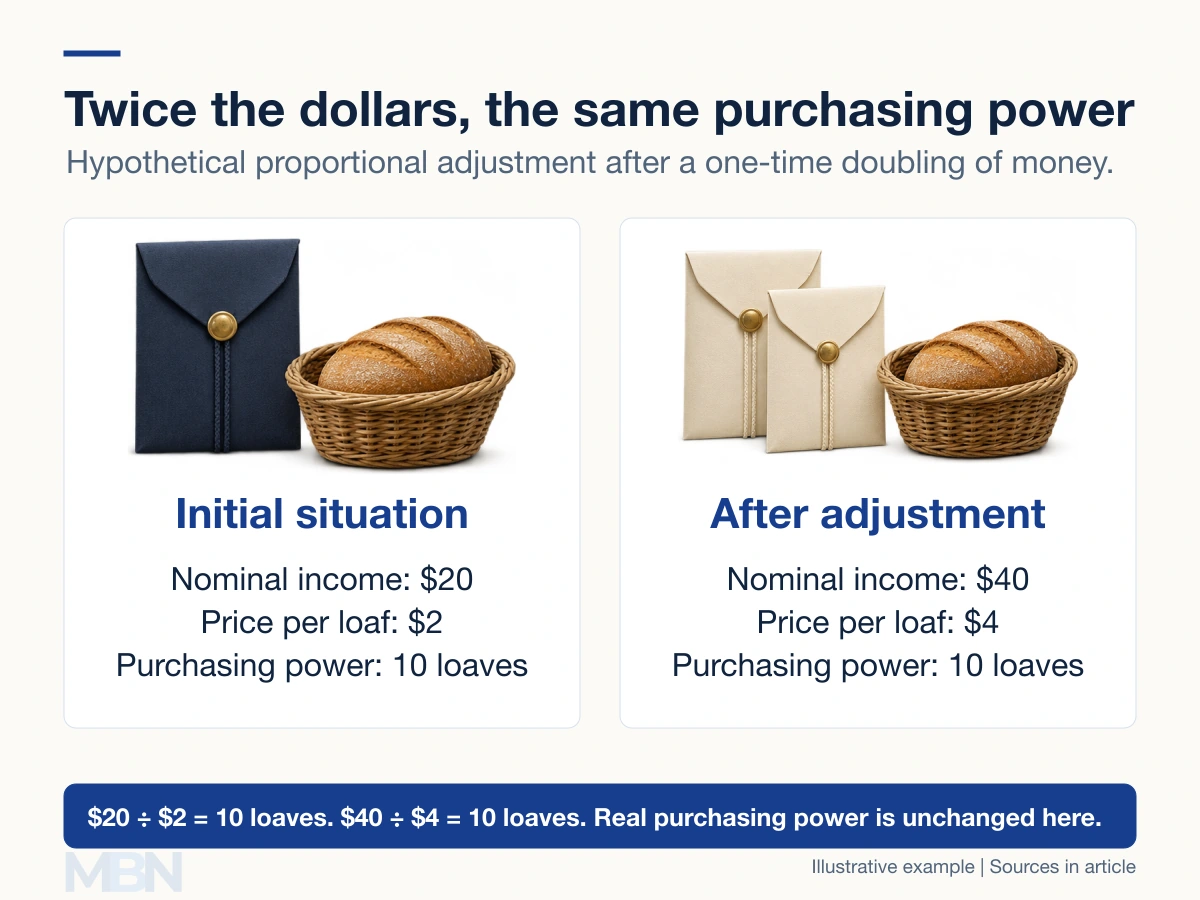
The currency unit’s purchasing power has halved in this example. That does not mean real incomes always double at once when a central bank expands its balance sheet. Federal Reserve research on money and inflation explains the assumptions behind proportionality and neutrality.
The quantity equation needs interpretation
The equation MV = PY links the money stock (M), velocity or turnover of money (V), the price level (P) and real output (Y). The St. Louis Fed’s explanation uses it to distinguish money, spending and production.
The equation alone does not prove that a change in M causes the same proportional change in P. Velocity, real output and money demand can change. The Richmond Fed examines why base money and prices need not move proportionally, including the role of bank reserves and interest paid on them.
Short-run effects and long-run debate
Prices, wages and contracts do not all adjust immediately. Monetary policy can change borrowing costs, demand and financial conditions, affecting output and employment during adjustment. Neutrality in a long-run model does not imply a costless transition for every household or firm.
Research also examines whether effects can persist through investment and productive capacity. A San Francisco Fed research summary presents evidence challenging complete long-run policy neutrality. The size and persistence of effects remain questions for evidence and model design, rather than settled by a definition.
Neutrality and superneutrality
Neutrality concerns a change in the money stock’s level. Superneutrality is stronger: a permanent change in the money-growth rate also leaves long-run real quantities unchanged. One proposition does not logically establish the other.
Persistent inflation can affect money holding, taxation, contracts and resource allocation. Those channels help explain why a model may allow neutrality of a one-time level change while rejecting superneutrality. Neither concept implies that unlimited money creation can create unlimited real goods and services.
Last checked and updated on November 11, 2026 by the MBN editorial team.