
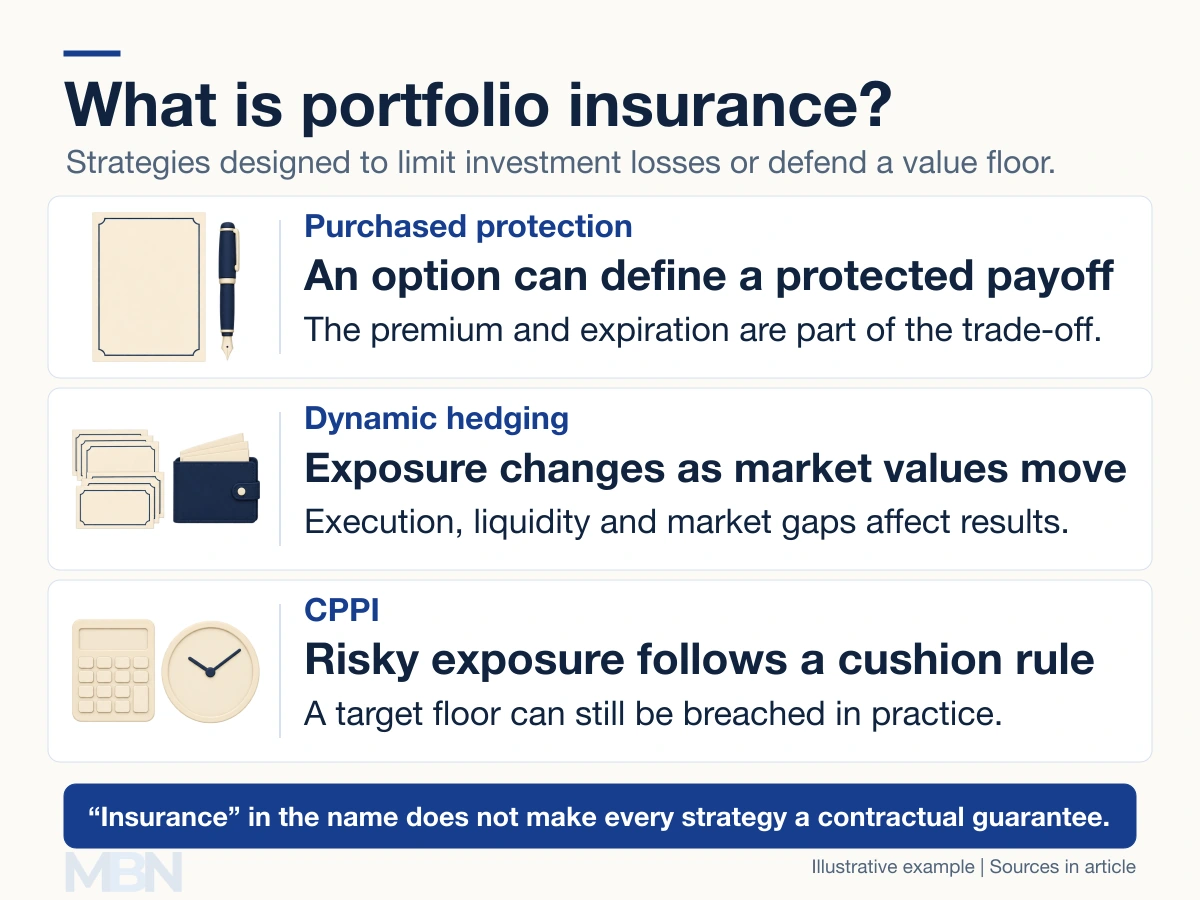
Portfolio insurance describes investment strategies designed to limit losses or keep a portfolio above a chosen value floor while retaining some opportunity for gains. Methods differ, and the name does not itself establish a guarantee from an insurer or other institution.
A portfolio is a collection of investments. Its protection might involve buying options, changing the mix of risky and safer assets, or adjusting a hedge as prices move. These approaches have different costs and failure risks.
How can options provide protection?
A put option gives its holder the right, under the contract’s terms, to sell an underlying asset at a specified strike price. Pairing an asset with an appropriately matched put can establish a minimum exit price during the protection period.
The Options Industry Council explains that a protective put costs a premium and ends at expiration. The strike price, original purchase price and premium together determine the potential loss. Protection does not necessarily preserve the full amount originally invested.
Coverage must also match the holding. An index option used against a different collection of shares can leave a mismatch between the hedge and the portfolio. CFA Institute distinguishes protective puts from collars, which can reduce protection costs by also limiting upside.
What is dynamic portfolio insurance?
Dynamic hedging changes exposure as market conditions change, instead of simply buying and holding a protective option. One approach reduces stock-market exposure through sales of shares or stock-index futures as markets fall.
Constant proportion portfolio insurance, or CPPI, links risky-asset exposure to a multiple of the cushion: the portfolio’s current value minus its chosen floor. A smaller cushion calls for less risky exposure under the rule.
Rama Cont and Peter Tankov’s research shows why real-world CPPI has gap risk. Markets can jump before the manager can rebalance, allowing portfolio value to cross the intended floor.
A CPPI example
Our fictional portfolio starts at $100, with an $80 floor and a multiplier of three. Its $20 cushion implies $60 in risky assets and $40 in a safer holding.
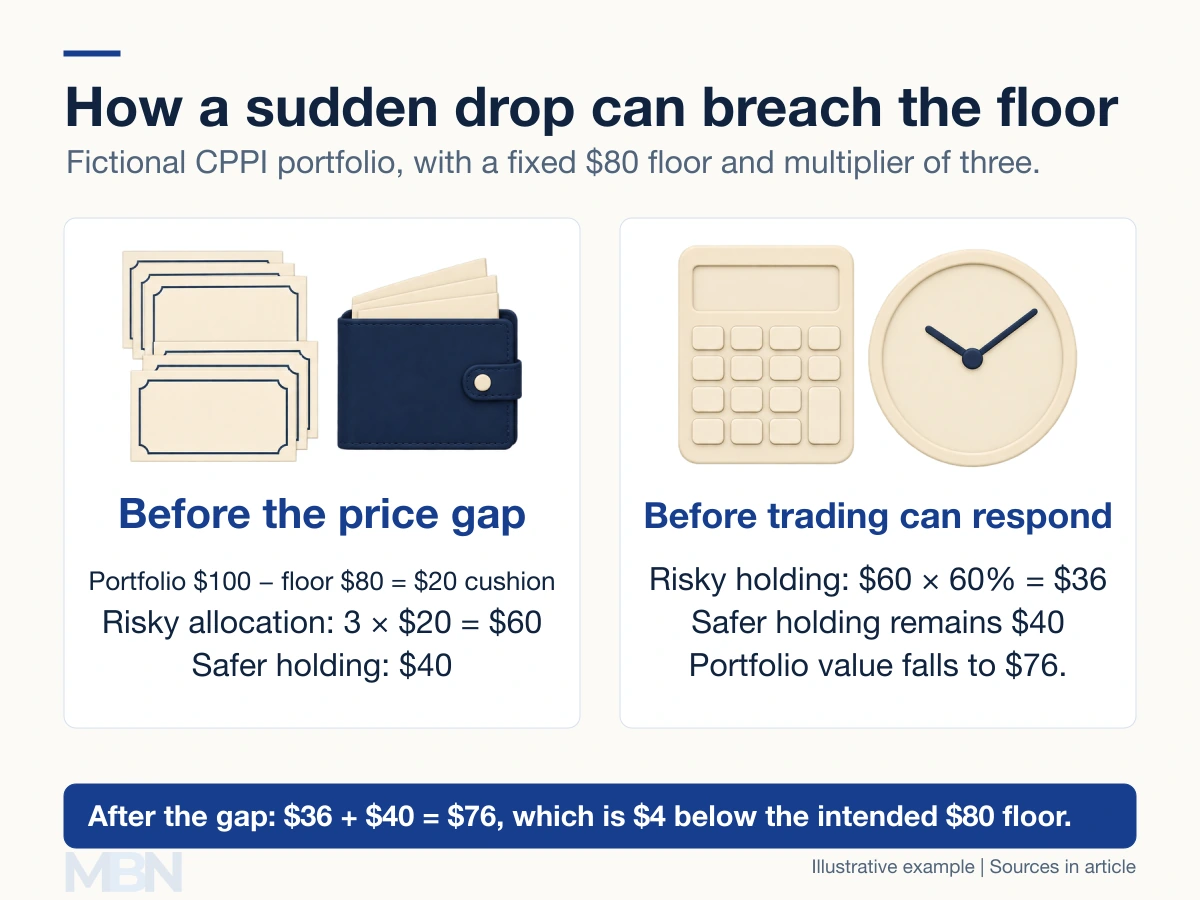
Assume the risky assets suddenly fall 40% before any trade can occur. They fall from $60 to $36. With the other holding unchanged at $40, the portfolio is worth $76, below its intended $80 floor.
This simplified example excludes interest, fees, taxes and changes in the floor. It illustrates an execution gap rather than predicting how any particular product will perform.
Why is the strategy associated with 1987?
A Federal Reserve research history discusses portfolio insurance during the October 1987 stock-market crash. Strategies calling for sales into a falling market contributed to selling pressure while trading and liquidity were strained.
That history should not be reduced to a single cause of the crash. It demonstrates why an individual hedging rule can depend on market conditions, execution and the actions of other investors. Any separate contractual capital guarantee must be assessed on its own terms and provider.
Last checked and updated on November 3, 2026 by the MBN editorial team.