
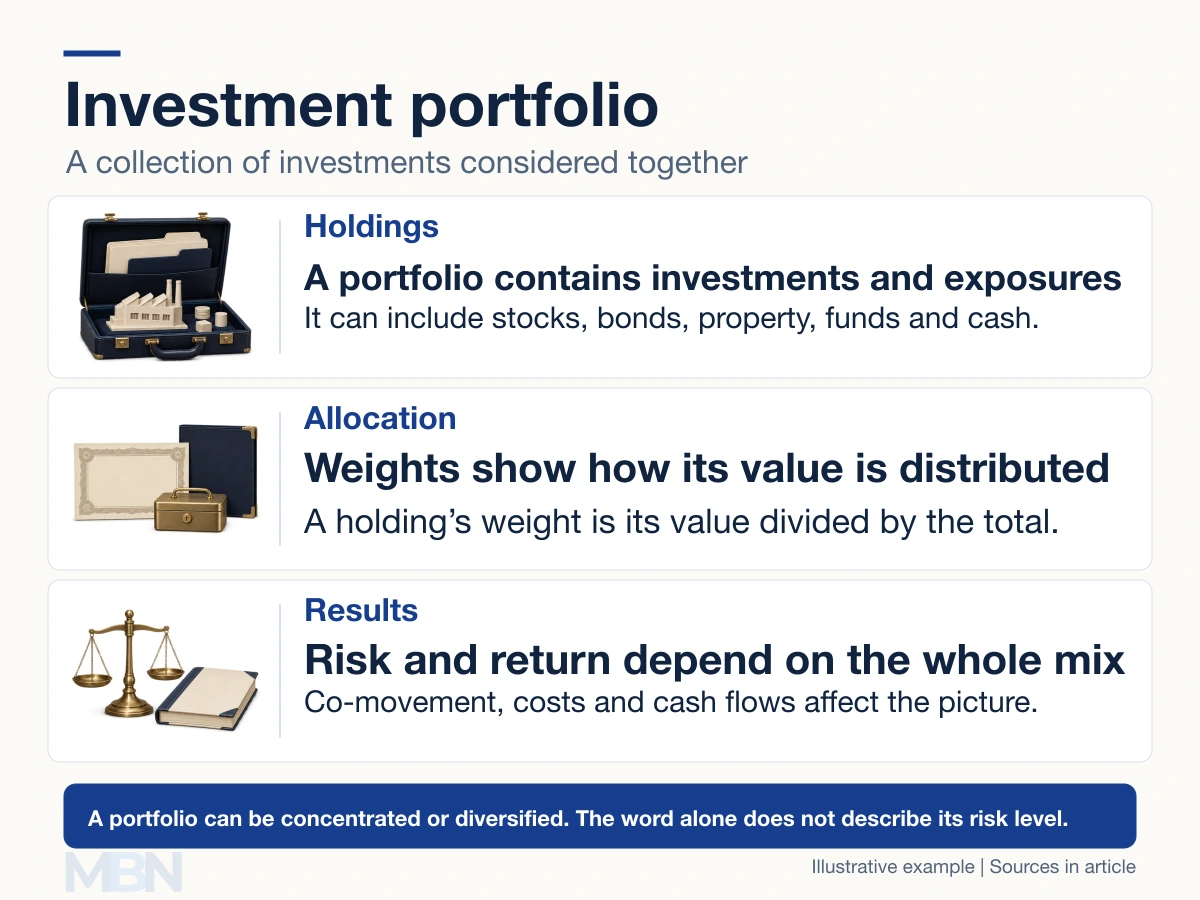
An investment portfolio is a collection of investments held by a person or institution and considered together. It can include stocks, bonds, funds, property, commodities, cash and other assets. Its purpose and composition depend on the owner’s objectives.
The SEC defines a portfolio as combined investment holdings. A portfolio need not be broadly diversified. It can be concentrated in one company, industry or asset class.
Holdings, accounts and asset allocation
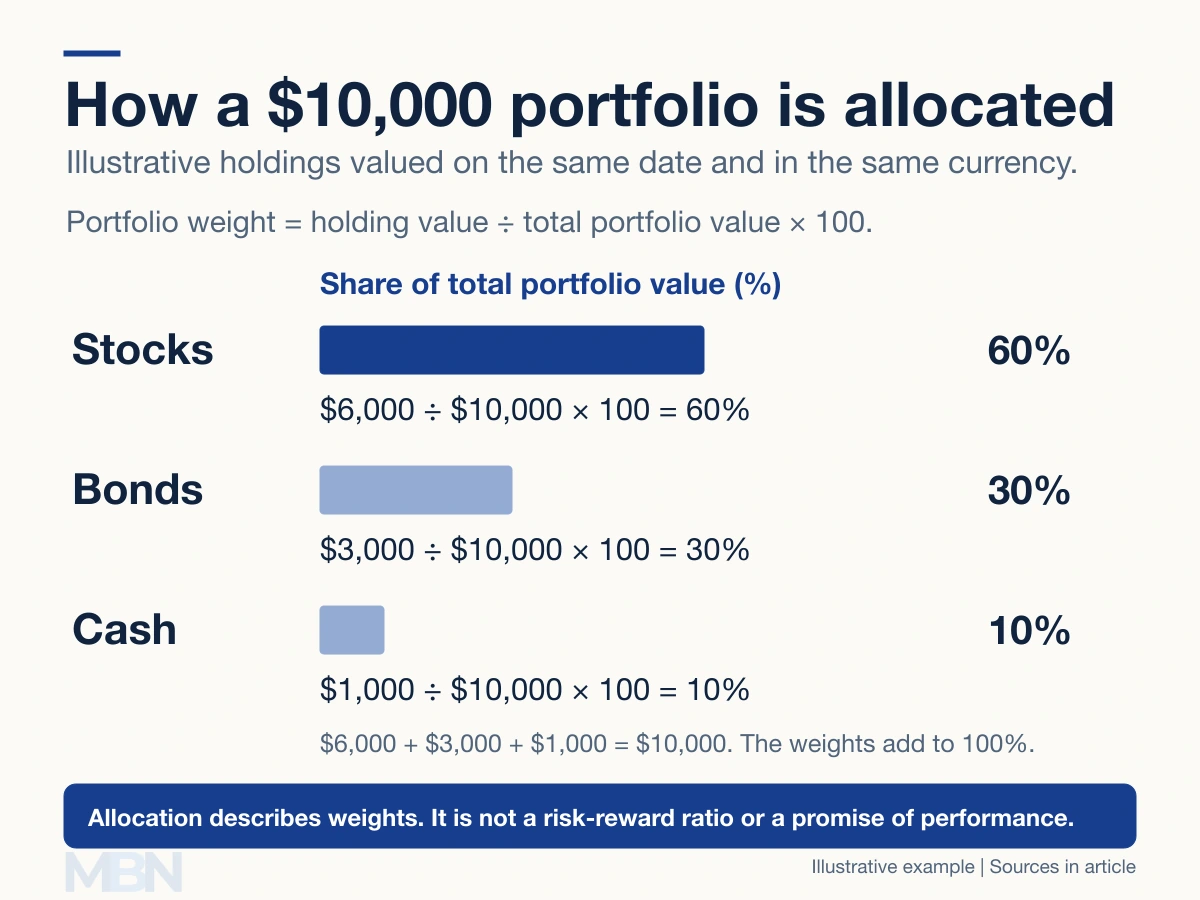
A holding is an individual investment or position. Asset allocation describes how the portfolio is divided among categories, such as stocks, bonds and cash. The weight of a holding is its current value divided by total portfolio value.
An account is the arrangement in which investments are held. One investor may assess holdings across several accounts as a combined portfolio. A fund can be one holding in that investor’s portfolio while containing its own underlying portfolio.
ASIC’s Moneysmart definition includes managed investments, property, derivatives and cash. Derivatives are contracts whose value depends on another asset or variable. Borrowing and derivative exposures can make a simple calculation of positive holding weights inadequate, so the scope should be stated.
A simple allocation example
Suppose an investor has $6,000 in stocks, $3,000 in bonds and $1,000 in cash. The total is $10,000. Their weights are 60%, 30% and 10%, respectively.
If the stocks rise 10% to $6,600 and the other values remain unchanged, the portfolio becomes $10,600. With no deposits, withdrawals, income payments, fees or taxes, its return is $600 ÷ $10,000 = 6%.
The stock weight is now $6,600 ÷ $10,600, approximately 62.26%. Allocation can therefore drift even when no trade is made. The SEC’s guide explains rebalancing as restoring a chosen mix; doing so can involve costs and taxes.
How the combined risk differs
Portfolio risk depends on individual exposures, their sizes and how their returns move together. Two equally valued portfolios can have very different risk. A holding’s dollar value alone does not determine a risk-reward ratio.
Diversification can reduce the impact of a particular company’s failure, but does not eliminate market-wide losses. Funds with different names can own the same securities or share the same economic exposures. FINRA explains these sources of concentration risk.
Even businesses described as defensive can lose value. A sector label does not make a stock immune to recession, debt problems or changes in interest rates. There is also no universal rule limiting every focused fund to thirty companies or three sectors; its actual mandate and holdings determine its concentration.
Managing a portfolio
Management can include selecting holdings, setting weights, handling cash needs and reviewing exposure limits. A manager may follow an index or make active decisions under a stated mandate. Some portfolios are managed directly by their owners.
The objective normally involves a trade-off among expected return, risk, liquidity, time horizon and costs. It is not generally possible to maximize return and minimize every risk simultaneously. The SEC explains how goals and risk tolerance affect allocation.
Measuring performance
Growth in the account balance is not necessarily investment return. Deposits add value, while withdrawals remove it. Income, price changes, fees and taxes also need consistent treatment.
A time-weighted return links returns between external cash flows, limiting the effect of deposits and withdrawals on the performance measure. A money-weighted return reflects the size and timing of those flows. The GIPS Standards Handbook explains the distinction and its reporting context.
Neither measure is inherently a monthly or quarterly method. The period, currency, fee basis and whether returns are expressed as a yearly rate should match the comparison being made. A return figure alone does not reveal the risks taken to earn it.
Last checked and updated on November 11, 2026 by the MBN editorial team.