
Private equity is ownership investment in businesses whose shares are not publicly traded on a stock exchange. The term also describes an investment industry that raises and manages capital to acquire or fund such ownership interests.
Equity is a claim on ownership. A loan is a debt claim, even when the lender is a private investment firm. Private equity managers can operate other strategies, but private credit and private equity are not interchangeable assets.
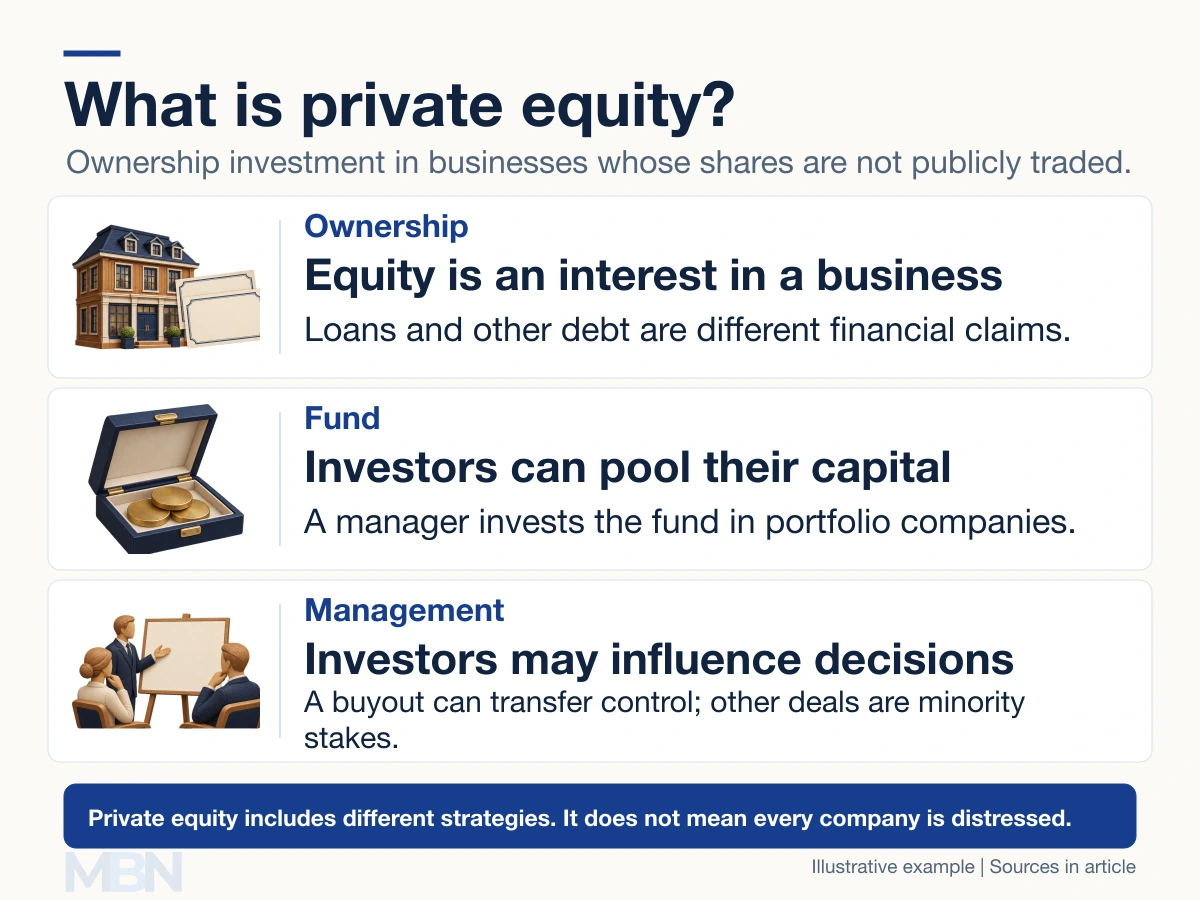
How does a private equity fund work?
A fund pools capital from investors and buys interests in businesses, often called portfolio companies. The fund, its investment manager and the portfolio company are separate parts of the arrangement.
In a common limited-partnership structure, limited partners commit capital while the general partner manages the fund. The SEC explains that capital can be called over time, so a commitment is not necessarily paid in full on the first day.
The governing agreements determine fees, expenses, profit-sharing, withdrawal limits and other rights. Not every fund has the same structure or lifespan.
What kinds of businesses receive investment?
Buyout funds commonly acquire control of established businesses. Growth investors may buy minority stakes to fund expansion, while venture capital focuses on younger businesses with growth potential.
Private equity is not restricted to unprofitable or failing companies. Profitable businesses can be acquired too. The SEC’s investor guide describes both controlling and minority investments.
Venture capital is often included within a broad definition of private equity, though industry discussions also distinguish venture funds from buyout funds. A minority investor can have board representation, information rights and an active advisory role. Minority ownership does not establish a hands-off approach.
What is a leveraged buyout?
A leveraged buyout uses borrowing alongside equity to finance an acquisition. The resulting debt creates payment obligations and can amplify changes in the owners’ investment value.
For a simplified fictional example, assume a business worth $100 million has $60 million of net debt, leaving $40 million of equity value. Net debt means debt after the cash adjustment used in the valuation. Assume no other claims or adjustments.
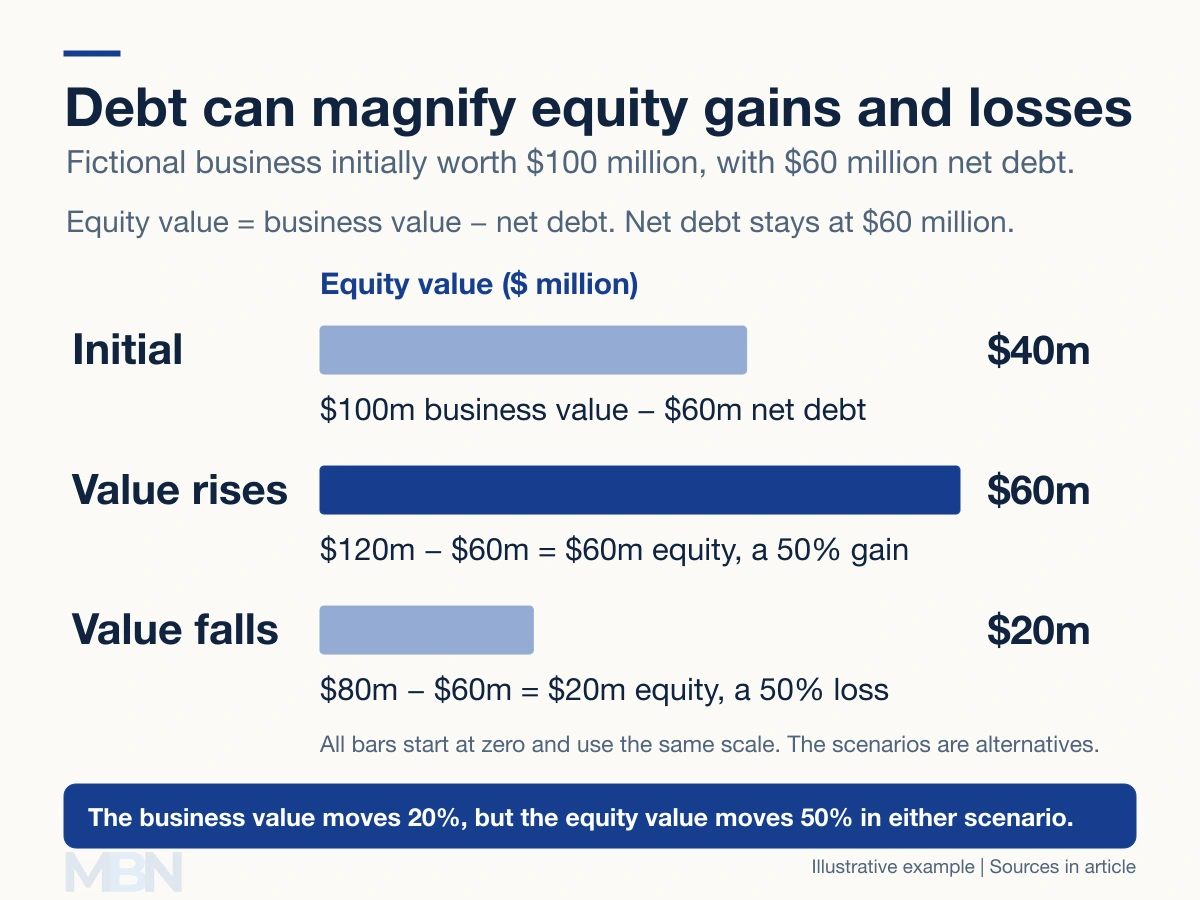
If the business value rises to $120 million while net debt stays at $60 million, equity value becomes $60 million. The $20 million increase is 50% of the initial $40 million equity.
In a separate downside scenario, business value falls to $80 million and unchanged debt leaves $20 million of equity, a 50% loss. The example excludes interest, fees, taxes, debt repayment and operating cash flows. It illustrates the mechanics, rather than predicting a return.
The National Association of Insurance Commissioners discusses leverage and liquidity risks in private equity. Borrowing adds obligations regardless of whether the investment performs as hoped.
How can investors receive money back?
A fund may sell a portfolio company to another business or investor, or take it to a public market through an initial public offering. It may also receive dividends or proceeds from a recapitalization.
A recapitalization changes the financing mix. A payment funded by new borrowing is different from profit generated by operations, and an estimated investment value is different from cash distributed to investors.
Why are liquidity, fees and valuation relevant?
Traditional private equity funds can restrict withdrawals for years, while selling an interest may require finding a buyer and meeting transfer conditions. Management fees, expenses and performance-related profit shares reduce what investors retain.
Values for unlisted holdings rely on valuation methods and available evidence. Less frequent valuation updates do not establish that the underlying business is less risky than a listed one.
Traditional private funds generally serve institutional and eligible private investors. Other fund structures can provide exposure to private assets. An October 2026 Federal Reserve note explains semiliquid retail funds, which offer periodic, constrained repurchases rather than the daily liquidity associated with ordinary open-end mutual funds.
Last checked and updated on November 3, 2026 by the MBN editorial team.