
Q theory explains business investment through the value of capital already installed in a company compared with the cost of acquiring or replacing capital. When an additional unit is worth more inside the business than it costs to obtain, the firm has an incentive to invest.
The familiar measure, Tobin’s q, compares market valuation with replacement cost. It connects financial-market valuations to spending on productive assets. It is not a rule telling investors to buy shares whenever q exceeds one.
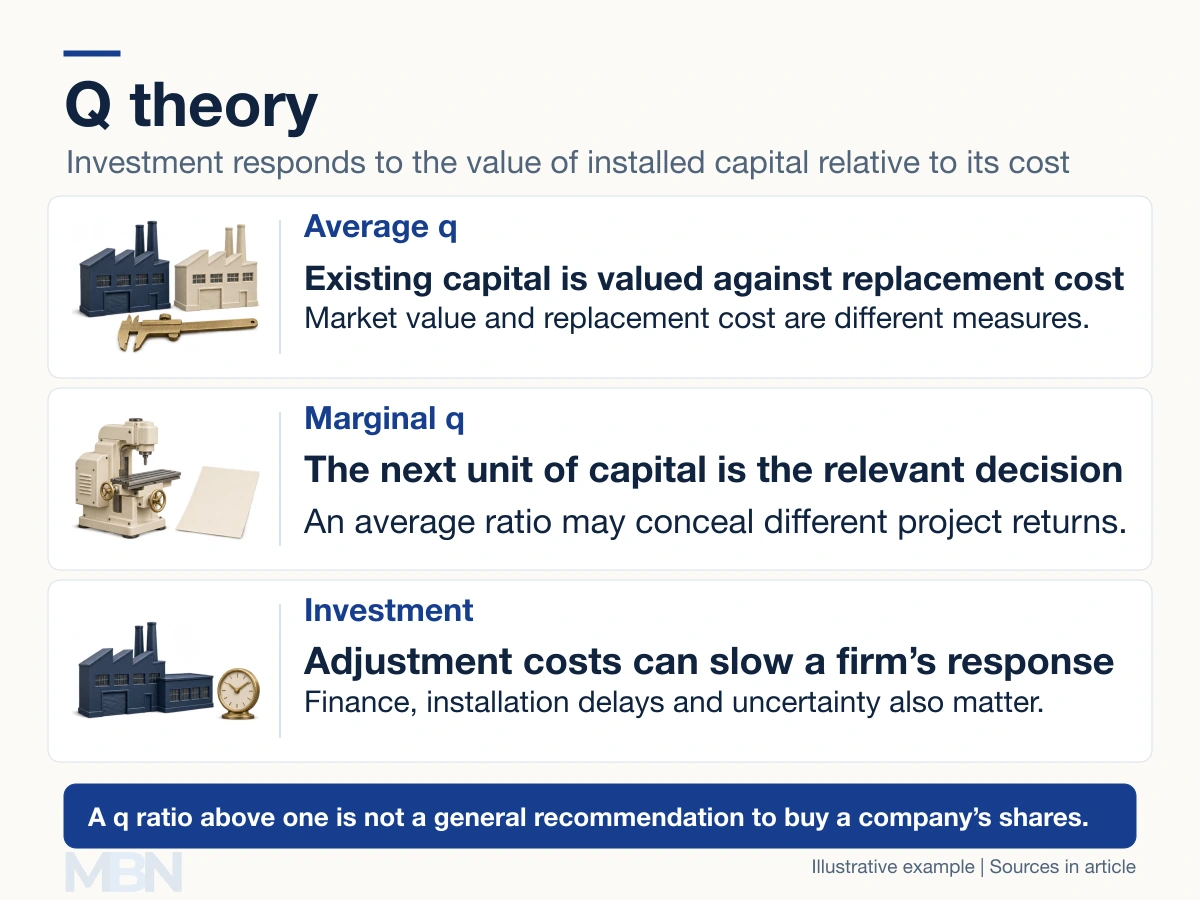
How average q is calculated
Average q = market value of the relevant installed capital ÷ its replacement cost. The US Bureau of Economic Analysis uses q ratios to compare financial-market asset valuations with current-cost asset values.
For a simplified company example, the numerator includes market equity and debt associated with the asset base. Share-market value alone does not represent the value of assets financed partly by creditors. Actual calculations can also adjust for financial assets and other claims.
The denominator estimates the cost of replacing the relevant capital at current prices. It is not the number of shares, the historical cost of share capital or necessarily the balance sheet’s asset value. The numerator and denominator must cover a consistent business and asset base.
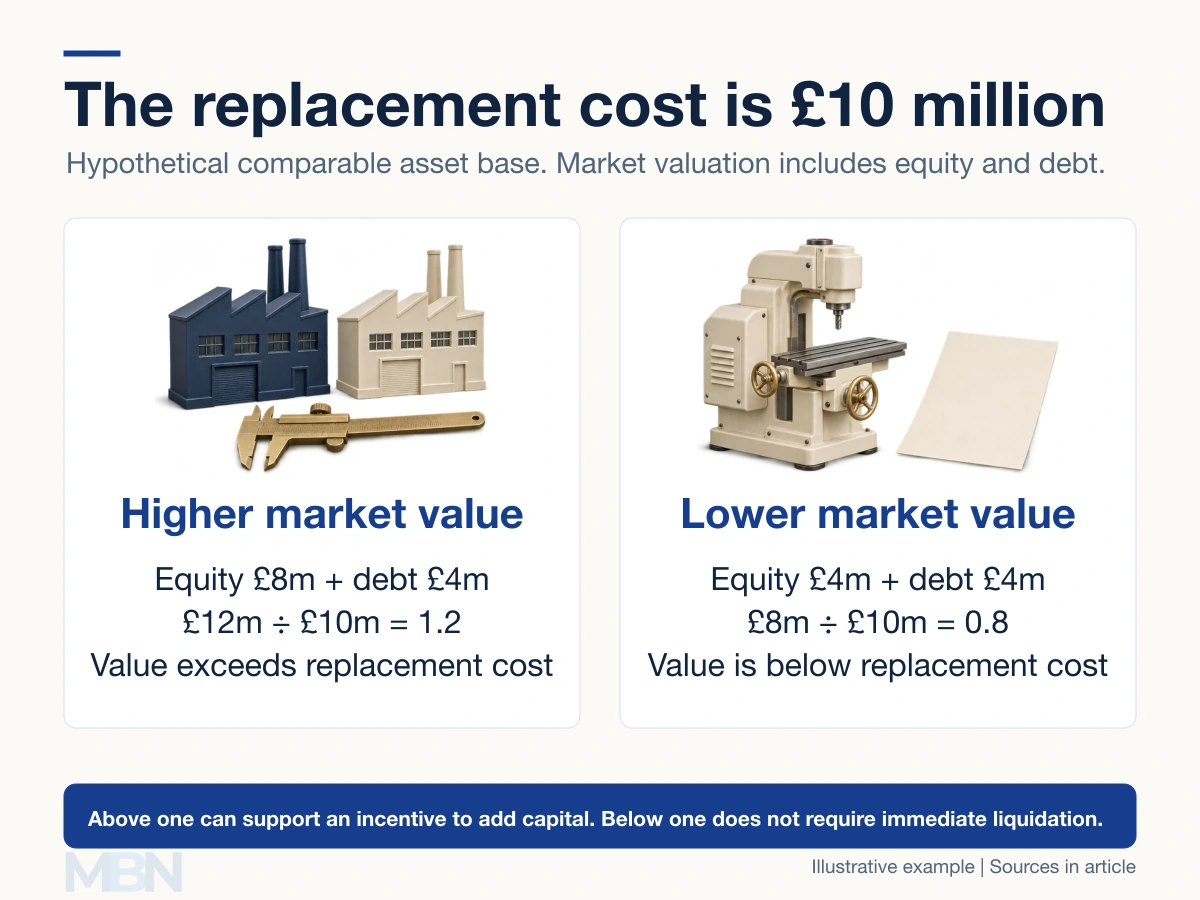
If replacement cost is £10 million and market equity plus debt is £12 million, average q is 1.2. If the market valuation falls to £8 million with replacement cost unchanged, q is 0.8. These ratios compare values; they do not mean profits are respectively 20% or −20%.
Why marginal q matters
Marginal q concerns the value of an additional unit of installed capital relative to its acquisition cost. It asks about the next investment, rather than the average value of everything already owned.
The Reserve Bank of Australia explains that average and marginal q coincide only under particular assumptions. A valuable existing business can still have a poor expansion project. Conversely, a firm with weak older assets may have a worthwhile new investment.
Because marginal q is difficult to observe, researchers often use average q as a proxy. Financing constraints, taxes and differences among assets can weaken that relationship.
Investment does not adjust instantly
In a simple model without adjustment costs, a marginal value above acquisition cost encourages expansion; a value below cost discourages adding capital. With adjustment costs, the value of the next unit must also cover the extra cost of installing it.
Those costs can include disrupted production, recruitment and construction delays. NBER research on q theory examines investment with adjustment costs and multiple capital inputs. Irreversible spending and uncertainty can make waiting valuable. Capital can also run down through depreciation rather than an immediate asset sale.
What q can miss
Replacement cost is difficult to measure for brands, software, research, customer relationships and organisational knowledge. Research by Ryan Peters and Lucian Taylor examines intangible capital in the investment-q relationship.
A ratio based mainly on tangible assets can look high when valuable intangible resources are omitted. Market power, growth expectations and valuation errors also complicate interpretation. A high q is not proof of overvaluation, and a low q is not proof that a company should liquidate.
Price-to-book is a different ratio. It normally compares market equity with book equity, whereas q concerns capital value and replacement cost. Neither supplies a guaranteed market-timing signal.
James Tobin and the theory
The theory is associated with economist James Tobin, a 1981 economics Nobel laureate who served on President Kennedy’s Council of Economic Advisers. The Tobin Project’s biography identifies his Federal Reserve role as an academic consultant, rather than a member of its Board of Governors.
Last checked and updated on November 11, 2026 by the MBN editorial team.