
Random walk theory models a financial price or its logarithm as its previous value plus a new random change. In a simple random walk, successive changes are independent and follow the same probability distribution. Past changes do not reveal the next random step.
This is a model to be tested, rather than proof that all financial prices are completely unpredictable in every sense. Researchers distinguish different versions of the hypothesis and different meanings of market efficiency.
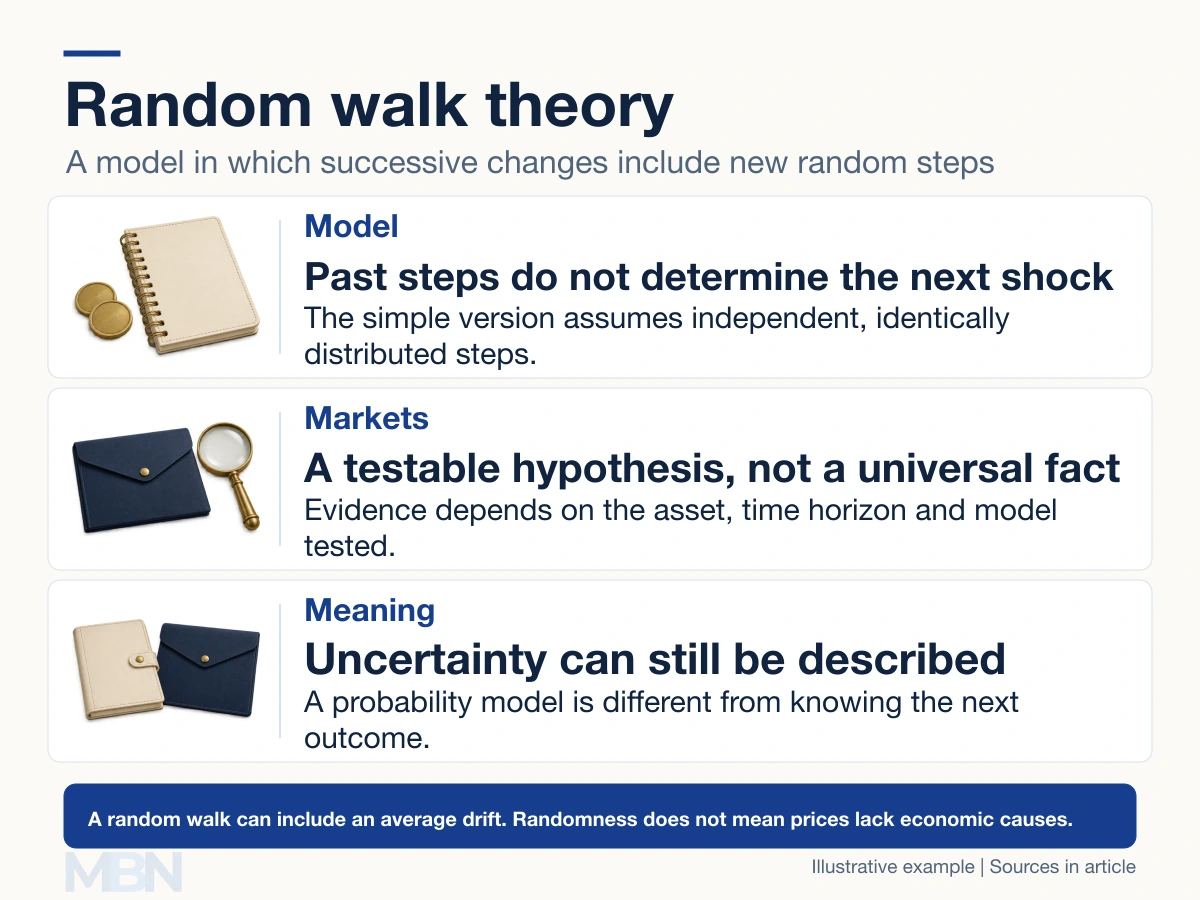
How a random walk works
A simple version can be written as: next value = current value + random step. A version with drift adds an average increment as well. A positive drift allows an expected upward movement over time, while individual steps remain uncertain.
The chosen variable matters. A model of dollar price changes differs from one applied to log prices, whose changes approximate percentage returns. A model’s assumptions also specify its step sizes and probabilities; real markets need not share them.
For a teaching example, start at 50. An independent fair coin toss adds one for heads or subtracts one for tails. The next value is therefore 51 or 49, each with 50% probability.
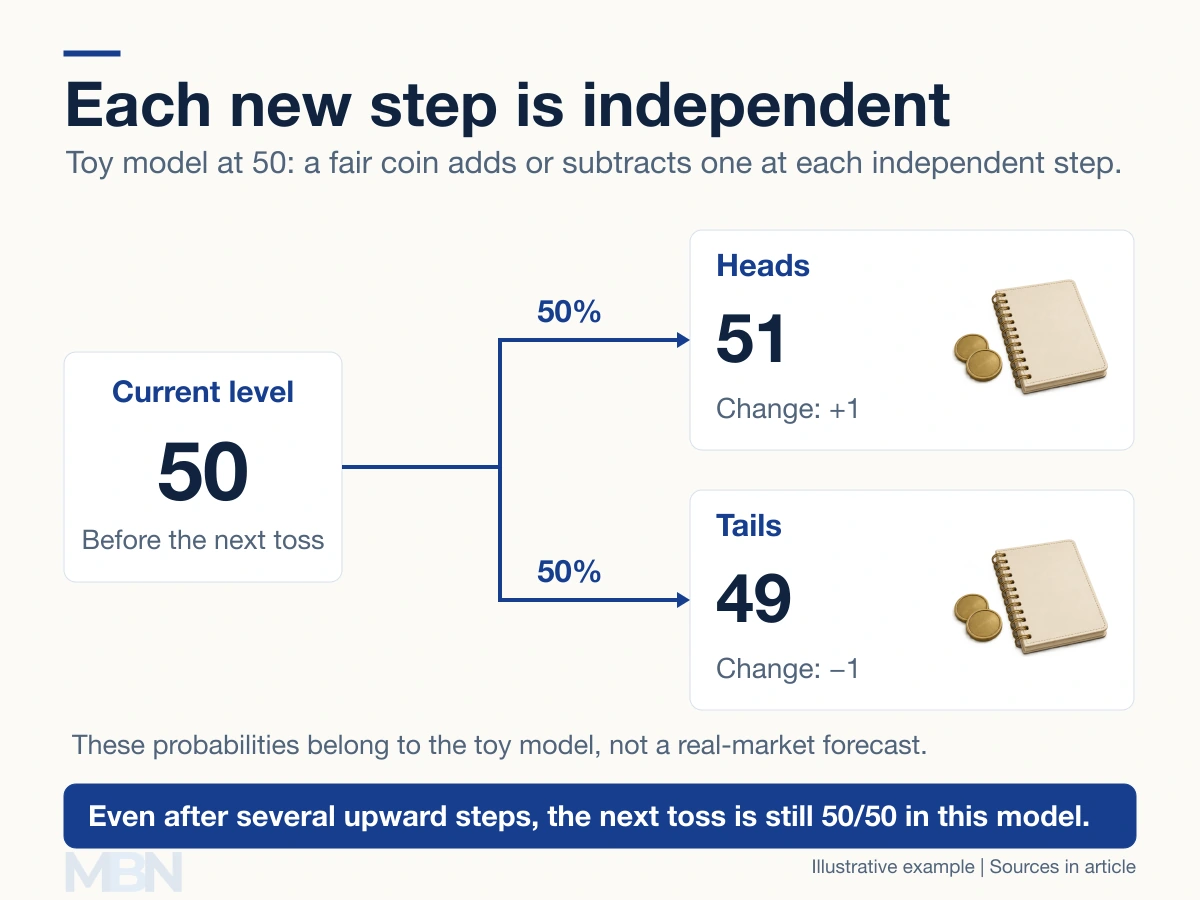
A run of upward steps does not make the next downward step “due.” Nor does it make another upward step more likely in this model. A finite random path can still display apparent trends.
Why the idea matters in finance
When new information changes investors’ expectations, prices can adjust quickly. If relevant past-price information is already reflected in today’s price, a familiar historical pattern need not provide an exploitable trading advantage.
The 2013 Nobel Prize explanation of asset-price research describes both the difficulty of short-term prediction and evidence of longer-horizon predictability. It does not reduce all asset-pricing research to the claim that nothing can be learned.
Random walks and efficient markets
The efficient-market hypothesis concerns how prices reflect a specified information set. Weak-form efficiency concerns past trading information; broader forms consider public or other information. A particular independent-step random walk imposes additional statistical restrictions.
For example, changing risk or expected returns can create predictable features without automatically offering a free profit. The concepts are related, but a rejection of one random-walk specification does not settle every question about market efficiency.
Federal Reserve research tests random-walk behaviour across markets, while other research examines how return predictability changes over time. Findings depend on data, methods and horizons.
Predictability is not guaranteed outperformance
A statistically detectable pattern may be too small, unstable or costly to exploit. Testing many strategies can also produce apparently impressive results by chance. Performance needs assessment against an appropriate benchmark and risk exposure.
Federal Reserve research on return anomalies accounts for trading costs, publication effects and out-of-sample testing. Conversely, an investor beating a benchmark for a period does not alone prove skill or disprove every random-walk model. Chance, risk and the comparison chosen all matter.
Last checked and updated on November 11, 2026 by the MBN editorial team.