
Redlining is discriminatory denial of, or unequal access to, credit or related services because of the racial composition or another protected characteristic of a neighborhood’s residents. A lender need not draw a literal red line on a map for the practice to occur.
The term is closely associated with US mortgage lending and housing history. Its central issue is discriminatory access, rather than every decision involving geography or every rejection of a loan application.
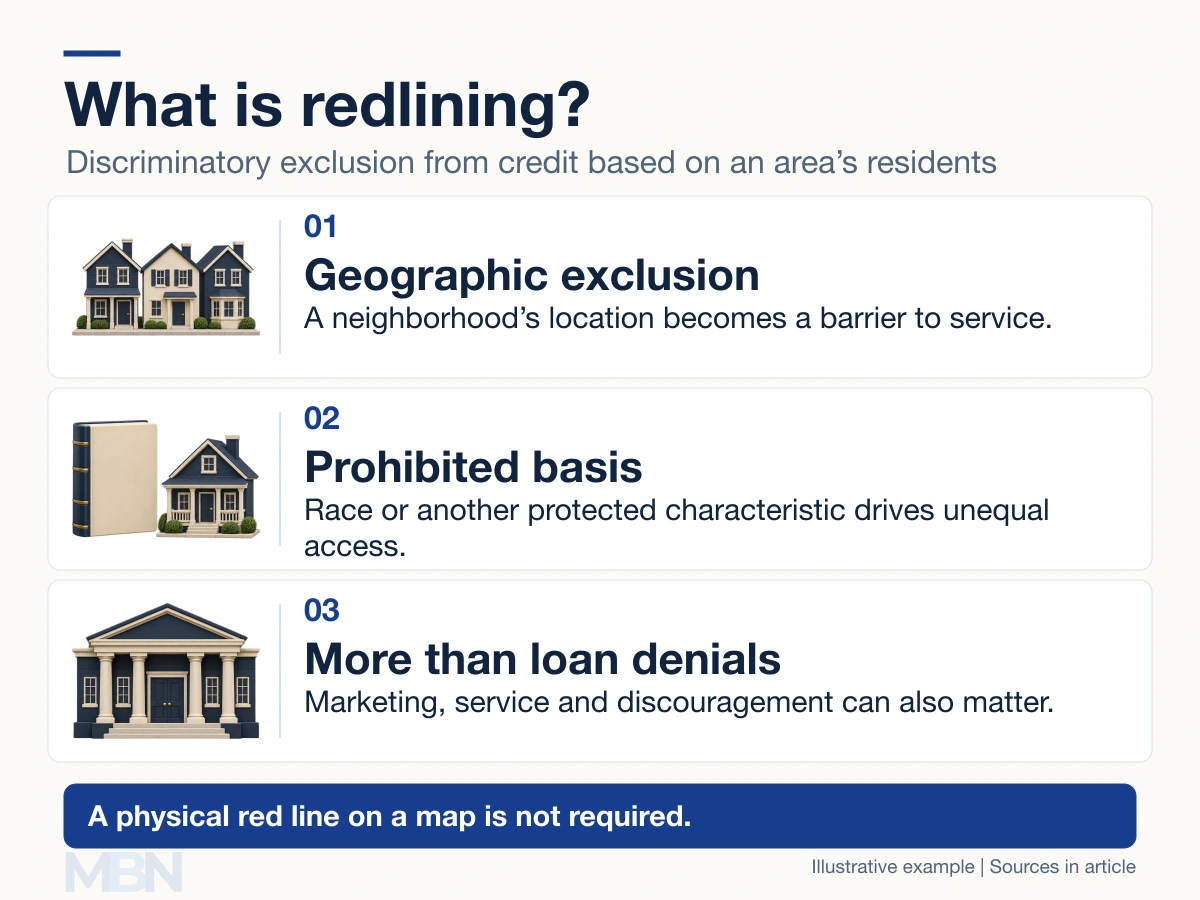
How redlining can operate
Discrimination can involve refusing applications, offering worse terms or discouraging prospective borrowers from applying. Patterns in marketing and service coverage can also matter. The FDIC’s fair-lending guidance discusses unequal geographic access on prohibited grounds.
For example, imagine two applicants with comparable relevant credit qualifications. One receives consideration, while the other is discouraged because the property is in a predominantly Black neighborhood. The hypothetical difference concerns discriminatory exclusion, rather than a demonstrated inability to repay.
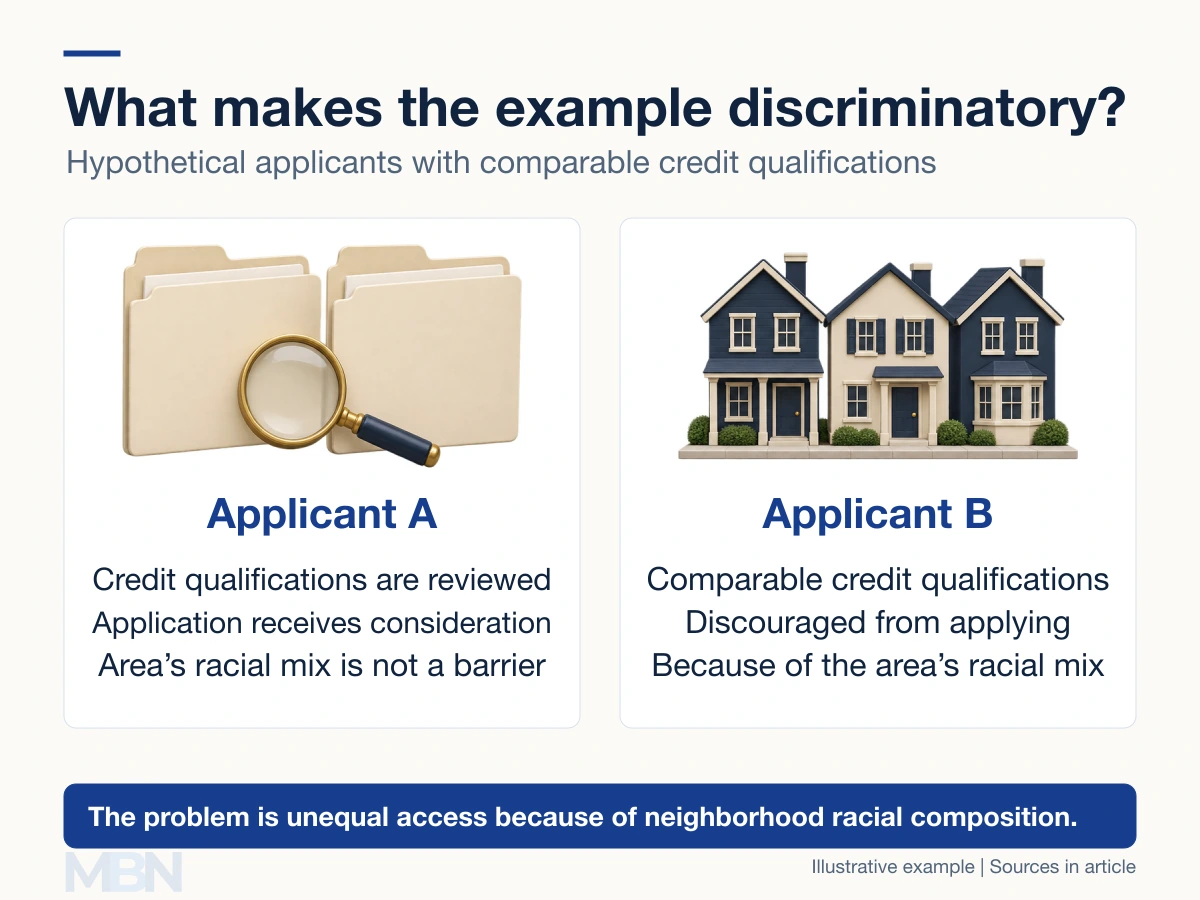
HUD’s fair-lending explanation covers discrimination across the mortgage process, including approvals, pricing, advertising, appraisals and servicing. It identifies denying a mortgage or charging more because of a majority-minority neighborhood as an example.
The legal framework is broader than the CRA
The Fair Housing Act of 1968 outlawed racially motivated redlining in housing-related lending. The Justice Department explains that mortgage discrimination can fall under both that Act and the Equal Credit Opportunity Act. Their scope and protected grounds are not identical.
The Community Reinvestment Act, or CRA, has a different role. Enacted in 1977, it directs assessment of covered institutions’ records of meeting community credit needs, including low- and moderate-income neighborhoods, consistently with safe and sound operations. It is not the sole legal basis for prohibiting racial lending discrimination.
Historical maps and housing finance
In the 1930s, government housing programs and private financial practices embedded discriminatory neighborhood assessments. Maps using red to mark areas rated unfavorably became enduring symbols of that exclusion.
Federal Reserve History’s account explains the Federal Housing Administration’s role and the interaction of public and private practices. The history is more complex than attributing every discriminatory lending decision to one set of preserved maps.
Restrictions on access to mainstream mortgage finance affected opportunities to buy homes and build equity. The persistence and size of particular effects require evidence for the place, period and outcome being discussed.
Risk assessment is not a blanket exception
Lenders can assess relevant repayment capacity and collateral under applicable law. Flood exposure, for example, can raise genuine property and insurance questions. Calling a policy “scientific” does not by itself establish that it is lawful or excuse discrimination on a prohibited basis.
A full assessment needs the actual policy, its application, the relevant legal test and evidence. Raw differences in loan numbers alone do not describe every applicant’s qualifications, a lender’s coverage or why decisions were made.
Insurance rules and other countries’ discrimination laws require their own analysis. “Redlining” is also used more broadly in discussions of unequal services, but the US lending explanation should not be treated as a universal legal definition for every sector.
Last checked and updated on November 6, 2026 by the MBN editorial team.