
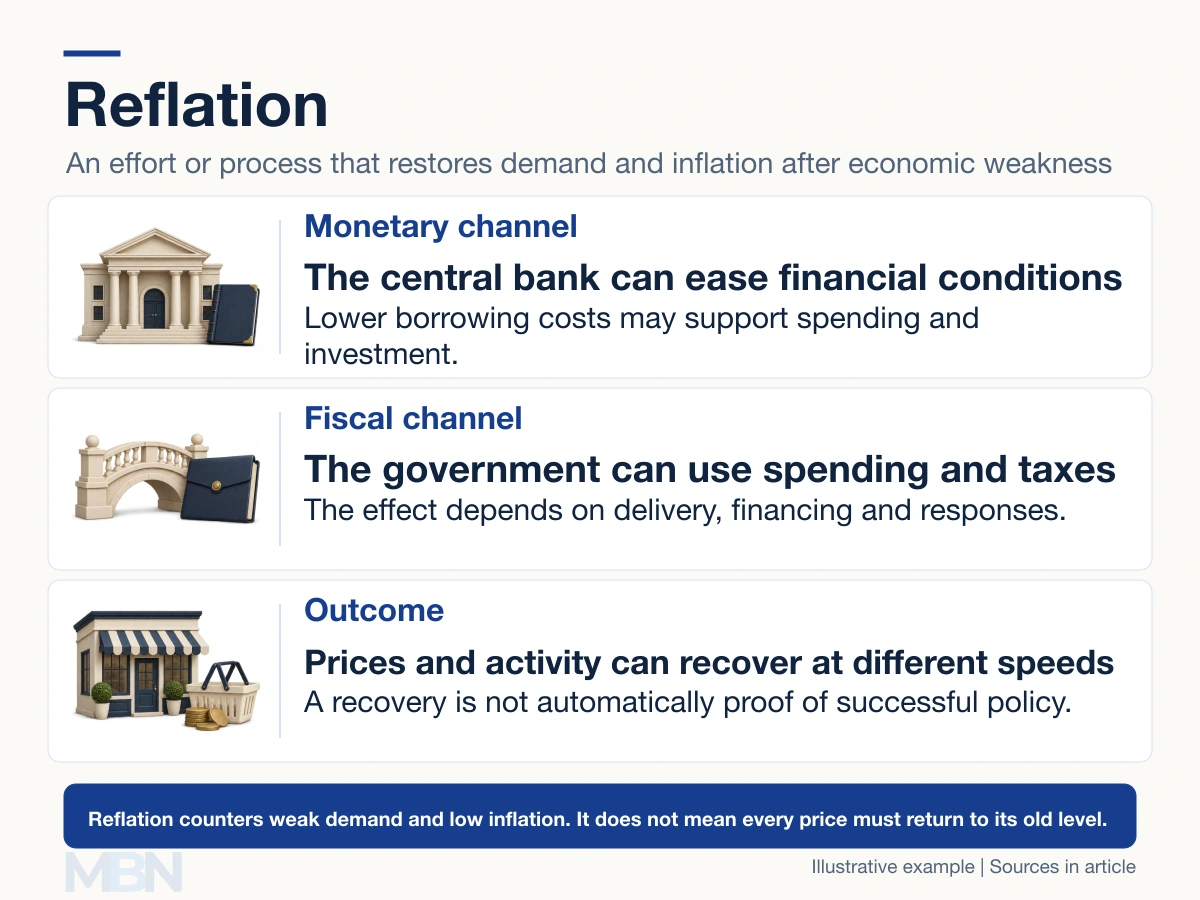
Reflation is an effort or process that lifts demand and inflation after a period of economic weakness, very low inflation or deflation. The term can describe policies intended to support a recovery, or the resulting improvement in nominal spending and prices. An intention and an achieved result are different.
Monetary policy is conducted by the central bank; fiscal policy concerns government spending and taxation. Either can support reflation, depending on the country’s circumstances and institutions.
Reflation, inflation and disinflation
Inflation is a rise in the general price level. Deflation is a sustained fall in that level, rather than an isolated discount or a cheaper product. Disinflation means the inflation rate falls, for example from 6% to 3%; prices can still be rising.
The St. Louis Fed explains these distinctions. Zero inflation means the measured general price level is unchanged over the comparison period, not that deflation has already occurred.
Reflation usually describes a recovery from unusually weak conditions. It is not a separate mathematical measure of prices, nor an official name for every economy’s first stage after recession.
How policy can support demand
A central bank may lower policy interest rates or use other tools to ease financing conditions. Lower borrowing costs can support consumption and investment. Policy communication can also influence expectations about future interest rates and inflation.
A Federal Reserve historical memorandum examines these channels when interest rates were very low. It discusses 1930s efforts to raise prices, then described as reflation, without establishing a universal recipe for later episodes.
Governments can increase purchases, invest in projects, adjust transfers or reduce taxes. The IMF explains these fiscal channels. The result depends on whether money is spent, saved or used for imports, as well as spare capacity, project timing and financing.
Neither approach ensures an immediate recovery. Borrowers may be unwilling to take on debt, banks may face constraints, and planned infrastructure can take years to deliver. A policy that raises demand can also raise prices more than output when supply is restricted.
A recovery in inflation is not a restored price level
Suppose a price index starts at 100, falls 2% to 98, then rises 2% the next year. It reaches 99.96. Positive inflation has returned, but the price level remains slightly below its starting point.
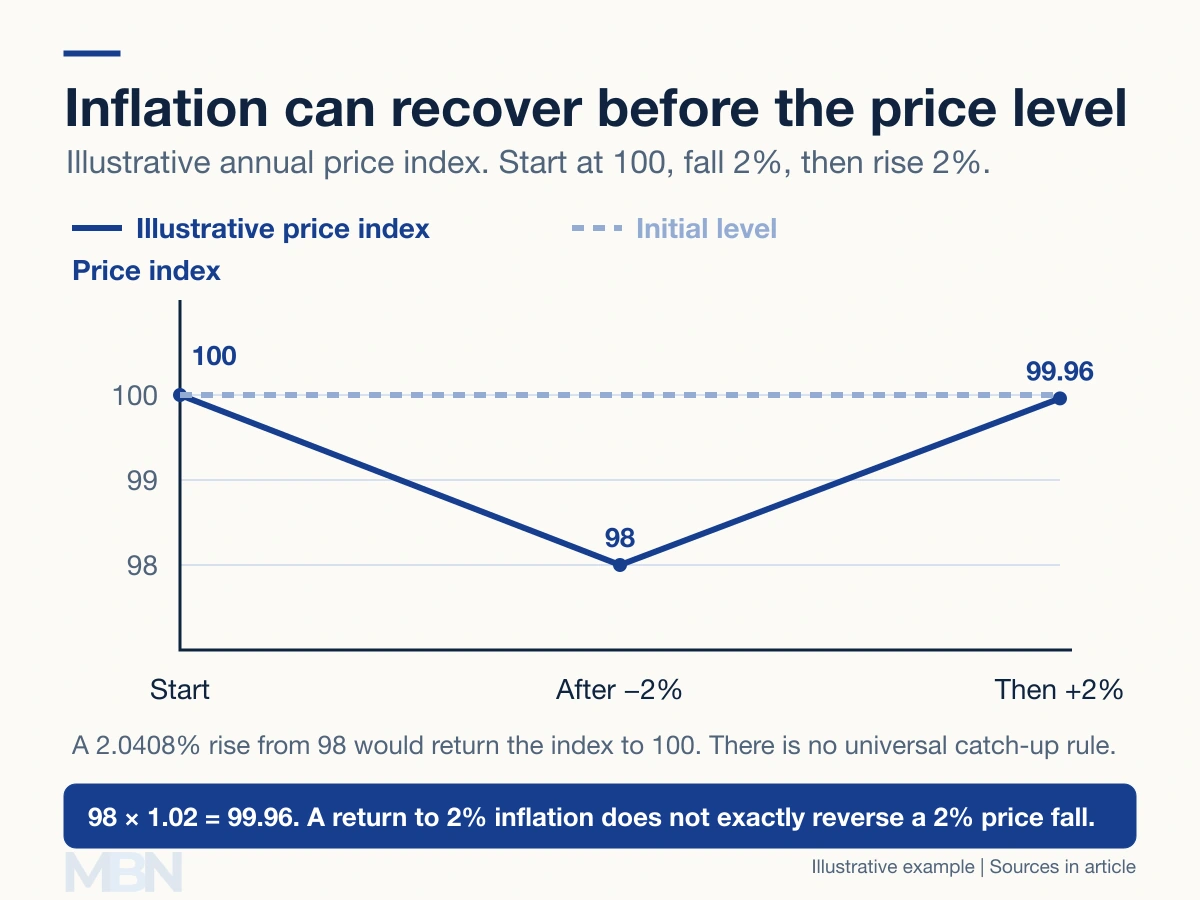
The Bank of Canada explains the difference between the price level and inflation. Restoring an inflation rate is different from making up every earlier departure from a price-level path.
Targets also differ. Australia’s Reserve Bank targets annual consumer-price inflation between 2% and 3%, with policy directed towards the midpoint. It is incorrect to describe every major central bank as having the same 2% point target.
What a reflation trade means
In financial markets, a reflation trade is a position based on expectations that growth and inflation will strengthen. Some investors may expect businesses sensitive to the economic cycle to benefit, or bond yields to rise.
These are expectations, not assured outcomes. Asset prices can already reflect the recovery, companies respond differently, and higher yields can reduce the prices of existing fixed-rate bonds. A market label is not proof that a lasting recovery has begun.
Limits and trade-offs
Policy assessment considers output, employment, inflation, expectations and financial stability together. A temporary energy-price rise may lift headline inflation without resolving weak underlying demand.
Support that continues too long can contribute to excessive demand, inflation or financial vulnerabilities. Decisions therefore depend on the outlook and how policies work over time, rather than a mechanical rule to stop once one indicator reaches a specified number.
Video explanation
This introductory video outlines fiscal and monetary tools. Its 2% reference is illustrative: targets differ, and policy does not have an automatic stopping point.
Last checked and updated on November 11, 2026 by the MBN editorial team.