
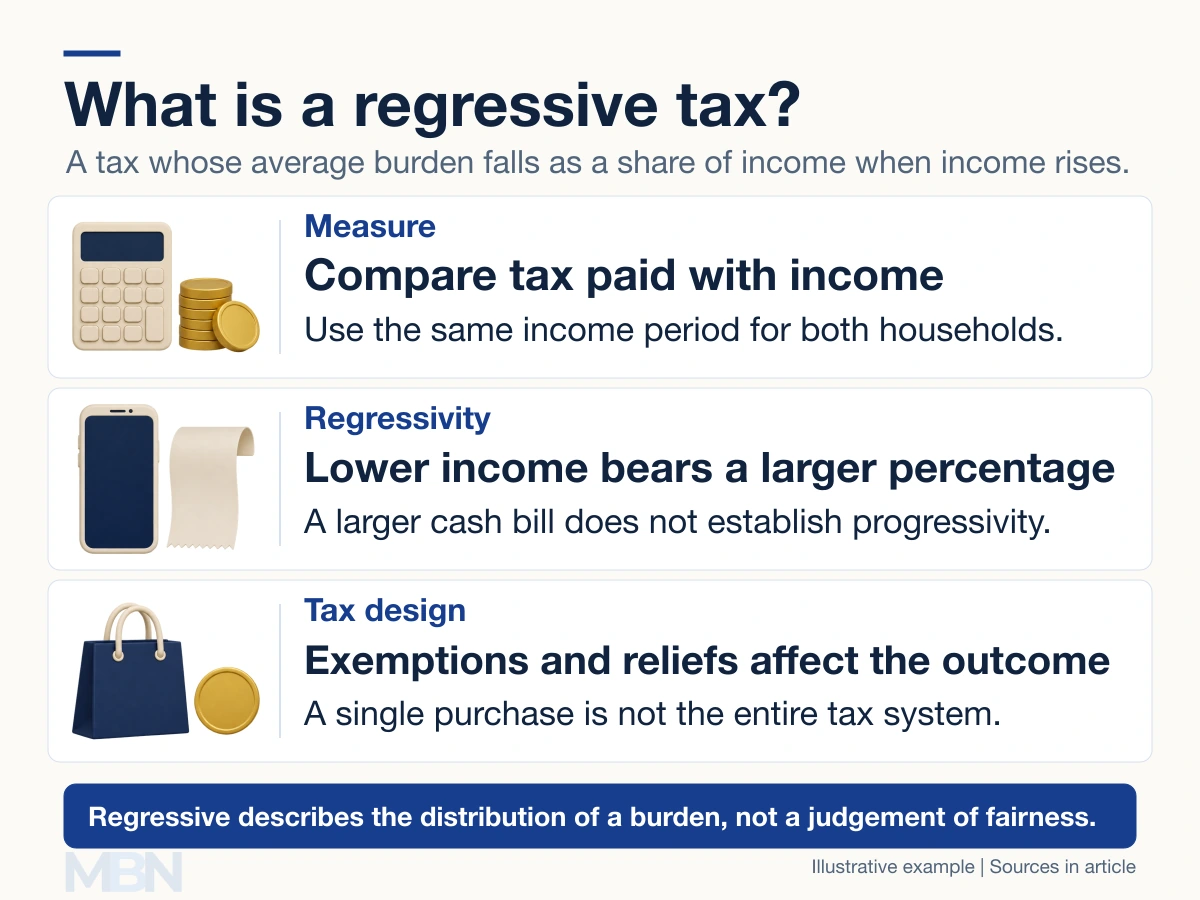
A regressive tax takes a larger share of income from lower-income people than from higher-income people. The comparison concerns the average tax burden relative to income, rather than simply the number of pounds paid.
The IRS educational definitions distinguish three patterns: a regressive burden falls as a share of income, a proportional burden stays constant, and a progressive burden rises.
The calculation behind the definition
Tax burden as a percentage of income equals tax paid divided by income, multiplied by 100. Both amounts must refer to a consistent period.
Suppose two fictional shoppers buy the same item for £100 before tax. An assumed 8% purchase tax adds £8, making the total price £108. One shopper earns £2,000 a month; the other earns £10,000.
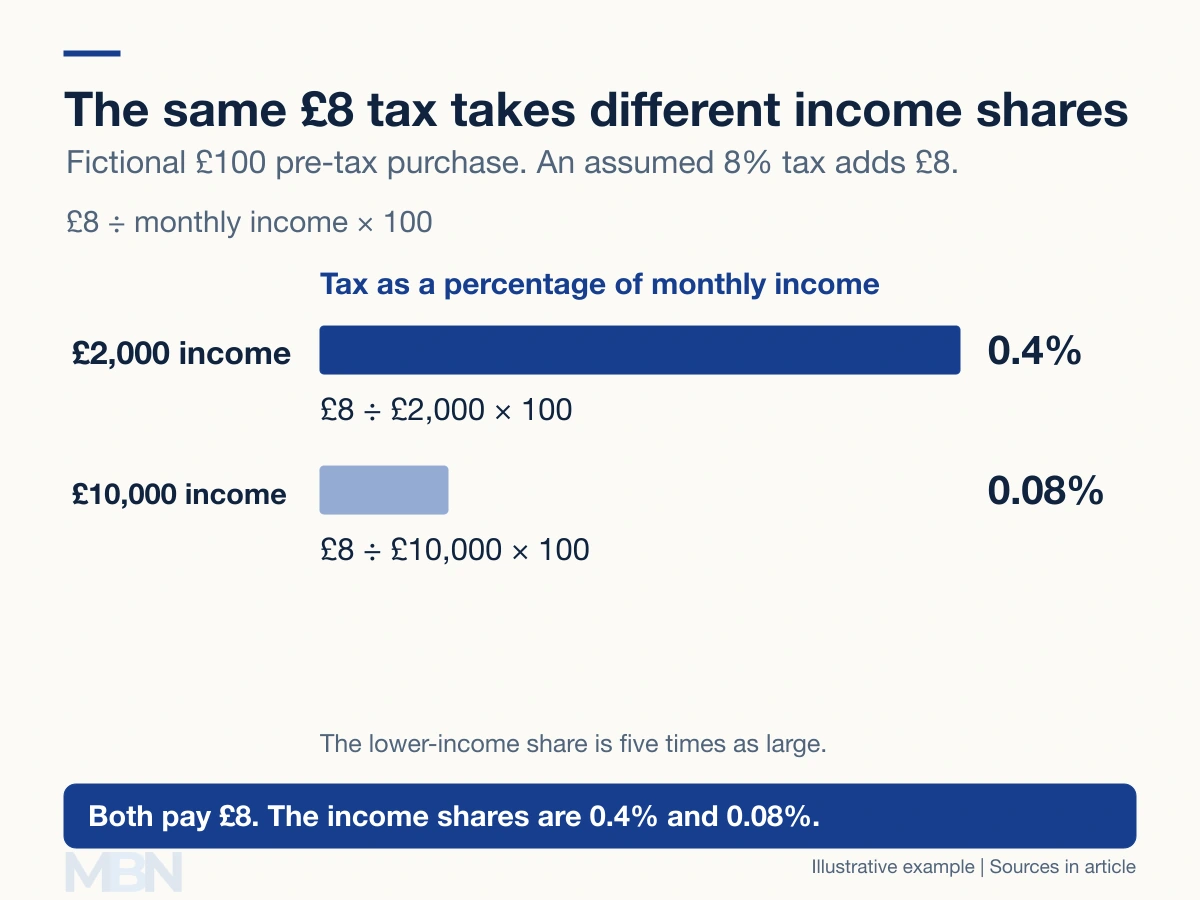
For the first shopper, £8 ÷ £2,000 × 100 equals 0.4%. For the second, £8 ÷ £10,000 × 100 equals 0.08%. Both pay £8, but the lower-income shopper gives up five times the share of monthly income.
Why can a uniform purchase tax be regressive?
A purchase tax can apply the same percentage to the selling price while taking different shares of buyers’ incomes. Iowa State’s economics explanation distinguishes those two denominators.
Actual household burdens depend on what people buy, how much they spend, exemptions and rebates. The single-item example shows the mechanism; it does not measure a household’s annual tax burden.
UK value added tax, or VAT, also taxes consumption, but it is not simply another name for a retail sales tax. HMRC explains how businesses charge VAT and reclaim eligible input VAT through the supply chain. Different rates and exemptions affect its distribution.
Does a larger property-tax bill mean a progressive tax?
No. A higher-value home may attract a larger bill without that bill rising as a percentage of the owner’s income. The property valuation, tax rate, exemptions and household resources all matter.
A Minneapolis Fed discussion of research on taxes and transfers shows why assessing a whole system requires more than comparing individual bills. Its findings also depend on which benefits and public services are included.
How does fairness enter the discussion?
Regressive is a description of distribution. Whether that distribution is fair is a separate judgement involving ability to pay, benefits received and policy aims.
A regressive tax can operate alongside progressive income taxes and targeted transfers. The combined effect may differ from the effect of any one tax. Claims about a country’s current system therefore require a defined measure, period and set of taxes and benefits.
Last checked and updated on November 3, 2026 by the MBN editorial team.