
Retail banking provides everyday banking services to individuals, including deposit accounts, payments and personal borrowing. Some banks also include small-business services within their retail operations, so organizational boundaries vary.
Retail describes the customer market, not a requirement to visit a branch. A bank can provide retail services through branches, cash machines, telephone banking, websites and mobile apps.
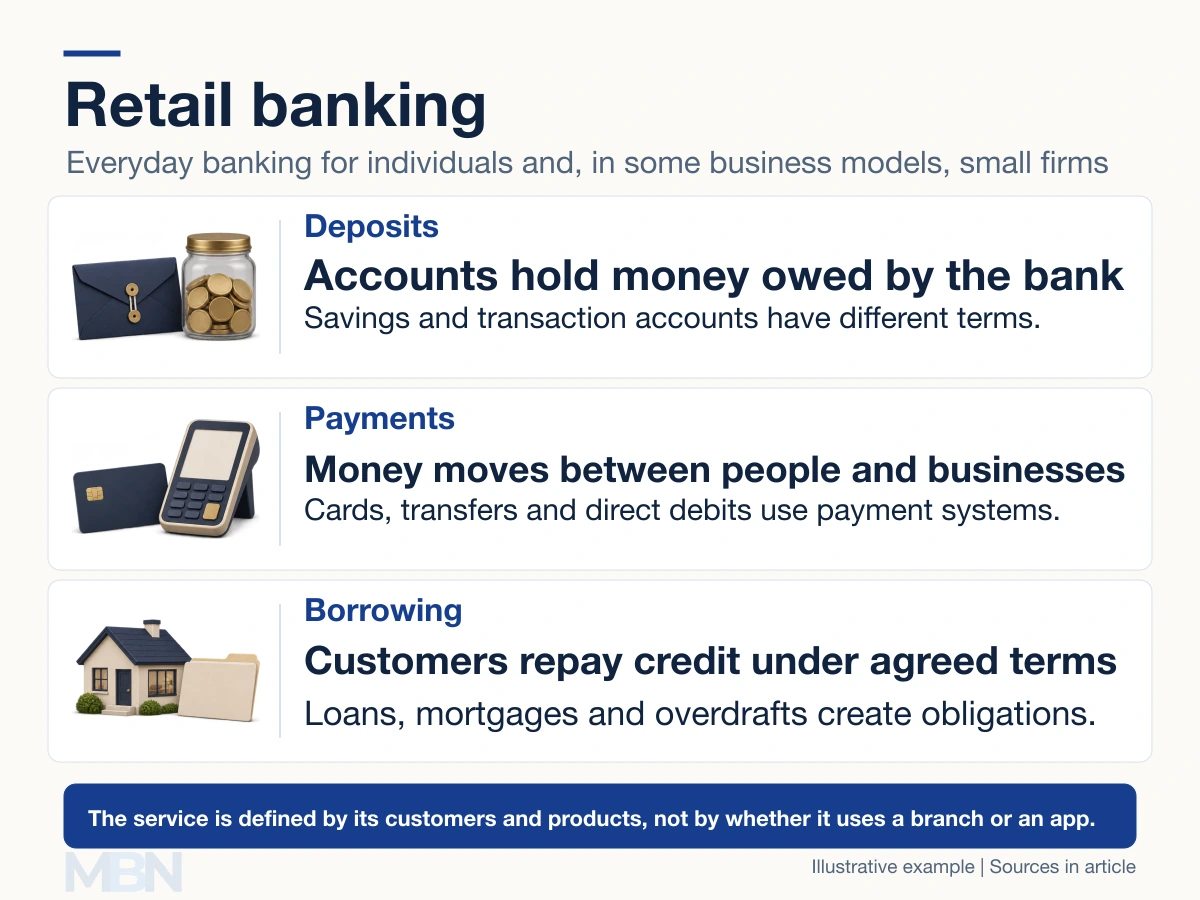
Common retail banking services
Checking accounts, known as current accounts in the UK, support everyday receipts and payments. Savings accounts and fixed-term deposits hold funds under different interest and access conditions. Products and terminology vary by country.
Payment services include transfers, direct debits and cards. A debit card generally uses funds in an account, potentially including an agreed overdraft. A credit card draws on a credit facility, which must be repaid under its terms.
Personal loans, mortgages and overdrafts provide different forms of borrowing. A mortgage is secured against property; an unsecured personal loan does not have that specific collateral arrangement. Fees, rates, repayment schedules and eligibility depend on the product.
Who owes whom?
A bank deposit is a claim on the bank, rather than a separate pile of cash assigned to each customer. The Bank of England explains commercial-bank deposits and how lending can create deposit money.
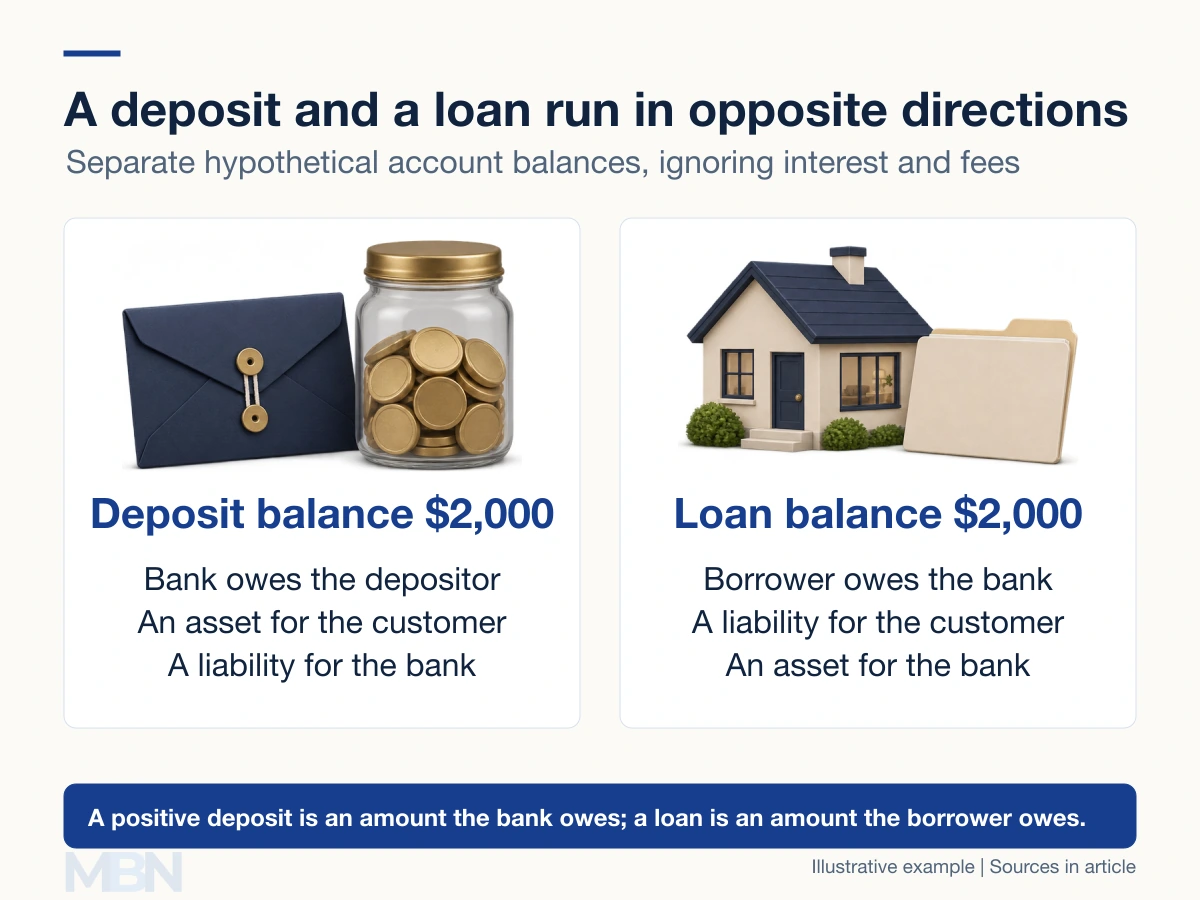
A $2,000 deposit is an asset for the depositor and a liability for the bank. A $2,000 loan is a liability for the borrower and an asset for the bank. The relationships are distinct even if one person holds both products.
Banks must manage credit losses, funding, liquidity and capital. Interest on loans and other assets, interest paid on funding, fees and operating costs all affect results. Retail banking is not a guarantee of stable profit.
Deposit protection has limits
In the United States, FDIC insurance generally covers up to $250,000 per depositor, per insured bank, per account ownership category. Separate accounts in the same category at one bank are combined for that limit. Non-deposit investments are not insured merely because a bank sells them.
In the UK, FSCS deposit protection is generally up to £120,000 per eligible person, per authorized bank, building society or credit union, following the change effective December 1, 2025. Brands sharing one banking authorization can share a limit; special rules apply to some temporary high balances.
These are jurisdiction-specific examples, checked on the date below. Coverage depends on the institution, product, eligibility and applicable scheme; it is not one worldwide guarantee.
A banking app is not always a bank
A licensed bank can operate mainly online. A financial-technology company may instead provide an interface to services delivered by a partner bank. The provider shown on a phone screen and the institution holding a deposit can therefore differ.
The FDIC explains that third-party app funds need to reach an insured bank and meet relevant conditions for pass-through coverage. Deposit insurance protects against an insured bank’s failure, not automatically the failure of an app provider or access problems at a nonbank.
Related banking activities
Wholesale banking generally serves larger institutional and corporate customers. Investment banking includes capital raising and transaction advice; its clients are not limited to companies. A group may conduct several activities through different divisions or legal entities.
Private banking offers tailored services for wealthier clients, but minimum asset requirements differ across providers and countries. There is no universal $500,000 threshold defining it.
Branch use and staffing differ across markets, customer groups and banks. Digital channels have changed how services are delivered, but that does not establish that all branches lack tellers or that every banking task is available online.
Last checked and updated on November 11, 2026 by the MBN editorial team.