
Online banking means accessing banking services through the internet. Customers can view accounts, make payments and carry out other supported tasks through a bank’s website or mobile service without visiting a branch.
It describes how a service is delivered, rather than a separate kind of money or bank charter. A bank with branches can offer online banking, while an online-only bank mainly serves customers remotely.
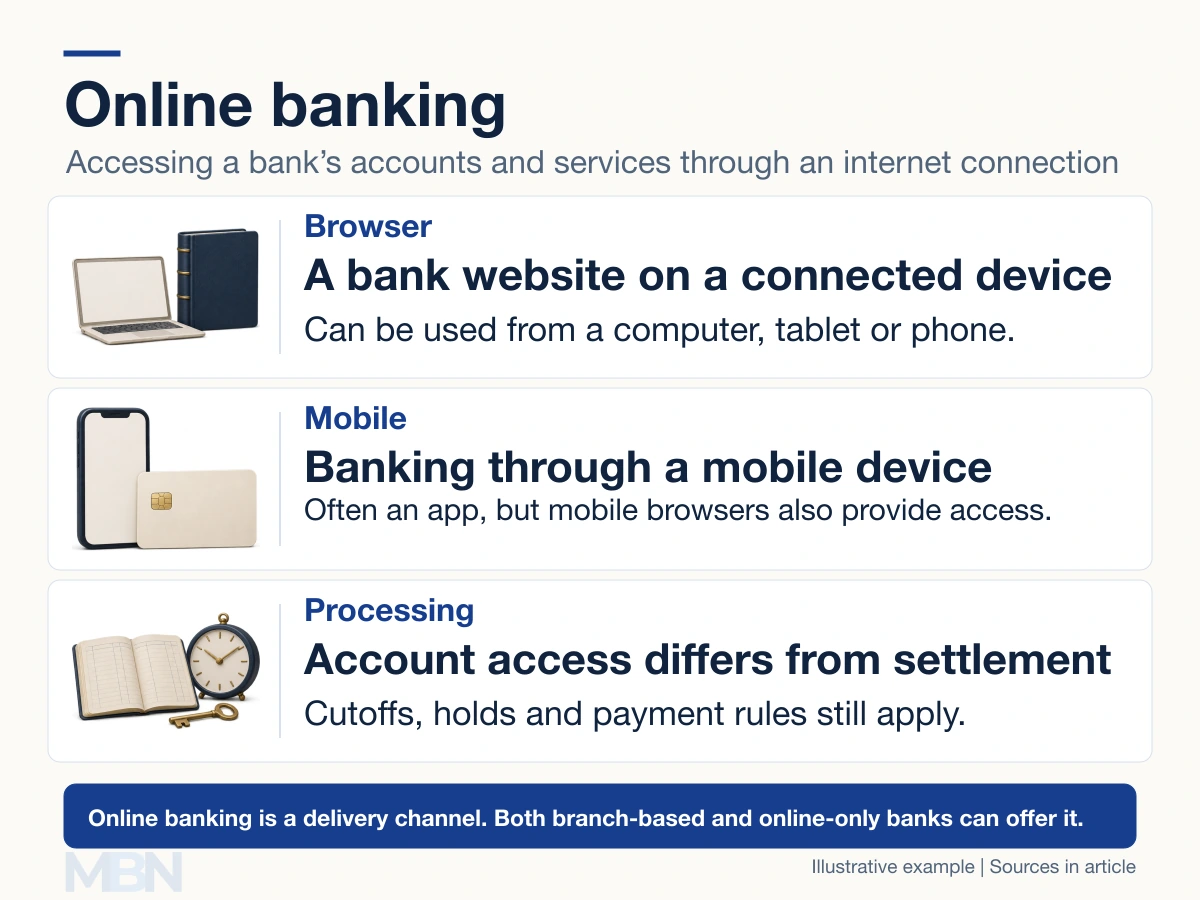
Internet banking and mobile banking
Internet banking commonly refers to access through a web browser. Mobile banking means banking on a phone or tablet, often through a dedicated app. A mobile browser can also access a bank website, so the terms overlap rather than forming completely separate systems.
The FDIC’s digital-banking explanation describes services such as checking balances, transferring money and depositing checks remotely where available. Banks may also provide bill payments, statements, alerts, card controls and applications for financial products.
Features are not universal. Cash deposits, identification checks, larger transfers and some account changes can require additional steps. Access is often available outside branch hours, but outages, maintenance, connectivity and support hours can still limit service.
What account balances mean
A displayed balance can reflect different stages of processing. Posted transactions have been recorded on the account. Pending transactions have not completed posting, while deposit holds or card authorizations can restrict the amount immediately available.
The OCC defines available balance by reference to holds, uncollected funds and restrictions. Suppose an account has a $1,000 posted balance and one $150 card hold already reflected in availability. With no other adjustments, the available balance is $850.
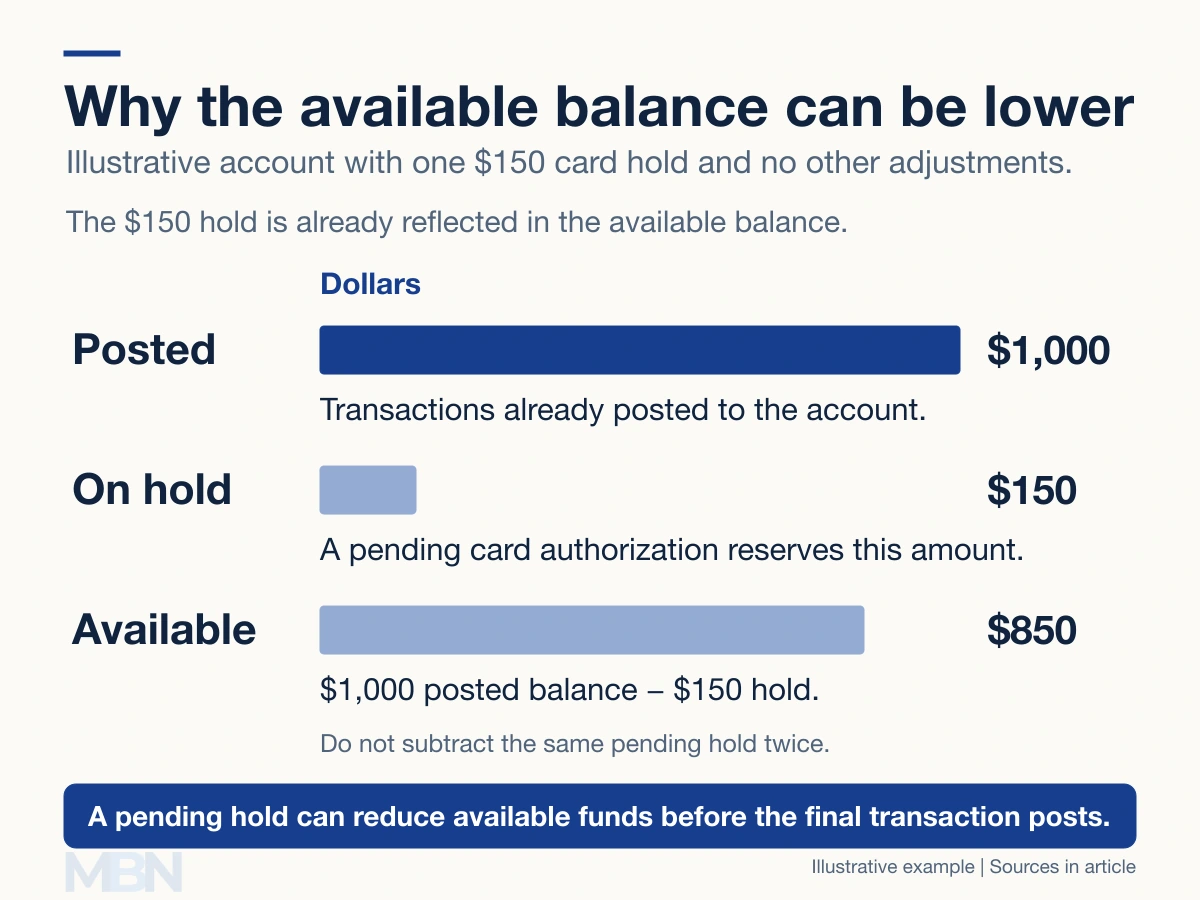
The $150 hold should not be subtracted twice. However, a check not yet presented or another commitment may not appear in the displayed figure. The OCC explains that processing timing can affect balances and that the account agreement governs the bank’s policies.
Submitting a transfer online is also different from completing it. Payment-system rules, cutoff times, checks and recipient-bank processing can affect when funds arrive.
Authentication and account protection
Authentication establishes who is accessing an account. A bank may combine a password or passkey with device checks, biometrics or a one-time code. The FTC explains two-factor authentication as using an additional factor rather than relying on a password alone.
These controls reduce particular risks but do not eliminate account takeover or deceptive payment requests. The FTC warns that impostors seek verification codes to gain access. The distinction is between entering a code in the genuine bank’s process and giving it to an unsolicited caller.
The provider matters as much as the app
A third-party financial app is not automatically a bank. The FDIC distinguishes bank deposits from nonbank app arrangements. US deposit-insurance eligibility depends on the insured bank, account ownership and applicable conditions, rather than whether an app looks like a banking service.
Deposit insurance addresses covered bank failures; it does not insure every scam, investment loss or interruption at a technology provider. Understanding online banking therefore includes both the access channel and the institution holding the underlying account.
Last checked and updated on November 11, 2026 by the MBN editorial team.