
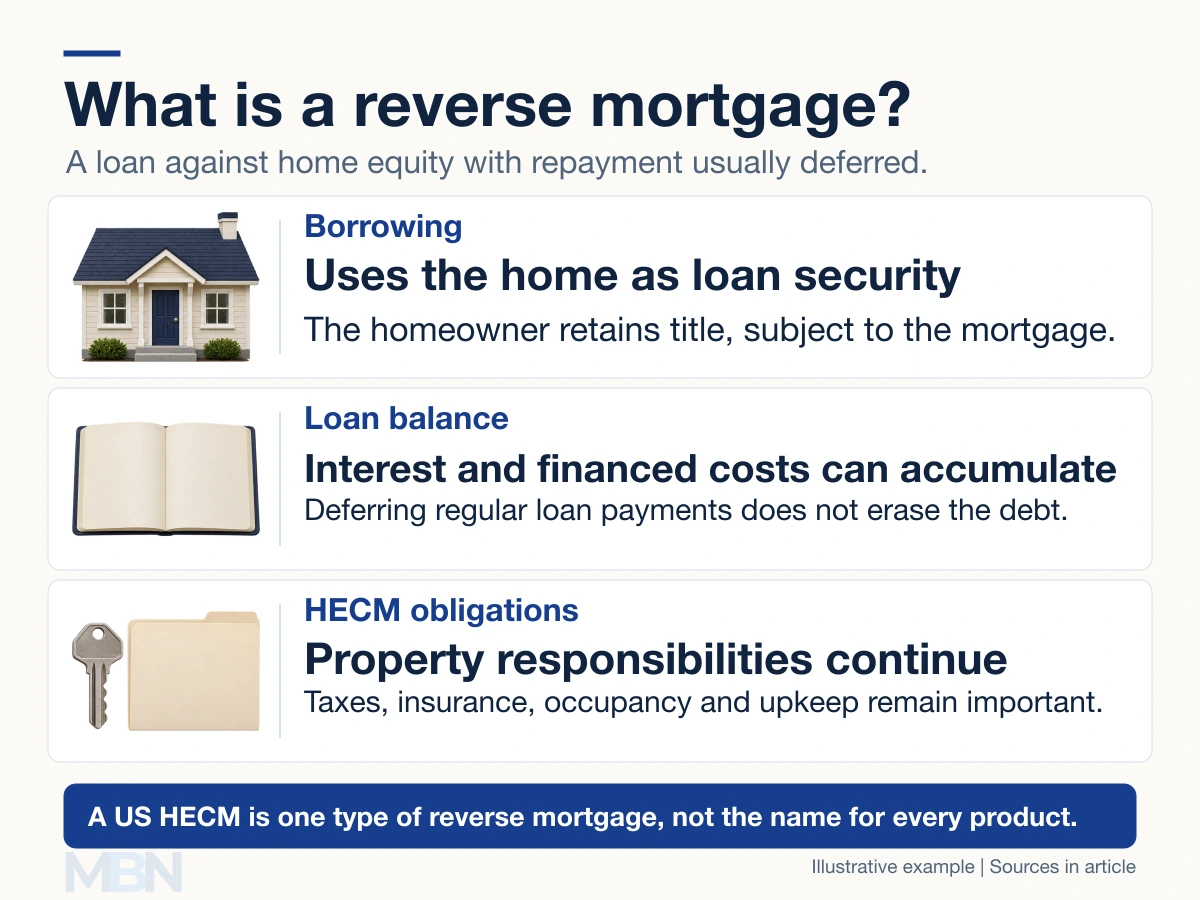
A reverse mortgage lets a homeowner borrow against home equity, usually without making regular monthly payments toward the loan balance. Interest and financed costs can be added to the debt instead.
A Home Equity Conversion Mortgage, or HECM, is the US Federal Housing Administration-insured version. HUD distinguishes that program from other reverse-mortgage products. HECM rules should not be treated as universal terms for every private product or country.
Who can use a US HECM?
The CFPB’s current HECM explanation specifies borrowers aged 62 or older. Other eligibility conditions apply. This is not an automatic entitlement to borrow the home’s full equity.
HUD says the available amount depends on factors including the youngest borrower’s or eligible non-borrowing spouse’s age, interest rates and the relevant property value or program limit. Existing mortgage obligations and costs also affect the cash available.
How does the debt grow?
The borrower keeps title to the home, but the mortgage remains secured against it. A line of credit, lump sum or scheduled payments may be available depending on the product and loan terms.
If interest and fees are financed rather than paid, they increase the balance. With the property value unchanged, a higher balance leaves less home equity.
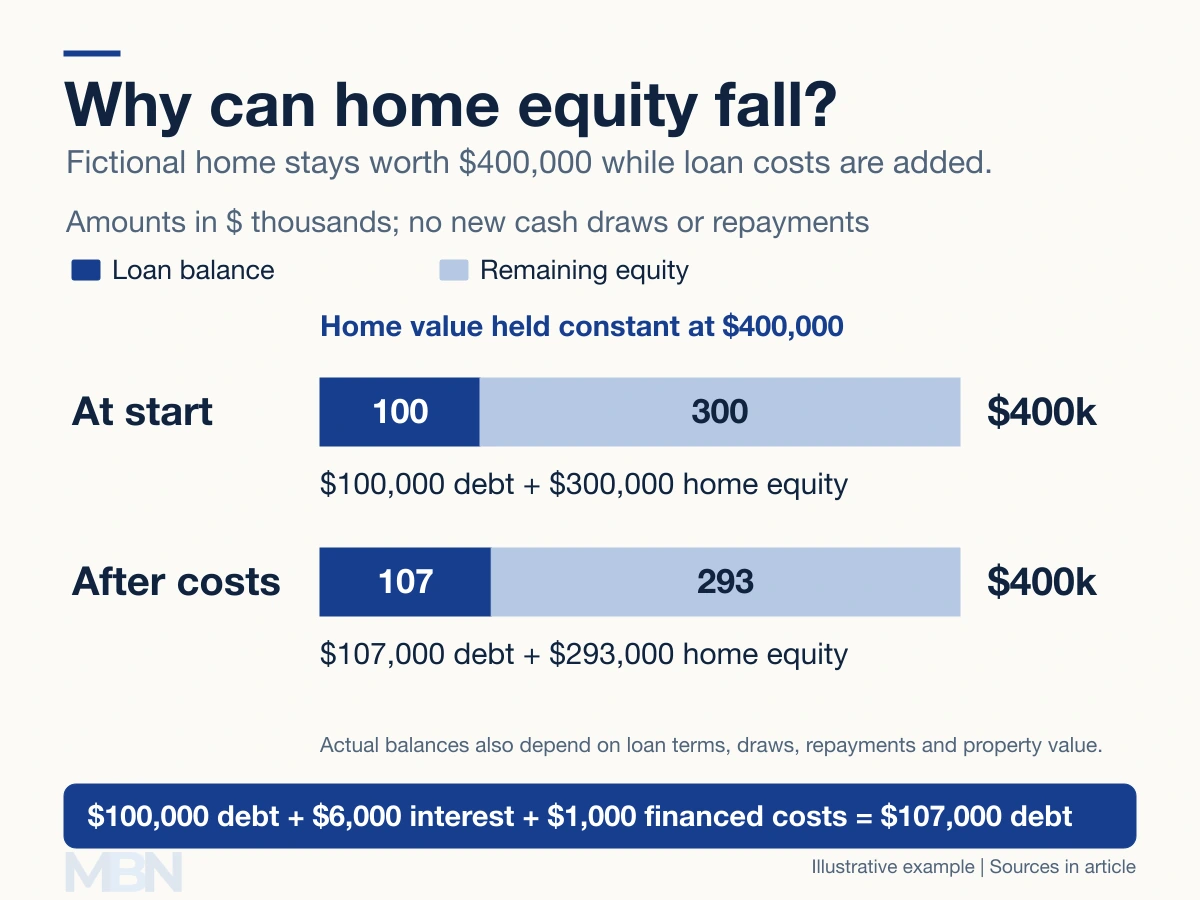
Our fictional example starts with $100,000 of debt on a $400,000 home. Adding an assumed $6,000 of interest and $1,000 of financed costs raises debt to $107,000 and reduces equity from $300,000 to $293,000. These amounts are illustrative, not an offer or a current rate.
Does deferred repayment mean no housing payments?
No. HECM obligations include property taxes, homeowners insurance, principal-residence occupancy and upkeep. Failure to meet loan conditions can cause default and foreclosure, even while a borrower is living in the home.
Repayment events include selling, ceasing to use the property as the principal residence, or death, subject to applicable protections. Absence for medical care and surviving-spouse status require more specific treatment than simply saying the loan ends whenever someone leaves.
What happens to a surviving spouse or heirs?
The CFPB distinguishes a surviving co-borrower from an eligible non-borrowing spouse. A co-borrower can generally continue under the loan while meeting its obligations. An eligible non-borrowing spouse may qualify for deferred repayment but does not receive further loan advances.
Heirs may have options to repay the debt, sell the property or transfer it to the lender. A sale is not the automatic outcome in every case.
HECM non-recourse protections can limit repayment where the debt exceeds the home’s value. Appraisal, sale and retention rules matter, and those protections should not be assumed to apply identically to a private reverse mortgage.
Last checked and updated on November 3, 2026 by the MBN editorial team.