
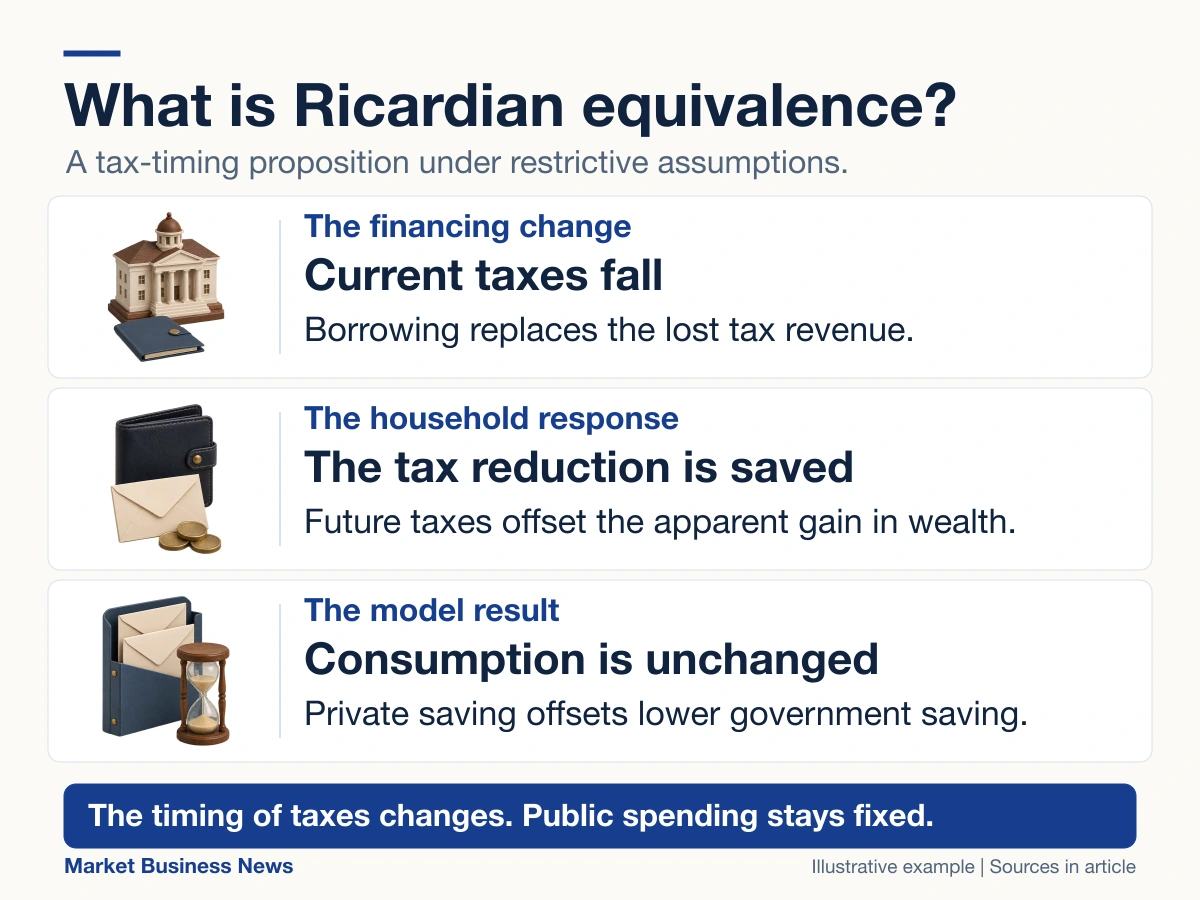
Ricardian equivalence is the proposition that replacing current taxes with government borrowing leaves private consumption unchanged, under particular assumptions. Households save the tax reduction because they expect future taxes to cover the debt.
The proposition holds the government’s spending plans fixed. It concerns when taxes are paid and how spending is financed, rather than the effect of every possible change in public spending or taxation.
Why a tax cut might leave consumption unchanged
A government can collect taxes now or borrow and collect taxes later to meet the resulting debt obligations. In the Ricardian case, households recognize that the second option shifts their tax burden through time without making them wealthier overall.
They therefore save the money released by the current tax cut. The increase in private saving offsets the fall in government saving, leaving national saving unchanged in the model. The Federal Reserve’s discussion of government debt explains this link between the government’s budget constraint and household consumption.
A government bond remains an asset for its owner. The proposition concerns whether the private sector gains net wealth after allowing for the future taxes associated with that debt.
A hypothetical tax-timing example
Suppose a household’s tax bill is reduced by US$600 today. Government spending stays the same, and borrowing replaces the lost tax revenue. In this simplified one-year example, both the government and household face a 5% interest rate.
Assume the household knows it will owe an extra US$630 in tax next year to cover the principal and interest. Saving the US$600 at 5% produces exactly US$630. Under the proposition’s assumptions, the household can meet that future bill without changing its consumption in either year.
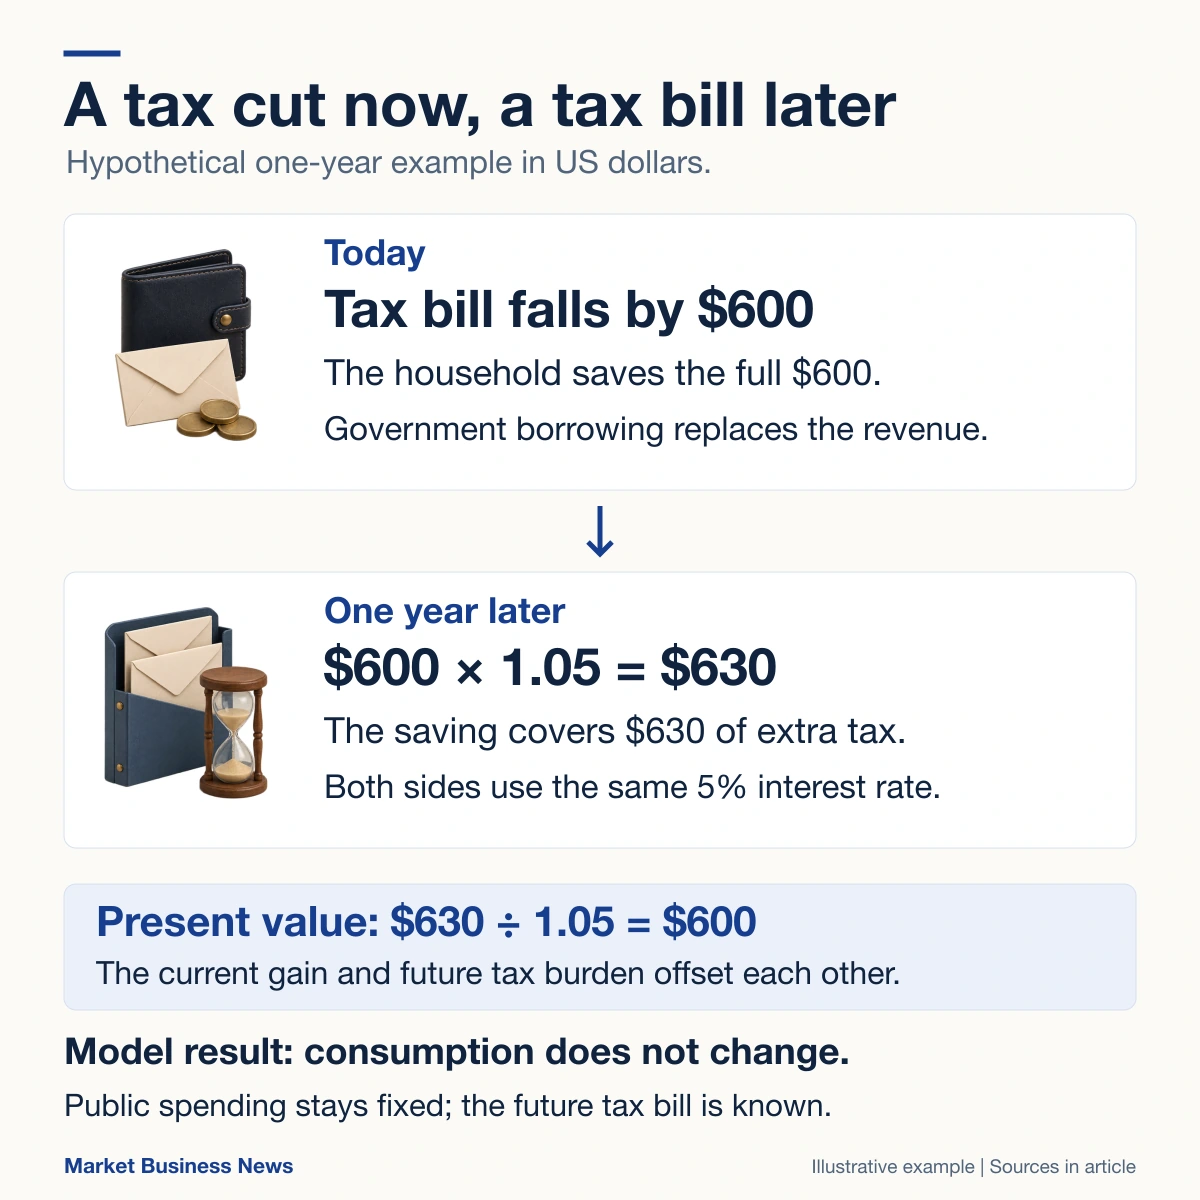
The future US$630 obligation has a present value of US$600: US$630 divided by 1.05. Present value expresses a future amount in today’s money using an assumed discount rate. The tax saving and future liability offset each other in this example.
The assumptions behind the result
A standard benchmark relies on several conditions, outlined in the IMF research paper Modeling and Testing Ricardian Equivalence:
- Government spending follows the same path under both financing methods.
- Households anticipate the future taxes and plan far enough ahead to take them into account.
- Borrowing and saving are available on suitable terms, without a binding restriction on household borrowing.
- The tax changes do not alter incentives to work, invest or produce. Economists often represent this with lump-sum taxes, amounts independent of those decisions.
- The households making today’s decisions bear, or care about the people who bear, the future tax burden.
Links between generations matter because government debt can outlast an individual taxpayer. In models with family transfers, parents can save more for children who will face the later taxes.
Why actual spending can respond differently
A household unable to borrow may have wanted to spend more before the tax cut but lacked the cash. Receiving the money can allow it to increase purchases even if it expects a later tax bill. Uncertainty about future policy, different planning horizons and changes in who pays taxes can also alter the result.
Research continues to test how closely the benchmark describes household behavior. In a March 2026 Kansas City Fed working paper, Jonathan J. Adams and Christian Matthes estimate that households take account of only part of their future taxes. This is a result from the authors’ model and estimation method, rather than a universal household response.
Ricardian equivalence is therefore a useful benchmark for analyzing debt-financed tax changes. Whether a particular policy raises consumption depends on its design, household circumstances and the evidence. Changing public spending raises a different question from changing its financing while keeping it fixed.
Where the idea came from
The name refers to ideas discussed by David Ricardo. Robert J. Barro developed an influential modern analysis in his 1974 paper Are Government Bonds Net Wealth?, published in the Journal of Political Economy. The continuing debate concerns both the assumptions and how well the resulting predictions fit actual economies.
Last checked and updated on November 2, 2026 by the MBN editorial team.