
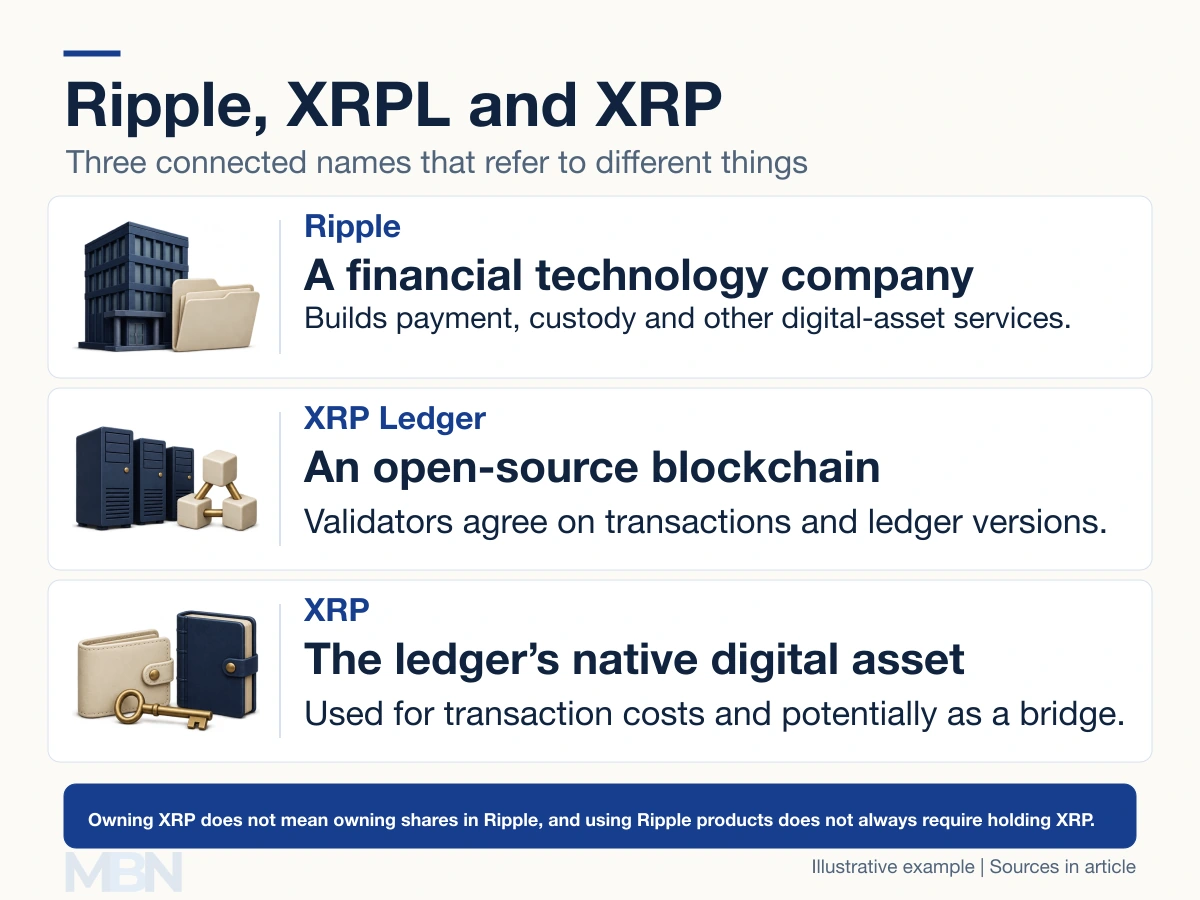
Ripple is a financial technology company that develops payment and digital-asset services. It is closely associated with the XRP Ledger, an open-source blockchain, and XRP, that ledger’s native digital asset. The company, network and asset are different things.
Calling the cryptocurrency “Ripple” can obscure what a transaction or investment actually involves. The XRP Ledger’s own overview distinguishes Ripple from XRP; holding XRP does not confer ownership of Ripple shares.
How the XRP Ledger works
The XRP Ledger records accounts, transactions and other objects in successive ledger versions. Its consensus protocol uses validators and trust-list relationships to agree on which transactions enter the next validated ledger and in what order.
It does not use Bitcoin-style proof-of-work mining. Validators do not receive newly mined XRP for validating transactions. The original supply was created when the network began in 2012.
Transaction costs are paid in XRP and destroyed rather than paid to a validator. The cost helps discourage spam; it can vary with transaction type and network conditions. Accounts and some ledger objects also have reserve requirements.
There is no rule that every XRP payment requires a bank and a market maker. Users can send XRP between ledger accounts. Cross-currency routes, by contrast, depend on available offers, liquidity pools or service providers.
What Ripple’s payment services do
Ripple describes its cross-border payment product as connecting fiat and digital-asset payment routes. Its current product documentation includes stablecoin collection, conversion and payout, rather than only the older xCurrent and xVia product descriptions.
The company says customers need not directly hold cryptoassets for some payment services, because Ripple can manage the conversion. Product terms, destination coverage and regulatory eligibility still determine what a customer can use.
XRP can act as a bridge between currencies. Suppose $1,000 buys 500 XRP at $2 each. If those 500 XRP are sold for €1.80 each, the recipient-side conversion produces €900 before costs.
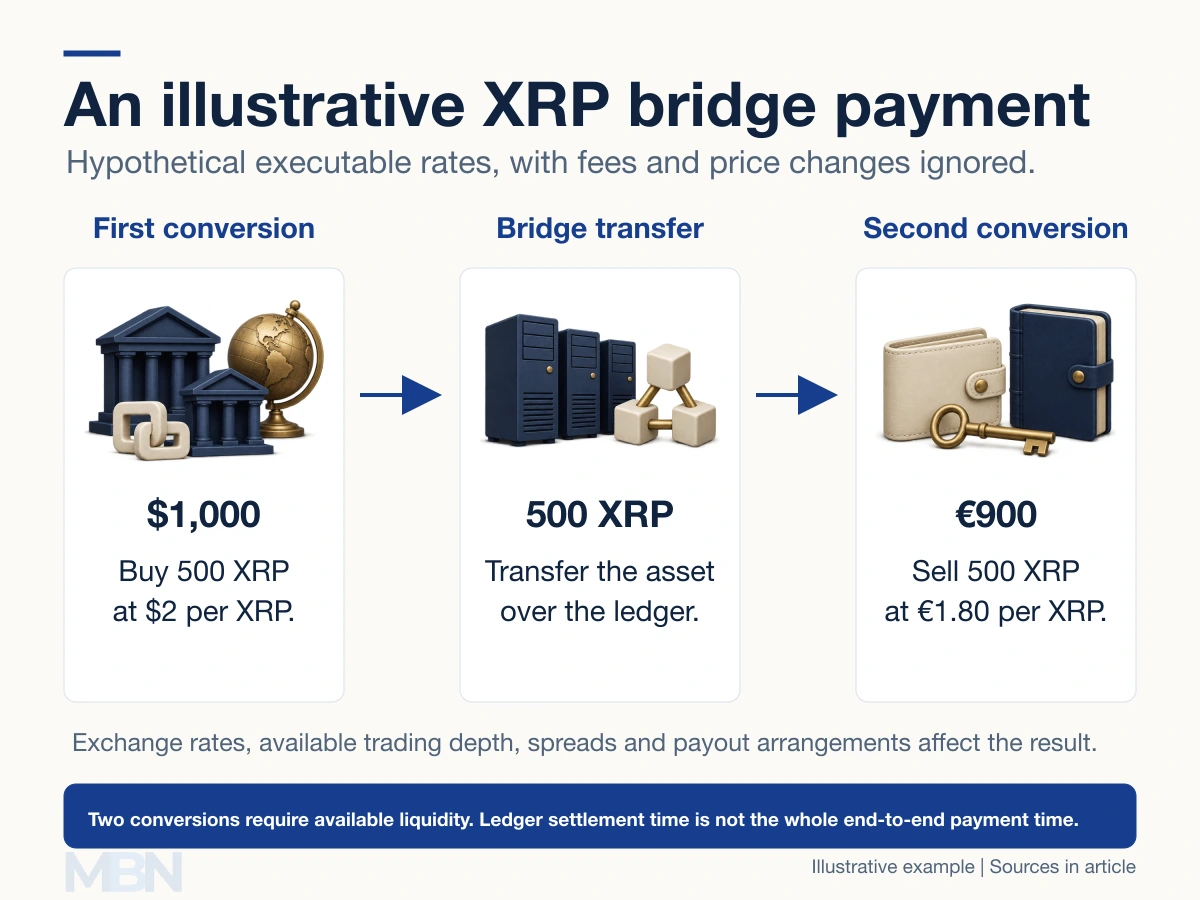
That example requires enough liquidity at both assumed prices. A spread, fee or price movement can change the amount. A fast validated ledger transfer does not eliminate bank processing, compliance, foreign-exchange or local payout requirements.
XRP, stablecoins and risk
XRP is not a dollar stablecoin and does not promise redemption for a fixed dollar amount. Ripple also offers Ripple USD, or RLUSD, a separate dollar-referenced stablecoin. The issuer describes RLUSD as reserve-backed and redeemable under its arrangements. That does not make XRP and RLUSD interchangeable.
Public ledger records also mean that using an address is not a guarantee of anonymity. Cryptographic authorization does not prevent scams, lost keys, service-provider failures or market losses.
The ledger supports defined functions such as payments, asset issuance and escrow, but it should not be described as containing a universal set of fully automated smart contracts that eliminates intermediaries and risk. The relevant transaction rules, application and legal arrangements determine what a particular service actually does.
Last checked and updated on November 11, 2026 by the MBN editorial team.