
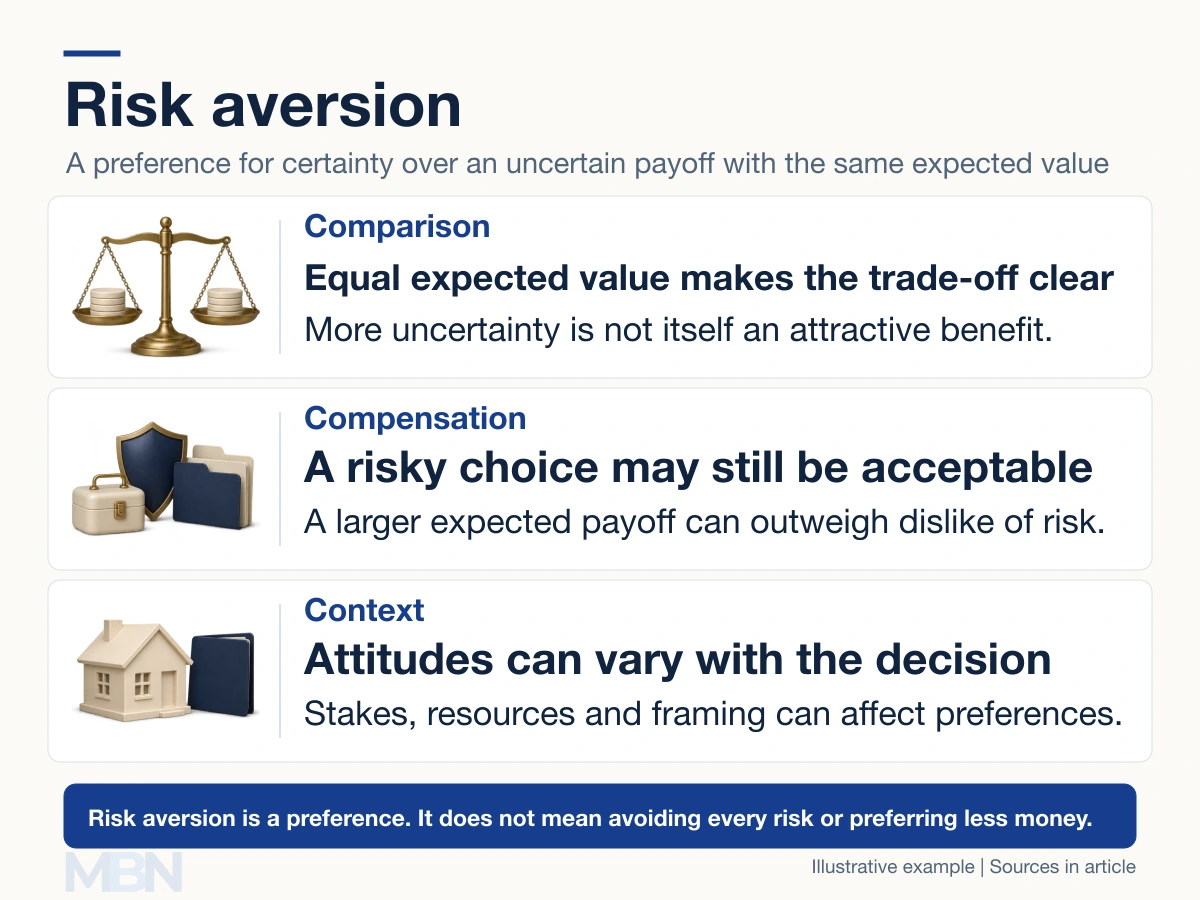
Risk-averse describes someone who prefers a certain payoff to an uncertain one with the same expected value. In everyday language, it means being reluctant to take risks. In economics, the comparison is more precise: it separates the amount expected from the uncertainty surrounding it.
A risk-averse person does not necessarily avoid every uncertain opportunity or prefer a lower return. A sufficiently attractive expected reward can make accepting risk worthwhile.
A simple example with stated probabilities
Suppose a person can receive £50 for certain or take a 50% chance of £100 and a 50% chance of nothing. There is no entry fee. The gamble’s expected value is 0.5 × £100 + 0.5 × £0 = £50.
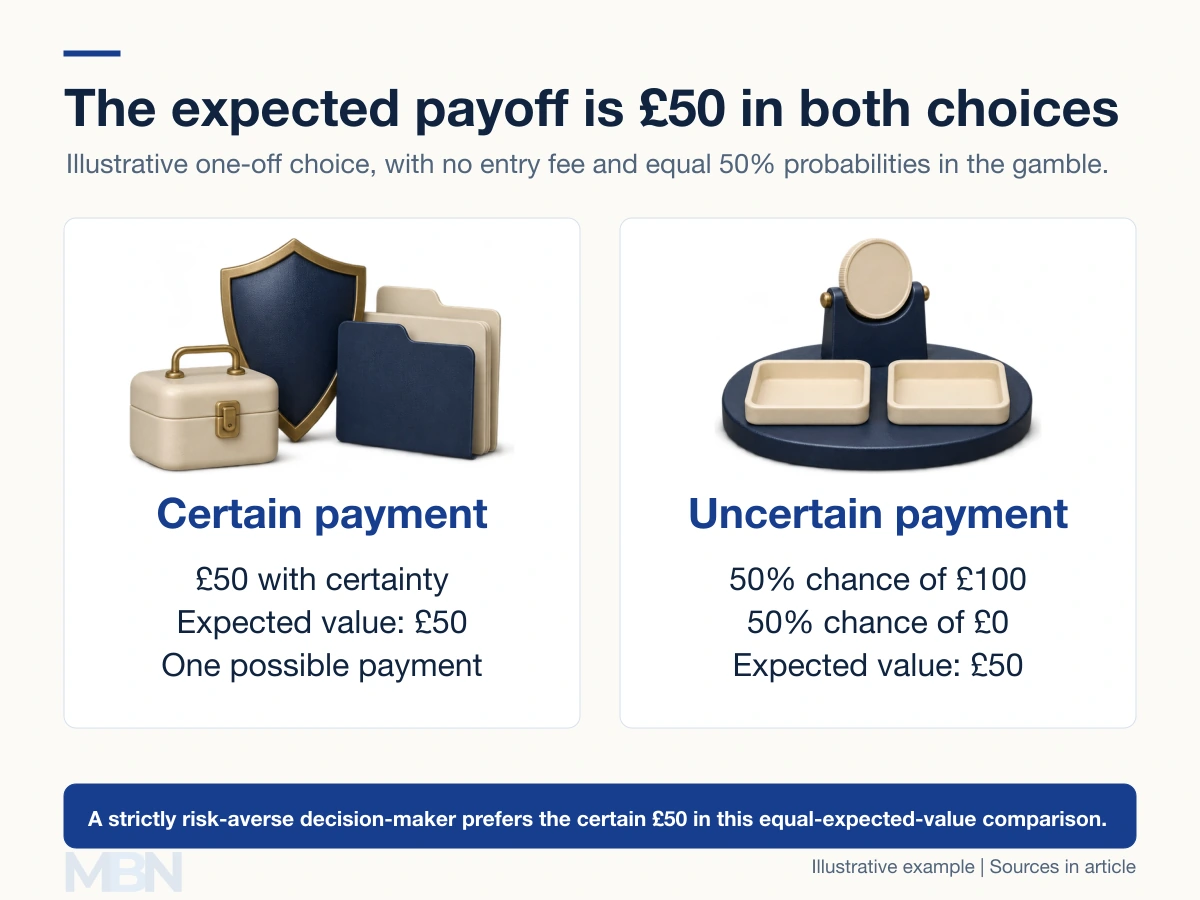
A strictly risk-averse person prefers the certain £50. A risk-neutral person is indifferent on this monetary comparison, while a risk-seeking person prefers the gamble. These definitions assume the outcomes, probabilities and other relevant conditions are understood.
The EconPort handbook explains these three attitudes through expected utility. Utility represents how desirable outcomes are to the decision-maker, rather than the number of pounds alone. In expected-utility theory, a concave utility function captures risk aversion.
Certainty equivalents and risk premiums
A certainty equivalent is the guaranteed amount someone considers equally attractive to a gamble. Suppose this person views £40 guaranteed as equivalent to the £100-or-nothing gamble. The gamble has £50 expected value, so the preference-based risk premium is £50 − £40 = £10.
This does not mean £40 is the expected payment or that every guaranteed offer will be accepted. An offer of £30 is below that person’s certainty equivalent. NYU Stern’s discussion explains certainty equivalents and risk premiums.
The same term, risk premium, is also used in investing for expected return above a risk-free benchmark. That return comparison should be distinguished from this monetary measure of an individual’s preferences.
Risk aversion and investment choices
A risk-averse investor may accept a lower expected return in exchange for less risk, but the available alternatives matter. A quoted high yield is not the same as a guaranteed high return. A risky investment can lose money.
Risk tolerance in practical investing includes both willingness and ability to bear losses. Income needs, liabilities, time horizon and available resources influence the decision. The SEC explains these considerations in its asset-allocation guidance.
No product label establishes suitability. An equity index fund can be diversified and still fall sharply. Bonds can carry default, interest-rate and inflation risk, as the SEC’s bond explanation describes. A bond ladder spreads maturity dates but does not remove every risk.
Insurance and everyday decisions
Insurance exchanges an uncertain covered loss for a known premium, subject to terms such as deductibles and exclusions. A risk-averse household may value that reduction in uncertainty even when the premium exceeds the expected claim.
A used-car buyer might similarly value a reliable warranty. The comparison depends on its cost, coverage and enforceability. Risk aversion alone does not mean everyone must choose a dealer or that a warranty eliminates uncertainty.
Risk aversion can depend on context
A person may welcome uncertainty in a sport but dislike it when housing or savings are at stake. Preferences can also vary with the size of the potential loss and the resources available to absorb it.
Risk aversion differs from loss aversion, which concerns the relative weight given to losses and gains around a reference point. Kahneman and Tversky’s prospect-theory research examines framing and differing choices over gains and losses. Neither concept is a judgement about intelligence, courage or willingness to try new products.
Last checked and updated on November 11, 2026 by the MBN editorial team.