
Risk management is the structured process of identifying, assessing and responding to uncertainty that can affect objectives. It helps an organization decide which exposures to take, which to change and how to monitor the results. It does not eliminate every possible loss.
Risks can arise from credit defaults, market prices, operational failures, cyber incidents, legal obligations or disrupted supplies. The relevant question starts with the objective: what outcome is being pursued, and what could cause it to differ from expectations?
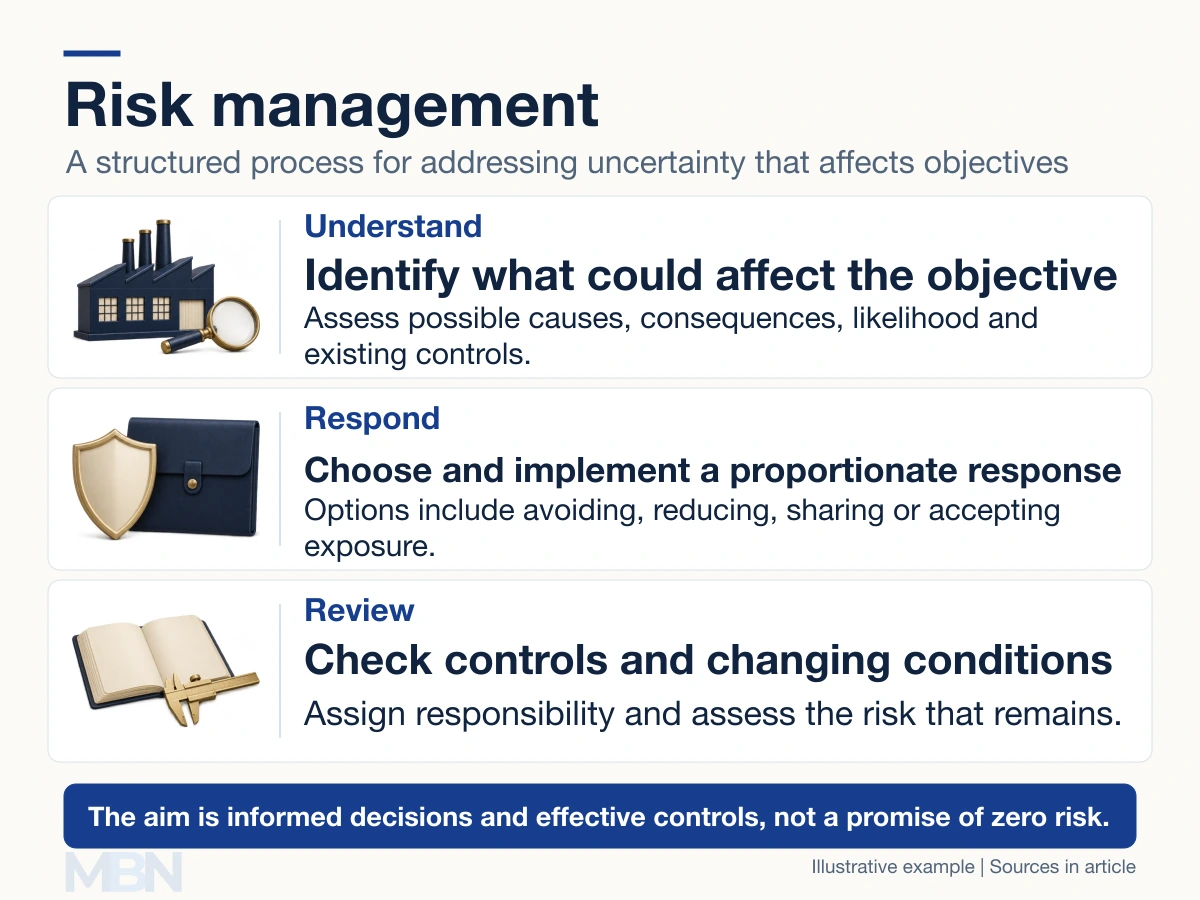
What the process involves
The UK government’s Orange Book describes risk management as part of decision-making. The process includes establishing context, identifying risks, analyzing and evaluating them, selecting responses, and monitoring the outcome. Communication and reporting continue throughout.
Likelihood describes how probable an event is; consequence describes its effect. Assessments should consider existing controls and the quality of the evidence. A numerical score can help organize discussion but does not make a weak estimate precise.
Risk appetite describes the amount and type of risk an organization is willing to take in pursuing objectives. It informs limits and escalation decisions. Residual risk is the exposure remaining after controls or other responses.
Different ways to respond
Avoidance means not undertaking an activity that creates an unacceptable exposure. Reduction changes its likelihood or consequences, such as adding backup systems. Acceptance means deliberately retaining an exposure, with responsibility and monitoring.
Insurance can share specified financial consequences, but exclusions, deductibles and coverage limits remain. A hedge offsets a particular financial exposure and can introduce costs or other risks. Diversification spreads exposure but does not prevent losses shared across holdings.
A worked control example
Suppose a disruption has a 10% annual probability and would cost $50,000 if it occurred. In this simplified two-outcome model, expected loss is 10% multiplied by $50,000, or $5,000 per year.
A proposed control costs $1,000 annually and reduces the assumed probability to 3%, leaving the event’s loss unchanged. Expected loss falls to $1,500. The $3,500 expected-loss reduction exceeds the control cost by $2,500 under these assumptions.
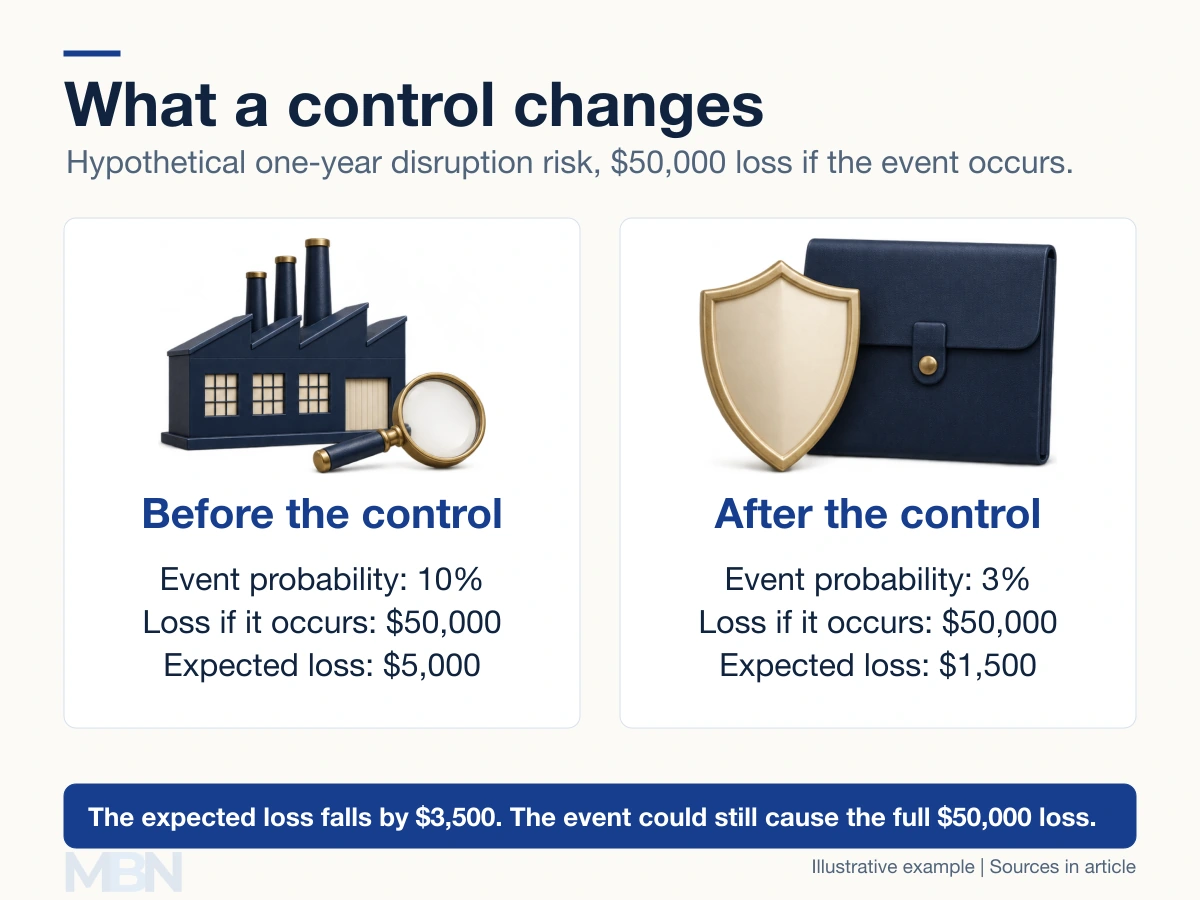
That is an average modeled benefit, not guaranteed annual savings. The business can still suffer the full event loss. Rare severe outcomes, legal requirements, multiple incidents and uncertainty in the estimates can change the decision.
The current ISO framework
ISO 31000:2018 replaced the 2009 edition. It provides principles, a framework and a process for risk management. ISO’s overview emphasizes integration into the organization and senior management’s involvement.
In this framework, risk concerns uncertainty’s effect on objectives, which can be positive or negative. Treating every negative event as risk and every positive event as an entirely separate category misses that broader definition.
Risk management as a profession
Risk professionals work in finance, operations, engineering, insurance and other fields. They may analyze exposures, assess controls, run scenarios, set reporting thresholds or advise decision-makers. Responsibility for business decisions remains with the relevant owners and governing bodies.
CFA Institute describes different entry routes into financial-risk roles. Education, experience and certification requirements vary by employer and specialization. The BLS describes a bachelor’s degree and related experience as typical for financial managers, but neither an MBA nor a particular certification is a universal requirement for every risk role.
Last checked and updated on November 11, 2026 by the MBN editorial team.