
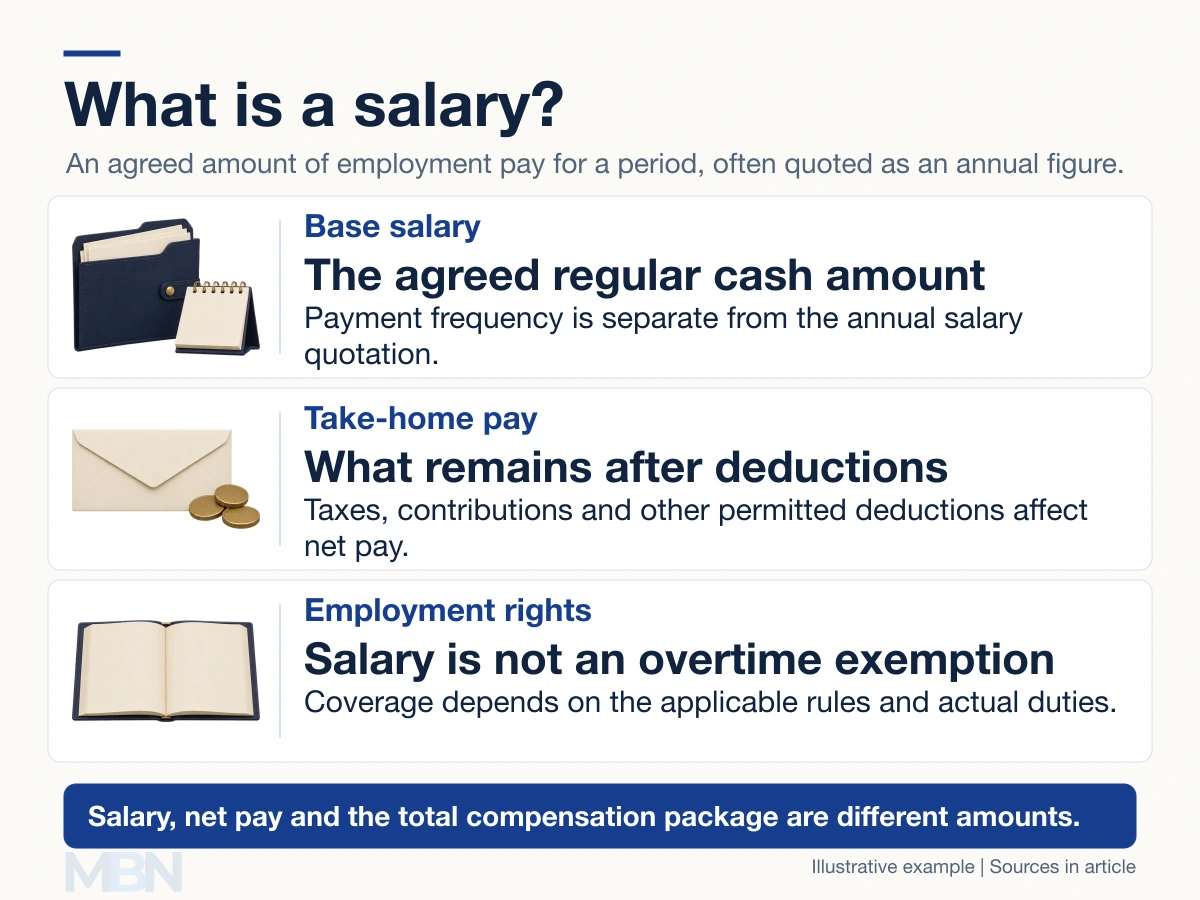
A salary is an agreed amount of pay for employment over a period, often quoted annually and paid in regular installments. The annual quotation, payment frequency and amount received after deductions are separate things.
A $60,000 annual base salary does not mean the employee receives $60,000 in one payment or takes home that entire amount. The contract, payroll schedule, deductions and applicable law determine how payment works.
Annual salary and payment frequency
Consider a fictional $60,000 gross annual base salary paid in equal installments over a complete year. Monthly payments would be $5,000 each. Twice-monthly payments would be $2,500 each, making 24 payments annually.
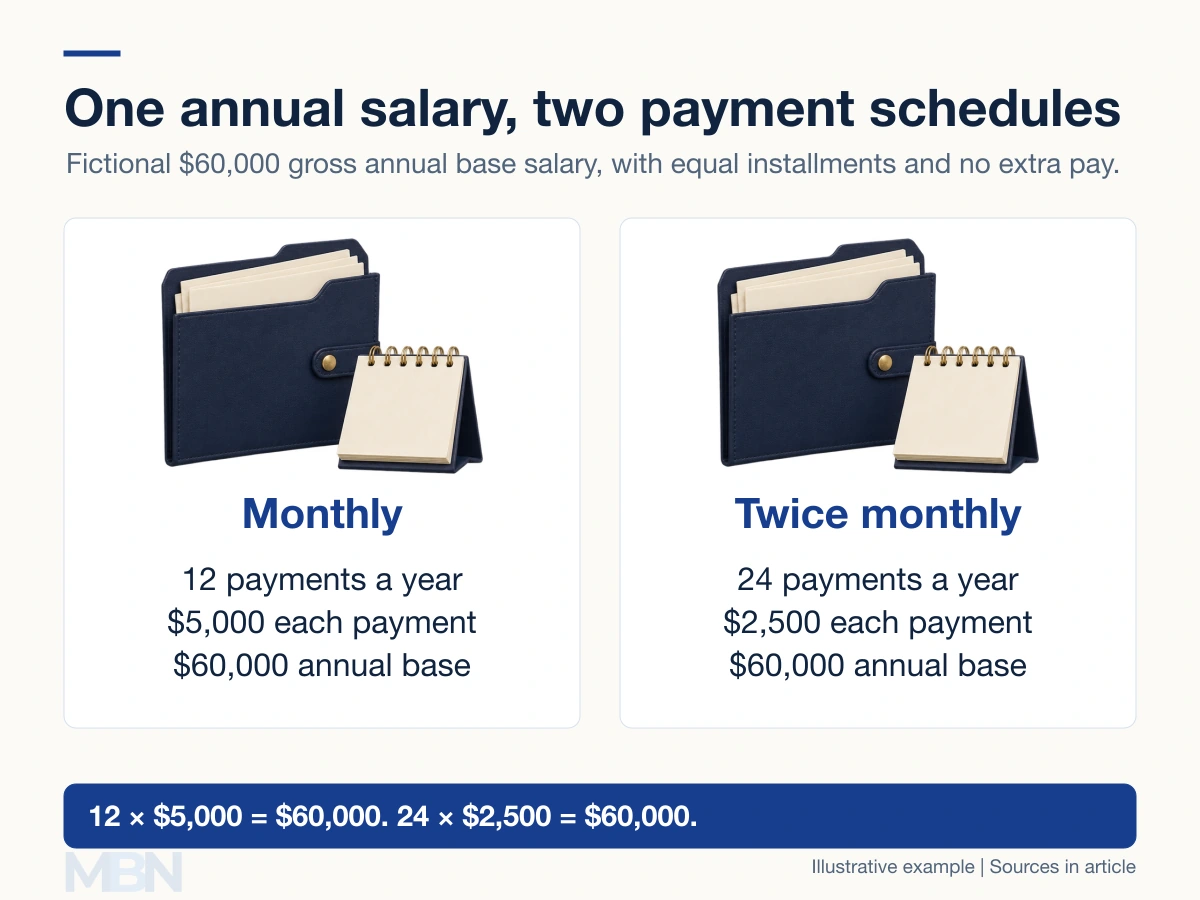
Both schedules produce the same annual base amount before deductions. The example excludes bonuses, overtime, pay changes and partial periods. An every-two-weeks schedule is different from a twice-monthly schedule and should not be assumed to use the same divisor.
Salary is commonly contrasted with pay calculated directly from an hourly rate and hours worked. But wages is also a broad legal and everyday term for employment pay, so the words are not universally exclusive categories.
Gross pay, net pay and compensation
The Federal Reserve Bank of Kansas City distinguishes gross pay from net pay. Gross pay is measured before withholdings and deductions; net pay is what remains afterward. A fixed base salary therefore does not guarantee an identical bank deposit every payday.
Total compensation can include base pay, bonuses, commissions, equity awards and employer-provided benefits. A discretionary bonus or an equity award with vesting conditions should not be described as guaranteed base salary. Benefits also depend on the employer, contract and law.
Salary does not automatically remove overtime rights
In the US, being called a manager or being paid a salary does not by itself establish an exemption from federal overtime rules. The Texas Workforce Commission explains that actual duties and applicable requirements matter, rather than job titles alone.
Covered, nonexempt salaried employees can be entitled to overtime. Certain exemptions have duties and pay requirements, with exceptions and potentially more protective state rules. Managers are not invariably salaried, and salaried workers are not invariably exempt.
Nor does salary automatically remove time-record requirements. The US Department of Labor requires accurate hours and pay records for covered, nonexempt workers. The law does not require one particular timesheet format.
The applicable minimum-wage rules also matter. Dividing a quoted annual salary by assumed hours is not a substitute for applying the relevant coverage and pay-period rules.
What is salary sacrifice?
In the UK, salary sacrifice is an agreed reduction in contractual cash pay, usually in exchange for a non-cash benefit. The employee must agree to the contract change. Employer pension contributions are one possible example.
HMRC says the arrangement must not reduce cash earnings below the applicable National Minimum Wage. Tax and National Insurance treatment depend on the benefit and arrangement; a salary-sacrifice label does not make every benefit tax-free.
What determines a salary?
Responsibilities, skills, location, working arrangements, labor-market conditions and negotiation can influence the amount, alongside contractual and legal requirements. A salary figure alone does not establish job security, work-life balance or entitlement to particular benefits.
A reservation wage is different: it is the minimum pay a person would be willing to accept for a particular job. It describes that person’s decision, rather than an employer’s salary offer or the legal minimum.
Last checked and updated on November 4, 2026 by the MBN editorial team.