
The secondary mortgage market is where existing home loans and mortgage-backed securities are bought and sold. It connects mortgage lending with investors who supply funding after loans have been originated.
A mortgage is a loan secured by property. In the primary market, a lender makes that loan to a borrower. A subsequent sale of the loan belongs to the secondary market, even if it is never packaged into a security.

Why lenders sell mortgages
Selling loans can free funds for further lending. A lender may sell individual loans or a portfolio to another institution, or transfer loans into a securitization structure. The price, contractual obligations and risks retained vary with the transaction.
For a hypothetical example, a lender originates a $200,000 mortgage and later sells it for $200,000. It receives sale proceeds, but that amount is not $200,000 of profit: the lender has given up an asset and incurred funding and operating costs. Actual sale prices can differ from the outstanding loan balance.
How mortgage-backed securities work
A mortgage-backed security, or MBS, gives investors rights to cash flows associated with a pool of mortgages. The SEC’s Investor.gov explanation distinguishes simpler pass-through structures from securities divided into classes with different payment arrangements.
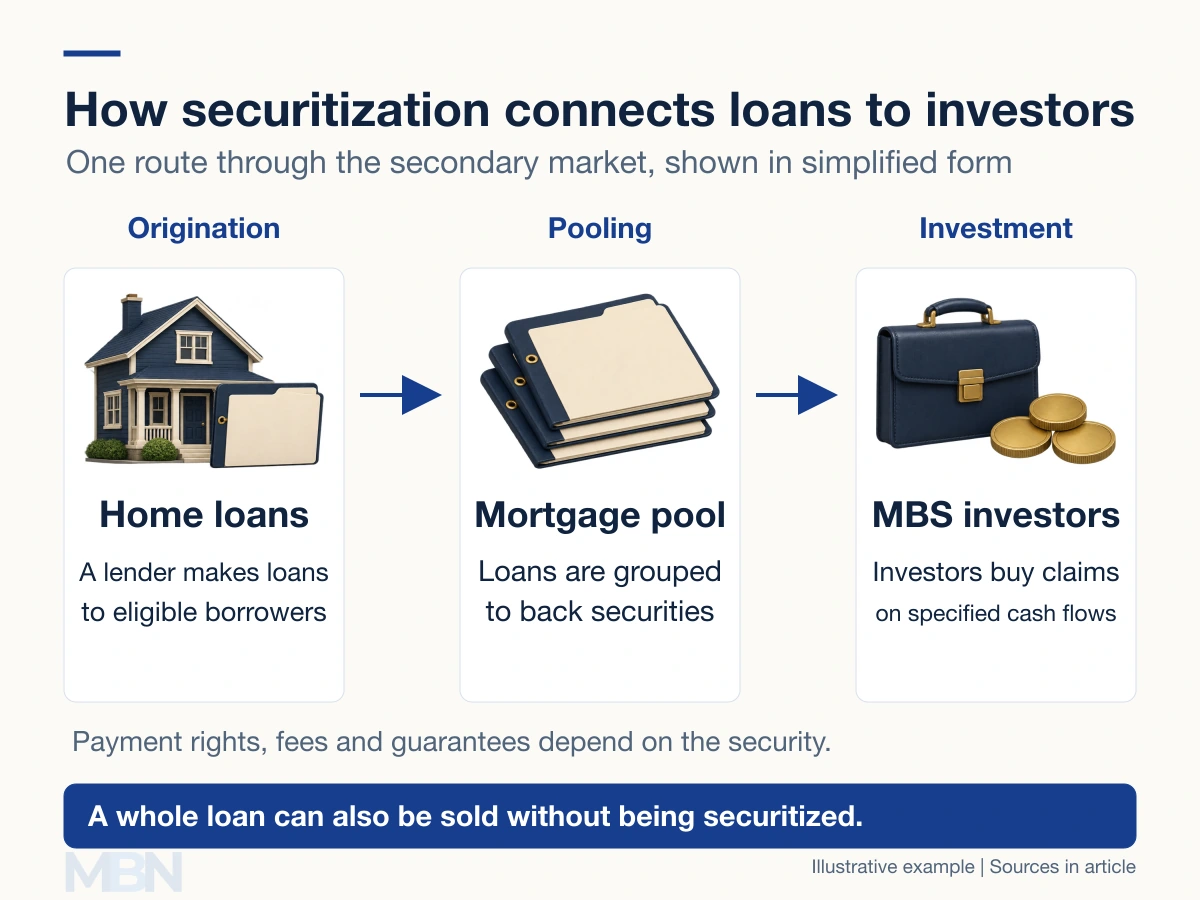
For a pass-through, borrower payments support distributions to investors under the security’s terms. Servicing charges, guarantee fees and other arrangements mean that an investor does not simply receive every dollar a borrower pays.
Prepayments can return principal sooner than expected, leaving investors to reinvest at different rates. Interest-rate changes affect prices and expected repayment patterns. Credit protection depends on the issuer, guarantor and security, rather than the label “MBS” alone.
Loan ownership and servicing are different
The loan owner holds the mortgage asset. The servicer administers the account, collects payments and handles other responsibilities. A sale of the loan does not necessarily transfer servicing.
The Consumer Financial Protection Bureau explains that a sale cannot change the terms of the borrower’s agreement. A servicing transfer can change payment instructions, and requires notice. An adjustable rate can still change according to the existing contract; that is different from a buyer rewriting the loan.
Fannie Mae, Freddie Mac and Ginnie Mae
In the United States, Fannie Mae and Freddie Mac are government-sponsored enterprises involved in mortgage purchases and securitization. Ginnie Mae is a government agency whose qualifying MBS guarantees carry the full faith and credit of the US government. These institutions’ legal structures and guarantees are not interchangeable.
Federal Reserve history dates Fannie Mae’s creation to 1938, its split and reorganization involving Ginnie Mae to 1968, and Freddie Mac’s creation to 1970. Fannie Mae was not first established in 1968.
FHFA’s conservatorship information states that Fannie Mae and Freddie Mac continue under conservatorship, which began in September 2008. Conservatorship is a form of official control, not evidence that the two enterprises own every US mortgage.
Private institutions also participate, and lenders can retain loans. The mix of whole-loan sales, agency securities, private-label securities and retained mortgages changes over time. An old market-share estimate should not be presented as today’s distribution.
Last checked and updated on November 6, 2026 by the MBN editorial team.