
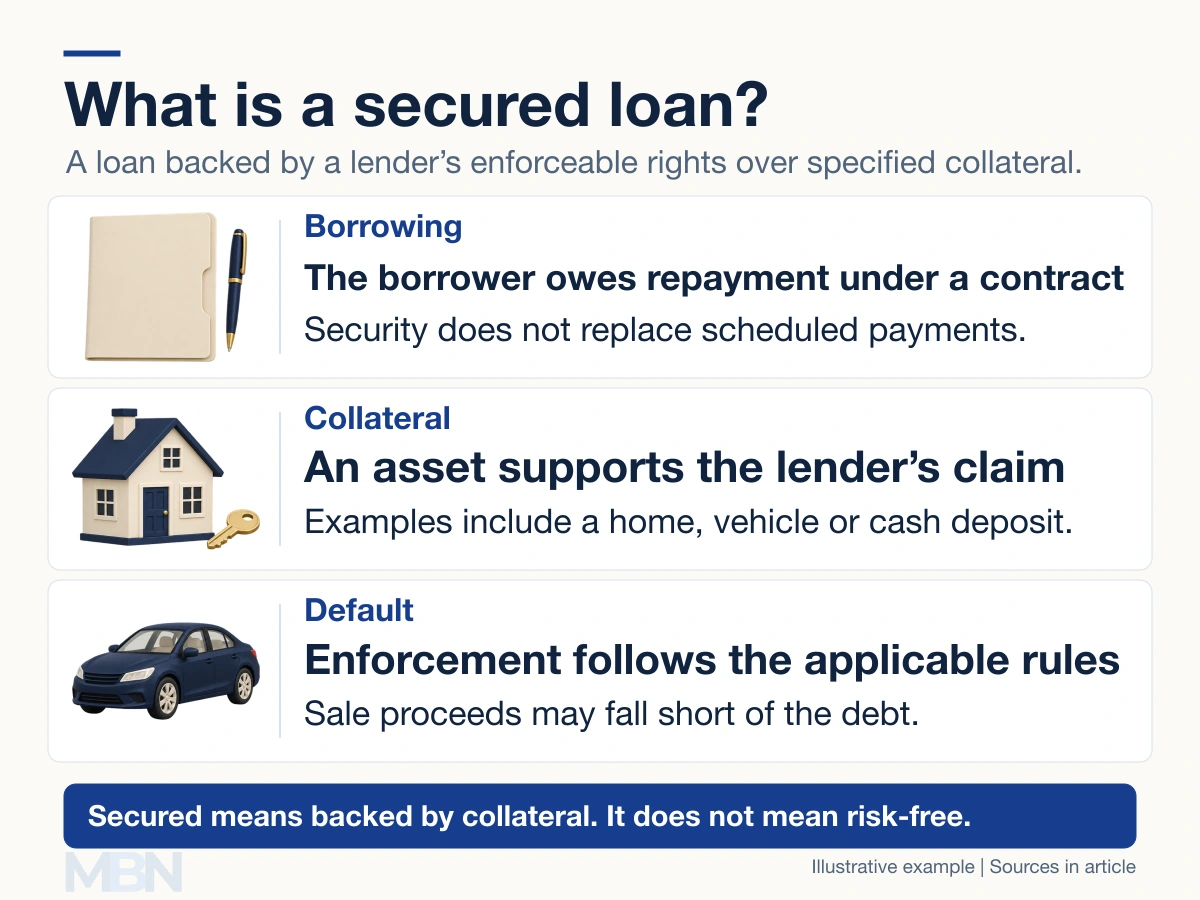
A secured loan is borrowing backed by collateral, an asset over which the lender has agreed legal rights if the borrower defaults. A home mortgage and a loan secured on a vehicle are common examples.
The borrower still owes the payments required by the loan agreement. The collateral gives the lender an additional route to recovery; it does not guarantee that recovery will cover the entire debt.
What can serve as collateral?
The FDIC describes collateral such as a house, vehicle or cash. A business loan might instead use specified equipment or other eligible business assets. The agreement identifies what property supports the debt.
The lender’s legal claim is often called a security interest or lien. Its scope and priority matter. An asset already supporting another debt may offer less protection to a later lender.
What happens after default?
Default means a failure to meet the contract’s obligations. Depending on the asset and jurisdiction, a lender may be able to repossess or foreclose on the collateral and apply the sale proceeds to the debt.
Enforcement is subject to legal restrictions. The FTC explains that US vehicle repossession rules vary by state, and that a repossessor cannot breach the peace. A home foreclosure follows a different process from taking possession of a car.
Can the borrower still owe money?
Yes. Suppose a fictional car loan has a $20,000 unpaid balance. The vehicle sells for $15,000 and allowed enforcement costs are $1,000. Only $14,000 is available for the loan, leaving a $6,000 shortfall.
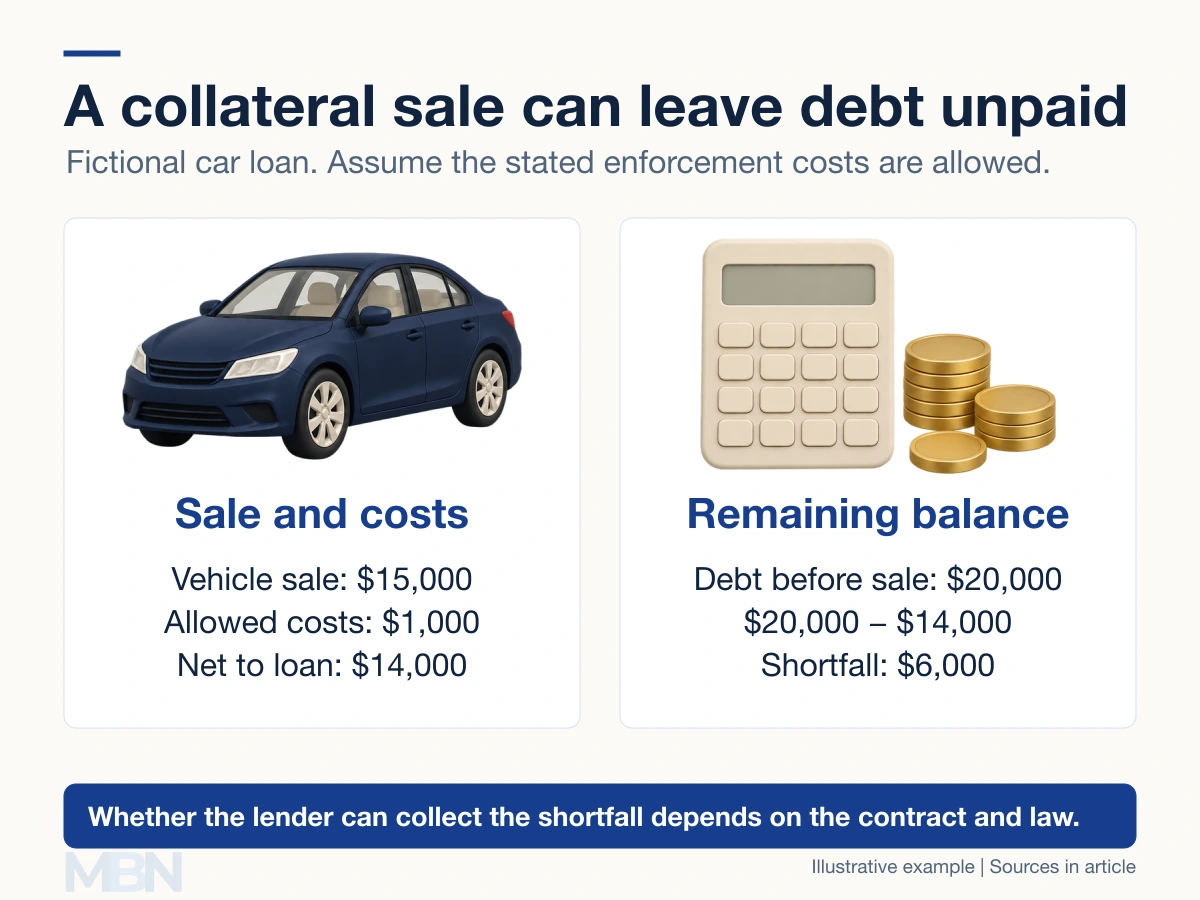
The CFPB calls this remaining amount a deficiency balance. A lender may be able to seek payment, subject to the contract, proper enforcement and applicable law. Conversely, a sale producing more than the debt and allowed costs can leave a surplus for the borrower.
Personal liability is a separate question from whether a loan is secured. The IRS distinguishes recourse from nonrecourse debt: nonrecourse lending generally limits recovery to the collateral. Exceptions and state rules can affect the result.
How does security affect borrowing terms?
Collateral can reduce the lender’s expected loss and support different pricing or loan limits. Rates still depend on the borrower, loan structure and market. A longer term can reduce an installment while increasing total interest.
A secured loan is not automatically an effective way to improve a credit record, and collateral does not ensure approval. The defining feature is the lender’s claim over an asset, with the accompanying risk that the borrower can lose it.
Last checked and updated on November 3, 2026 by the MBN editorial team.