
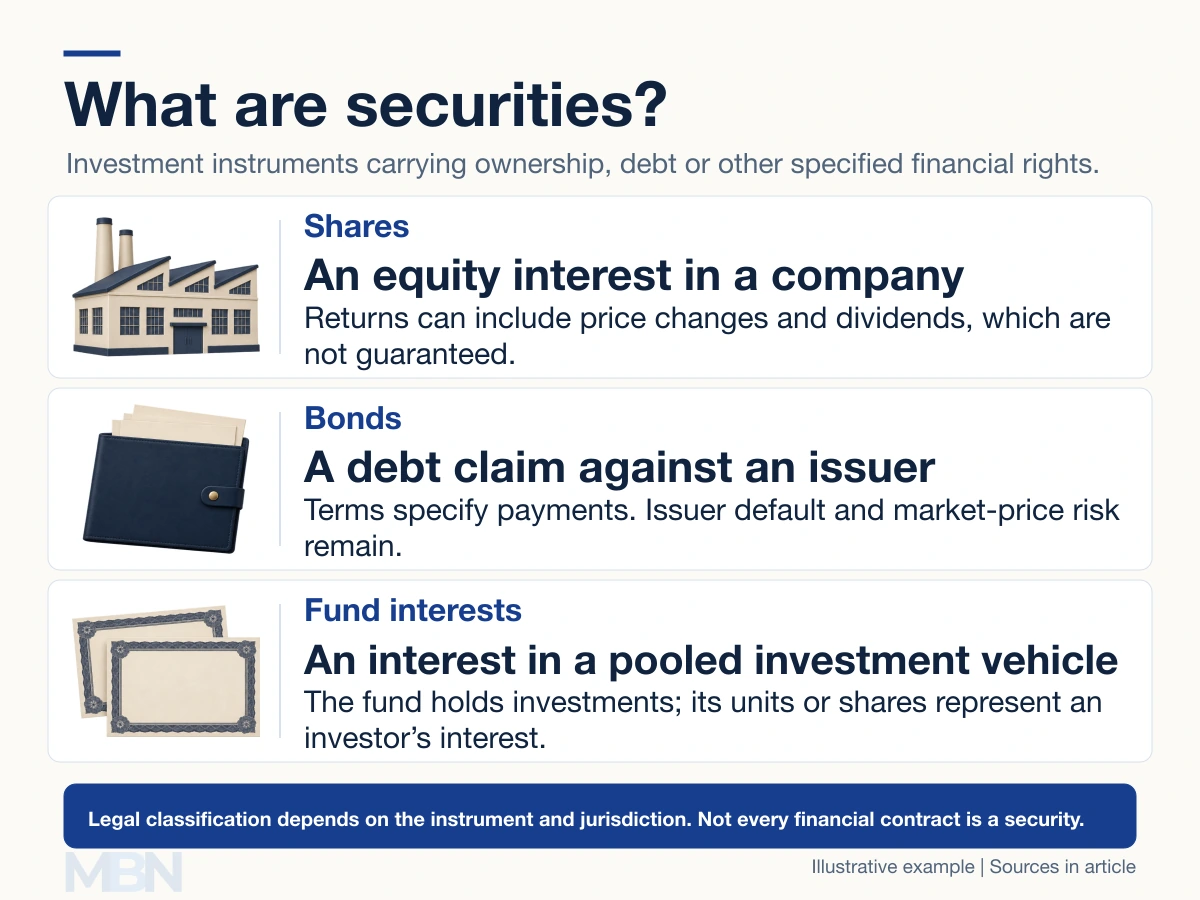
Securities are investment instruments that carry ownership, debt or other specified financial rights. Familiar examples include company shares, bonds and interests in investment funds. The precise legal definition depends on the instrument and the jurisdiction.
The SEC’s small-business glossary includes stocks, bonds and investment contracts. A security does not have to be a paper certificate, exchange-listed or easy to sell. Nor is every valuable asset or financial contract automatically a security.
Equity securities represent ownership
A common share represents an ownership interest in a company. Investors can gain or lose as its price changes and may receive dividends. The SEC’s Investor.gov stock guide explains these ownership rights and risks.
Dividends are not automatic whenever a company earns a profit. A business can retain earnings, and rights differ between common and preferred shares. Shareholders also face losses, including the possibility of losing their investment.
Debt securities represent borrowing
A bondholder lends to an issuer under defined terms. These can specify interest, maturity, repayment priority and other rights. The SEC’s corporate-bond explanation distinguishes creditors from shareholders.
Bondholders do not ordinarily become company owners merely by lending. They can receive contractual payments and experience price gains or losses if they sell. Default can prevent full repayment; zero-coupon and convertible bonds also show why not every bond works identically.
Fund shares represent pooled investments
A mutual fund pools money from investors to hold a portfolio. Its shares represent an interest in that pooled investment. The fund’s holdings and expenses affect investors’ returns.
A share and bond example
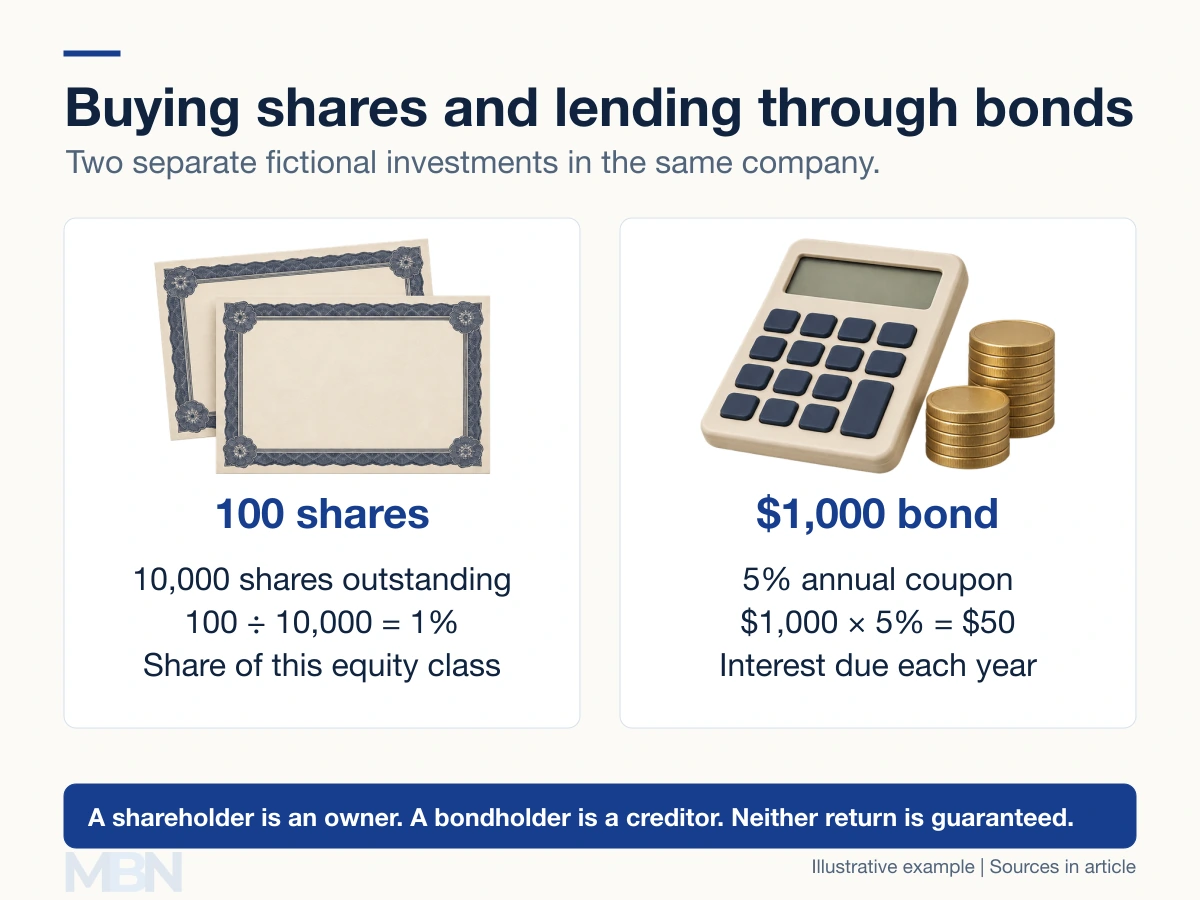
Suppose a fictional company has 10,000 identical common shares outstanding. Buying 100 gives an investor 1% of that class, assuming no change in the share count. It does not promise a 1% annual return.
Separately, a $1,000 face-value bond with a 5% annual coupon calls for $50 annual interest and repayment under its terms. The coupon is based on face value, not necessarily the price an investor pays. Payment still depends on the issuer meeting its obligations.
Issuing and trading securities
In a primary-market issue, an issuer sells new securities to raise funds. In a secondary-market transaction, an existing investor generally sells to another investor. The company does not receive each subsequent share-trade payment.
Securities can trade on exchanges or through over-the-counter markets. Others have restrictions or limited buyers. Tradability is not a guarantee of liquidity.
Are derivatives securities?
Some are, but the categories do not coincide. Derivatives derive value from an underlying asset, rate or other reference. The CFTC explains that US security futures are jointly regulated with the SEC, while broad-based stock-index futures fall under CFTC jurisdiction. Calling every future, swap or forward a security is inaccurate.
Paper certificates and electronic records
The SEC distinguishes direct registration from holding securities through an intermediary in street name. In street name, the investor is the beneficial owner while an intermediary or nominee appears on the issuer’s register. Direct registration can be electronic; registered ownership does not necessarily require paper.
Who regulates securities?
The SEC oversees US securities markets within its legal remit. In the UK, the FCA began work on April 1, 2013, taking over functions from the FSA. The Bank of England explains the separate PRA and FCA roles. Identifying the FSA as the current UK regulator is outdated.
Last checked and updated on November 4, 2026 by the MBN editorial team.