
Securitization structures the cash flows or credit risk of loans and other assets into exposures that investors can hold. In a traditional transaction, assets commonly support securities issued through a separate vehicle.
The IMF’s securitization primer describes pooling assets and using their payments to support securities. Mortgage-backed securities, or MBS, are one example. Other asset-backed securities can reference vehicle loans, credit-card receivables or other eligible assets.
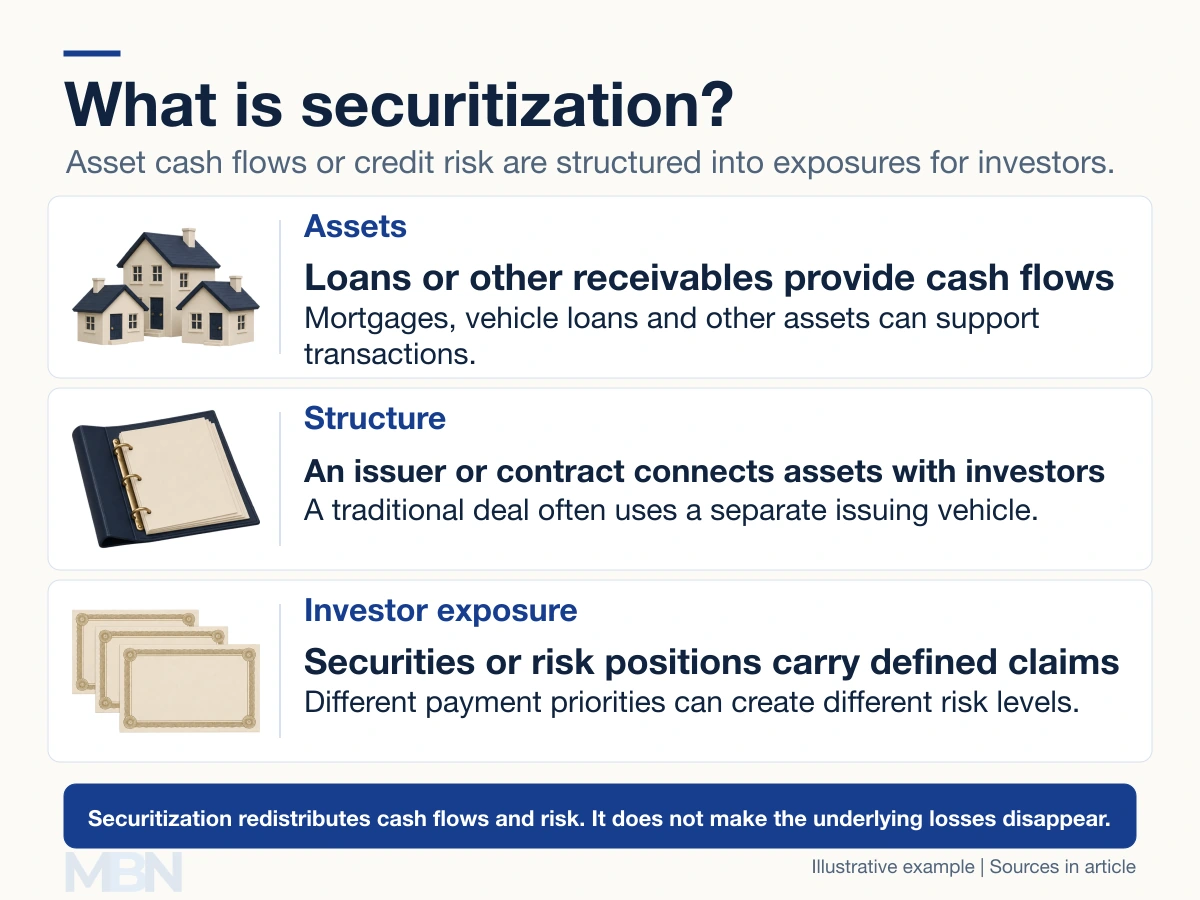
How a traditional transaction works
An originator creates or acquires the assets. A special-purpose vehicle, an entity established for the transaction, commonly acquires a pool and issues securities to investors. Borrower payments support the securities’ cash flows after the applicable fees and other allocations.
A servicer handles collections and administration. Securitization is more than a simple sale of an individual loan: the financing structure determines the investors’ claims and payment rules.
What is a tranche?
A tranche is a class or layer of exposure with particular payment and loss priorities. The Basel framework distinguishes these stratified risk positions. Junior positions generally absorb specified losses before more senior positions, according to the contract.
Suppose a fictional $10 million pool supports a $2 million junior position and an $8 million senior position. Ignoring other protections, a $1.5 million principal loss is entirely allocated to junior investors. A $3 million loss exhausts the $2 million junior layer and allocates $1 million to the senior layer.
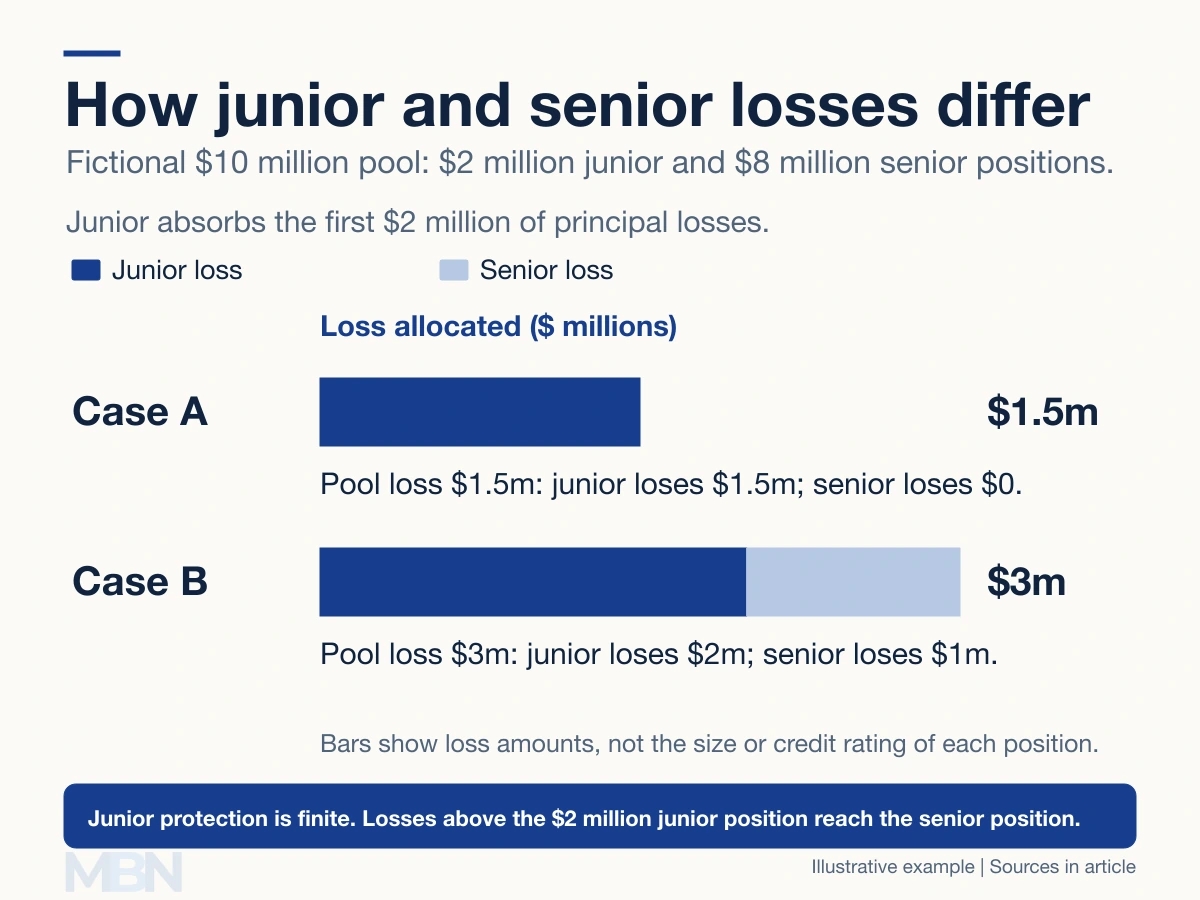
Subordination changes who bears losses first. It does not guarantee that senior investors cannot lose money. Actual payment waterfalls can also contain reserves, fees, triggers and other priorities.
Must the assets leave the bank?
No. In a synthetic securitization, credit derivatives or guarantees transfer specified credit exposure while the bank can retain the assets. The Basel Committee’s February 2026 report explains these synthetic risk transfers.
Even a transaction involving a legal transfer does not automatically remove all assets or risks from financial reporting. IFRS 9 sets conditions for derecognizing transferred financial assets. Derecognition means removing an asset from the accounts; retained risks and continuing involvement can affect the result. Regulatory capital relief is a separate assessment.
What changes for borrowers?
A loan sale and a servicing transfer are different events. The CFPB explains that a mortgage can be sold without changing its servicer. Where servicing does transfer, relevant notices give payment instructions. Borrowers should not be assumed to owe different contractual terms merely because investors change.
What risks remain?
Asset defaults, early repayments, interest-rate exposure, structural complexity and weak market liquidity can affect investors. A tradable security is not necessarily easy to sell at a favorable price. Pool composition, underwriting quality and the deal documents matter more than the broad securitization label.
Last checked and updated on November 4, 2026 by the MBN editorial team.