
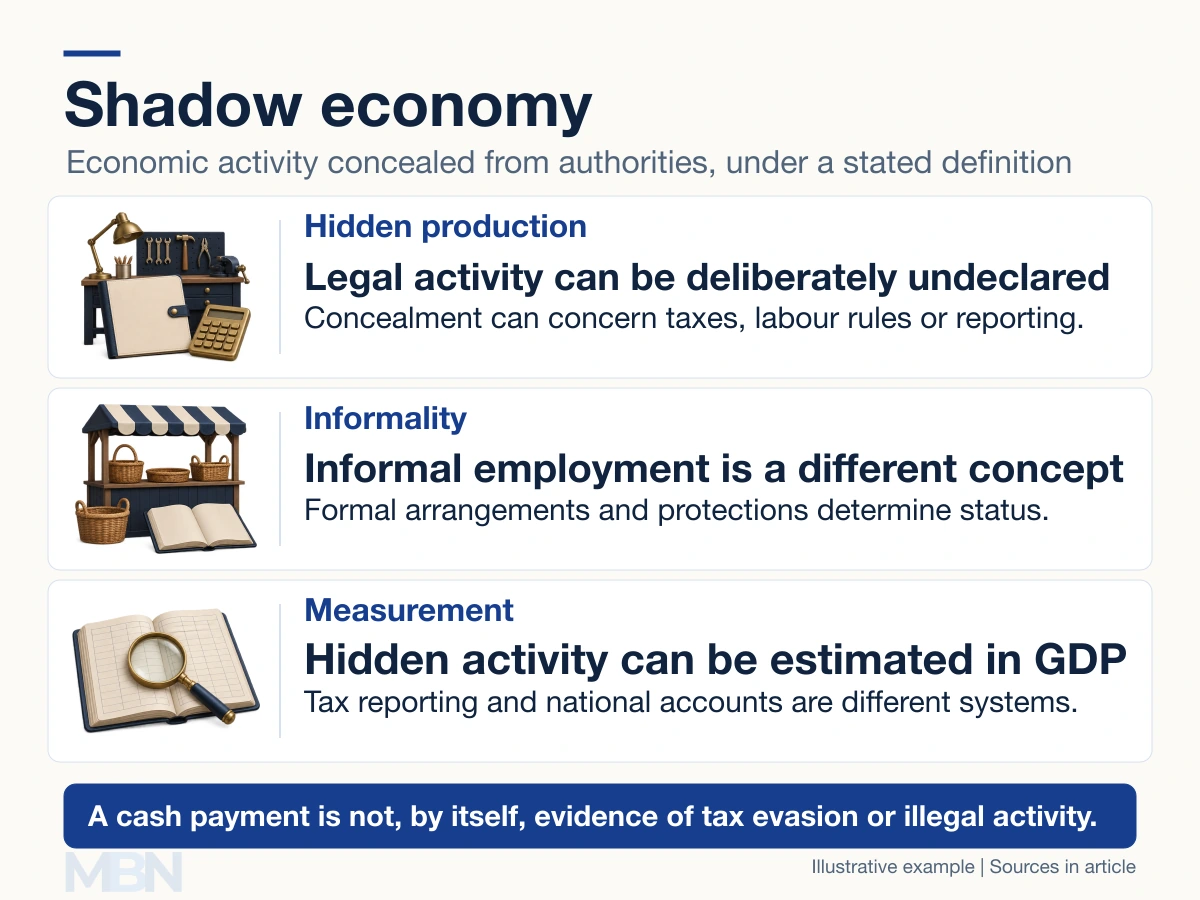
The shadow economy is economic activity concealed from public authorities, although the precise scope varies between studies. A common narrow definition concerns otherwise legal production hidden to avoid taxes, social contributions, labour requirements or reporting obligations.
An undeclared payment for legal repair work can fit that definition. Illegal production, informal employment and activity missed by statistical sources are related categories, but they are not identical. The international handbook on underground production explains these boundaries.
Shadow activity and informal employment
The International Labour Organization’s (ILO) 2023 statistical resolution defines informal employment by the absence of relevant formal arrangements in law or practice, including employment protections and social-security coverage. Informal jobs can exist in formal enterprises as well as in the informal sector.
That concept is broader than deliberate income-tax evasion and should not be used as a synonym for criminal activity. Legal work, the legal status of the business, tax compliance and the worker’s protections are separate questions.
Payment in cash does not itself establish concealment. A cash transaction can be recorded and reported correctly, while a concealed transaction can use a bank transfer. Neither a street stall nor a small business is automatically illegal or undeclared.
How hidden activity enters GDP
Gross domestic product, or GDP, measures the value of production within a country over a period, using national-accounts rules. Statistical offices use estimates and adjustments to capture activity that ordinary surveys or administrative records miss.
The Organisation for Economic Co-operation and Development (OECD) explains why underground activity is not wholly absent from national accounts. The UK Office for National Statistics (ONS) also describes the inclusion of illegal activity in GDP. Counting production for statistical purposes does not make the activity legal.
Value added is the value of output after deducting goods and services used up in production. Suppose directly captured value added is 900 units and a non-overlapping adjustment for hidden production is 100. Official GDP is already 1,000. Adding the same 100 again would incorrectly produce 1,100.
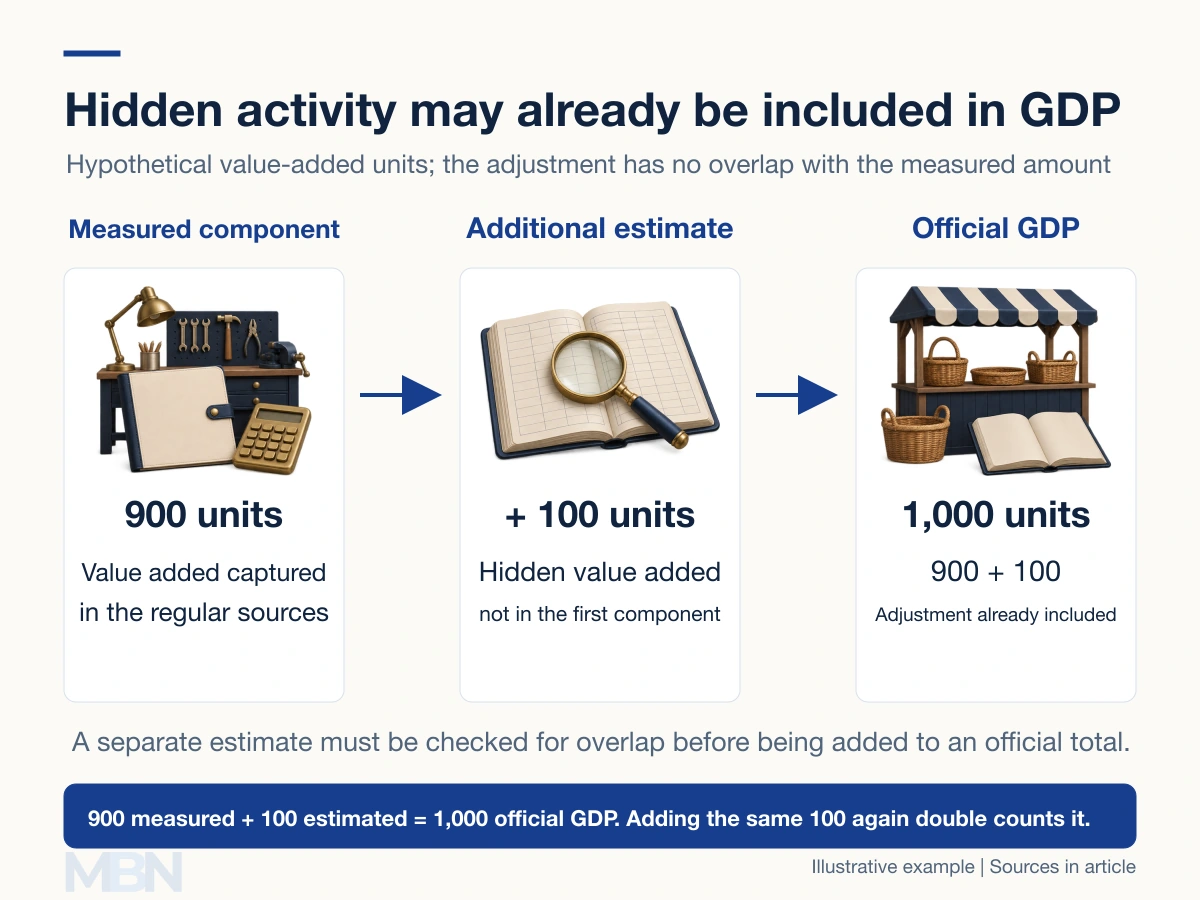
Coverage and methods vary, and some activity can remain unmeasured. It is therefore necessary to check whether a separate shadow-economy estimate describes activity already included, an estimate of remaining omissions, or a different concept altogether.
Employment percentages are not GDP percentages
If 60 of 100 employed people have informal jobs, the informal-employment share is 60%. It does not follow that informal production accounts for 60% of GDP, or that 60% of all taxes go unpaid.
People and jobs are counted differently from value added. Productivity, hours, multiple jobs, tax thresholds and the applicable definitions affect the relationship. An informal worker can also pay taxes indirectly through purchases.
Why estimates differ
Methods can use surveys, tax-audit evidence, discrepancies between data sources or statistical models. Cash demand and electricity use can inform some models, but neither is a direct meter of undeclared production. Payments technology, energy efficiency and industry composition can change the relationship.
Country comparisons require matching definitions, years, methods and denominators. A model-based estimate, an employment survey and an official national-accounts adjustment should not be placed in one ranking as equivalent observations.
For example, Statistics Canada’s March 2025 release estimated underground activity at C$72.4 billion for 2023, equivalent to 2.5% of GDP. It explains its scope, exclusions and estimation assumptions. That dated study is not a universal measure covering every illegal activity.
Workers, businesses and public revenue
Concealment can reduce tax receipts and undermine enforcement. Informality can also reflect scarce formal jobs, administrative barriers or limited access to protections. Workers’ circumstances, skills and bargaining power vary; one description cannot fit every participant.
Formalisation can involve registration, simpler procedures, access to social protection and appropriate enforcement. Tax rates, trust, institutions and economic conditions can interact, but a single factor does not establish a universal cause or remedy.
A shadow-economy estimate is also not a forecast of immediately recoverable tax revenue. Tax bases, exemptions, compliance responses and the costs of collection determine how much revenue could actually change.
Last checked and updated on November 11, 2026 by the MBN editorial team.