
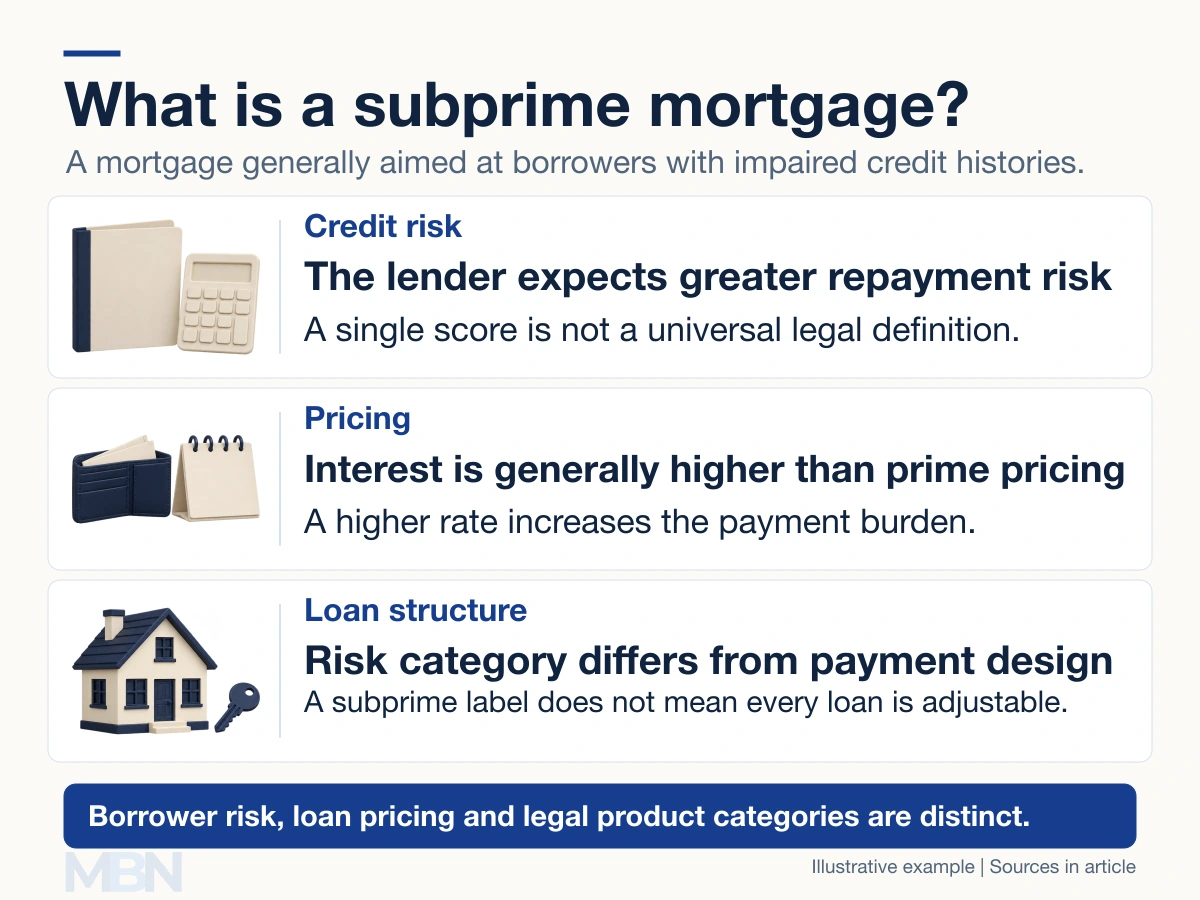
A subprime mortgage is generally a higher-interest home loan intended for borrowers with impaired credit histories. The higher price is intended to compensate the lender for greater expected repayment risk. It is not a promise that every borrower with a particular score will receive the same loan.
The Consumer Financial Protection Bureau explains subprime lending in relation to credit history and pricing. The term is associated with the US market, although risk-based mortgage pricing exists elsewhere.
Is there one subprime credit-score cutoff?
No single cutoff defines every lender’s product or every dataset. Credit-scoring models, underwriting standards and research categories differ. Income, existing debts, payment history and the loan’s terms also matter.
For example, the CFPB’s mortgage borrower-risk charts use FICO Score 8 bands: below 580 is deep subprime, 580–619 subprime, 620–659 near-prime, 660–719 prime and 720 or above super-prime. Those are the categories for that statistical series, not universal mortgage eligibility rules.
Does subprime mean adjustable-rate?
No. Borrower risk and interest-rate structure are different characteristics. A fixed-rate mortgage keeps its note rate unchanged; an adjustable-rate mortgage resets under a stated formula. Either structure can involve repayment risk.
A low introductory payment can rise later under an adjustable contract. Subprime pricing can also make a fixed-rate loan substantially more expensive than a lower-rate loan of the same size and term.
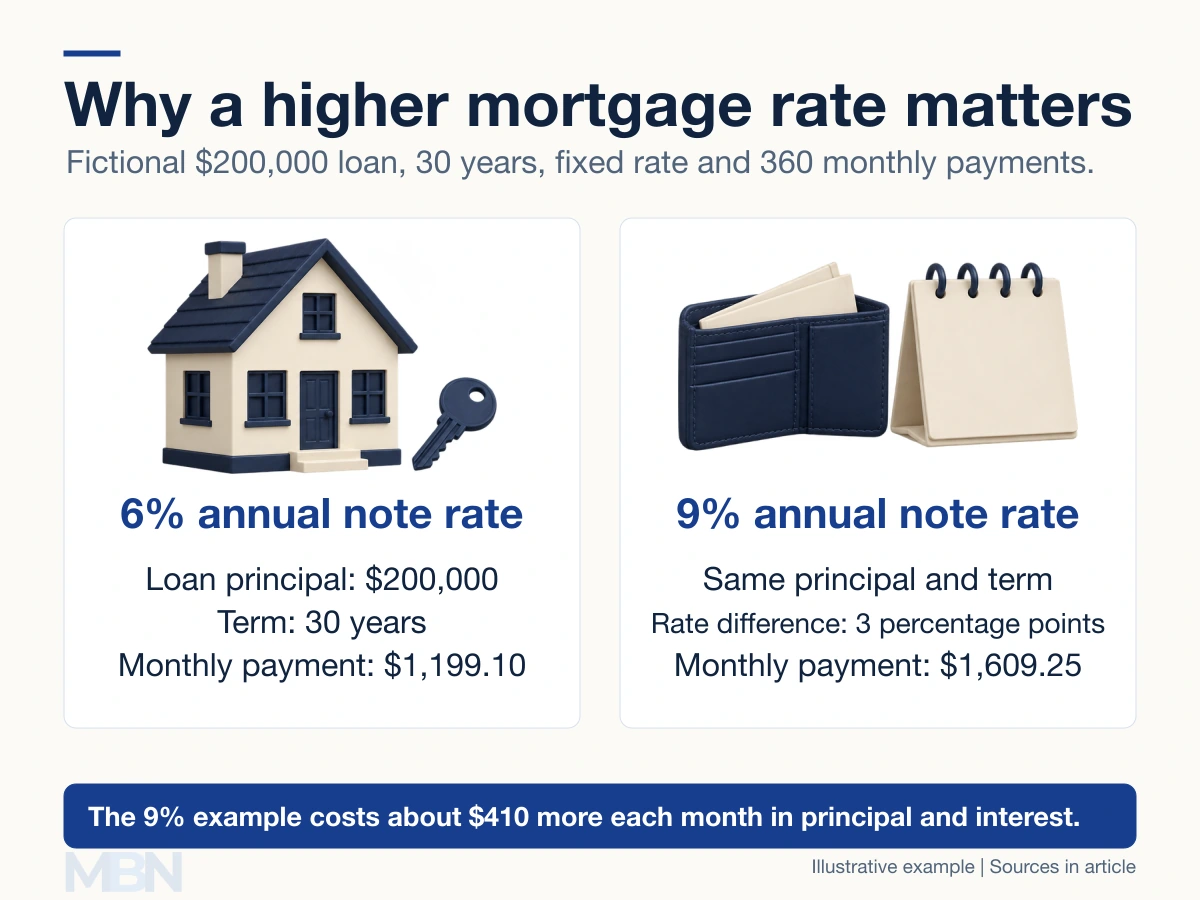
Our fictional $200,000, 30-year fully amortizing mortgage costs about $1,199.10 monthly at 6%, compared with $1,609.25 at 9%. The difference is about $410 a month before taxes, insurance and fees. Neither illustrative rate defines a prime or subprime borrower.
How do current US mortgage rules apply?
For covered consumer mortgages, Regulation Z requires a reasonable, good-faith determination of ability to repay, subject to its scope and exceptions. Relevant information must be considered and generally verified. A lender cannot rely simply on an expectation that the home’s value will keep rising.
“Qualified Mortgage” describes a regulatory category with specified conditions and legal protections. It is different from a credit-risk label. Likewise, a higher-priced mortgage loan is defined using APR relative to a benchmark, rather than a single FICO cutoff.
What happened during the financial crisis?
Federal Reserve History describes how expanded high-risk lending and expectations of further house-price gains reinforced the housing boom. Mortgages were also pooled into securities, spreading exposures to investors and financial institutions.
As prices fell, refinancing or selling a home became less able to cover the debt. Defaults and losses on mortgage-related securities increased, contributing to a wider financial crisis. House prices had already turned down before the crisis intensified in 2008.
The US Great Recession ran from December 2007 to June 2009. The episode involved lending standards, mortgage structures, securitization, leverage and funding pressures, rather than a certainty that all low-score borrowers would default.
Last checked and updated on November 3, 2026 by the MBN editorial team.