
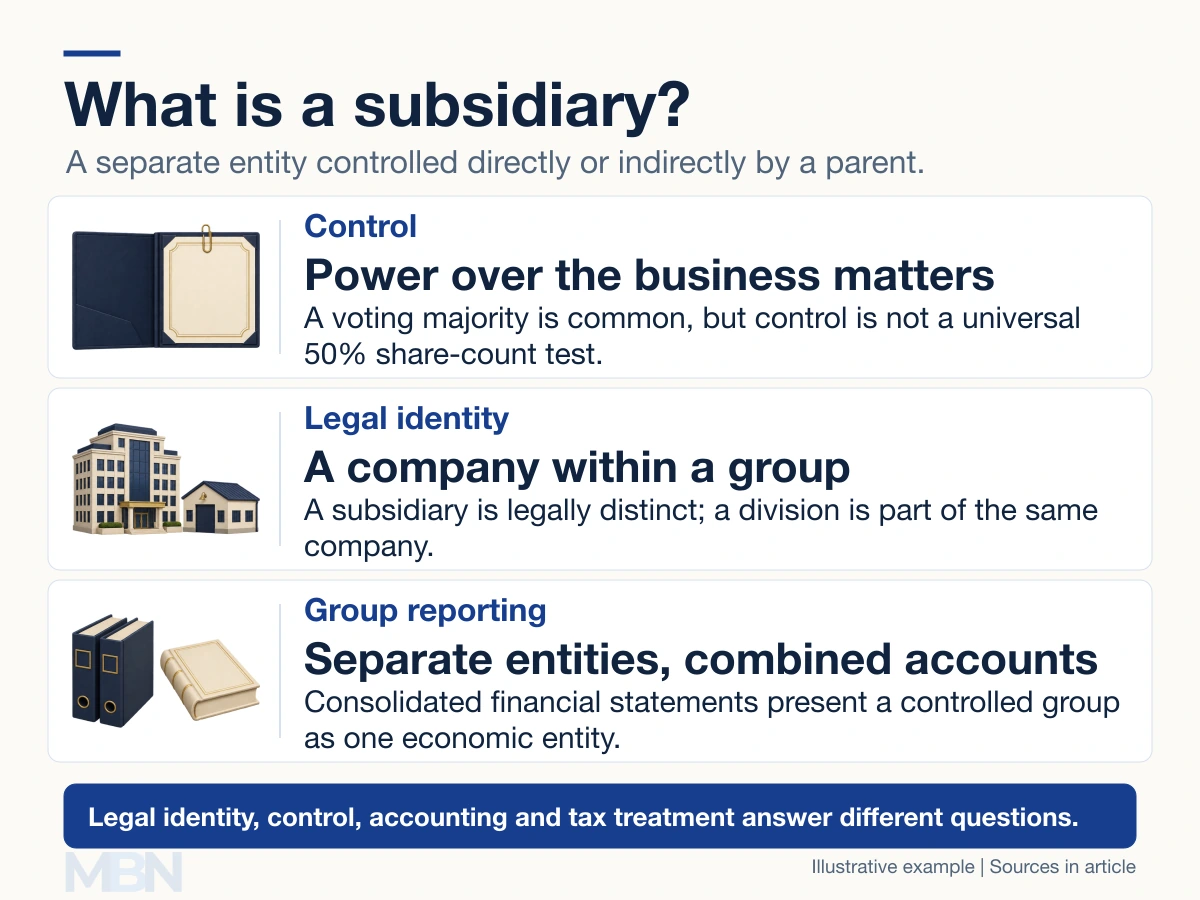
A subsidiary is an entity controlled by another entity, its parent. It can be controlled directly or through other companies in a group. Owning a majority of voting rights is a common route to control, but no single share-percentage rule explains every arrangement.
A wholly owned subsidiary belongs entirely to its parent or group. Other subsidiaries have outside shareholders. A subsidiary remains a separate legal entity, unlike a division within the same company.
Control is more than a share count
The US Securities and Exchange Commission’s Rule 405 defines a subsidiary through direct or indirect control. It separately describes a majority-owned subsidiary using more than 50% of the relevant voting securities, rather than “at least 50%.”
A 50–50 holding does not automatically give either investor unilateral control. Agreements, voting rights and other circumstances can matter. Under IFRS 10’s control principles, the assessment combines power over relevant activities, exposure or rights to variable returns, and the ability to use that power to affect returns.
A simple voting example
Suppose a fictional company has 100 equal voting shares. A parent owns 60 and other investors own 40. With no special rights or overriding arrangements, the parent has 60% of the votes and controls ordinary decisions.
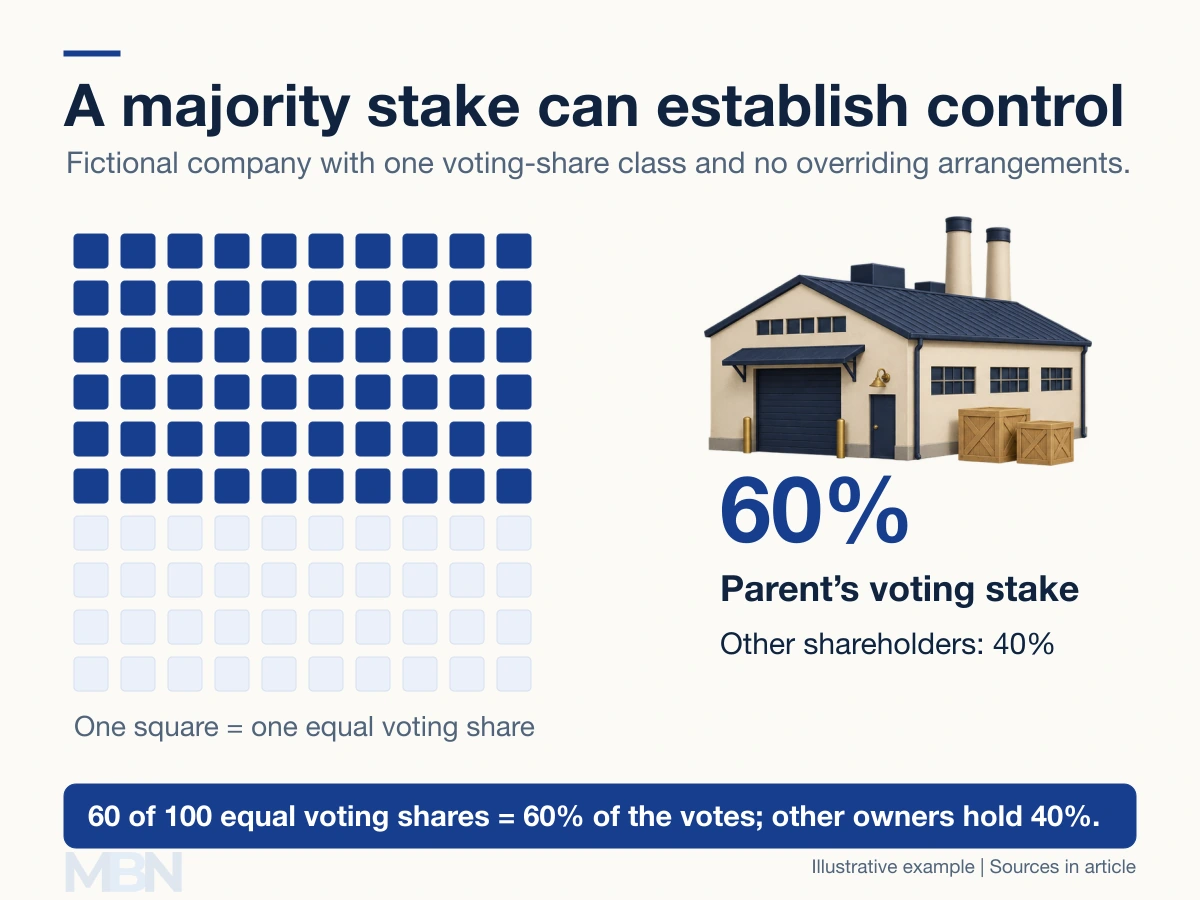
The company is a subsidiary, but it is not wholly owned. A different company could be controlled with fewer voting rights, depending on the facts. Conversely, protective rights or joint decision-making arrangements can change the analysis.
Separate identity does not mean absolute immunity
A subsidiary can hold assets, enter contracts and owe debts in its own name. Parent ownership alone does not make every subsidiary obligation the parent’s obligation.
However, “the parent is never liable” is too broad. A parent can assume obligations, such as through a guarantee, or incur responsibility for its own conduct. In Okpabi v Royal Dutch Shell, the UK Supreme Court explained in 2021 that a parent’s possible duty of care depends on ordinary legal principles and the facts. This is distinct from disregarding a company’s separate identity.
Group accounts and tax returns differ
IFRS 10 generally requires consolidation where a parent controls subsidiaries, with specified exemptions. Consolidation presents the group’s finances as one economic entity; it does not merge the companies legally. Transactions within the group are eliminated in consolidation.
Tax classification is a separate question. The IRS explains that a single-member LLC may be disregarded as separate from its owner for federal income tax, unless it elects corporate treatment. It can still be treated separately for employment tax and certain excise taxes.
US consolidated corporate income-tax returns have their own rules. The general affiliated-group test in section 1504 requires at least 80% of both voting power and stock value, with exclusions and other conditions. Merely being a subsidiary is insufficient.
Subsidiary, associate and affiliate
An associate is different under IAS 28: the investor has significant influence rather than control or joint control. A minority investment does not automatically establish that influence.
“Affiliate” depends on the context. SEC Rule 405 includes entities under common control as well as controlling and controlled entities. It is not simply another word for a minority shareholding.
For a real example, BNSF identifies its railway company as a wholly owned Berkshire Hathaway subsidiary. A company’s current ownership should be checked rather than inferred from an old list of investments.
An introductory accounting example
The older lesson below from the drdavebond channel introduces a cash acquisition of a wholly owned subsidiary. Its 100% stake and simplified asset-valuation assumptions belong to that example; they do not define every subsidiary.
Last checked and updated on November 4, 2026 by the MBN editorial team.