
A surety bond is an undertaking in which a surety answers for specified obligations of another party, the principal, for the benefit of an obligee. Its protection depends on the bond’s terms and applicable law.
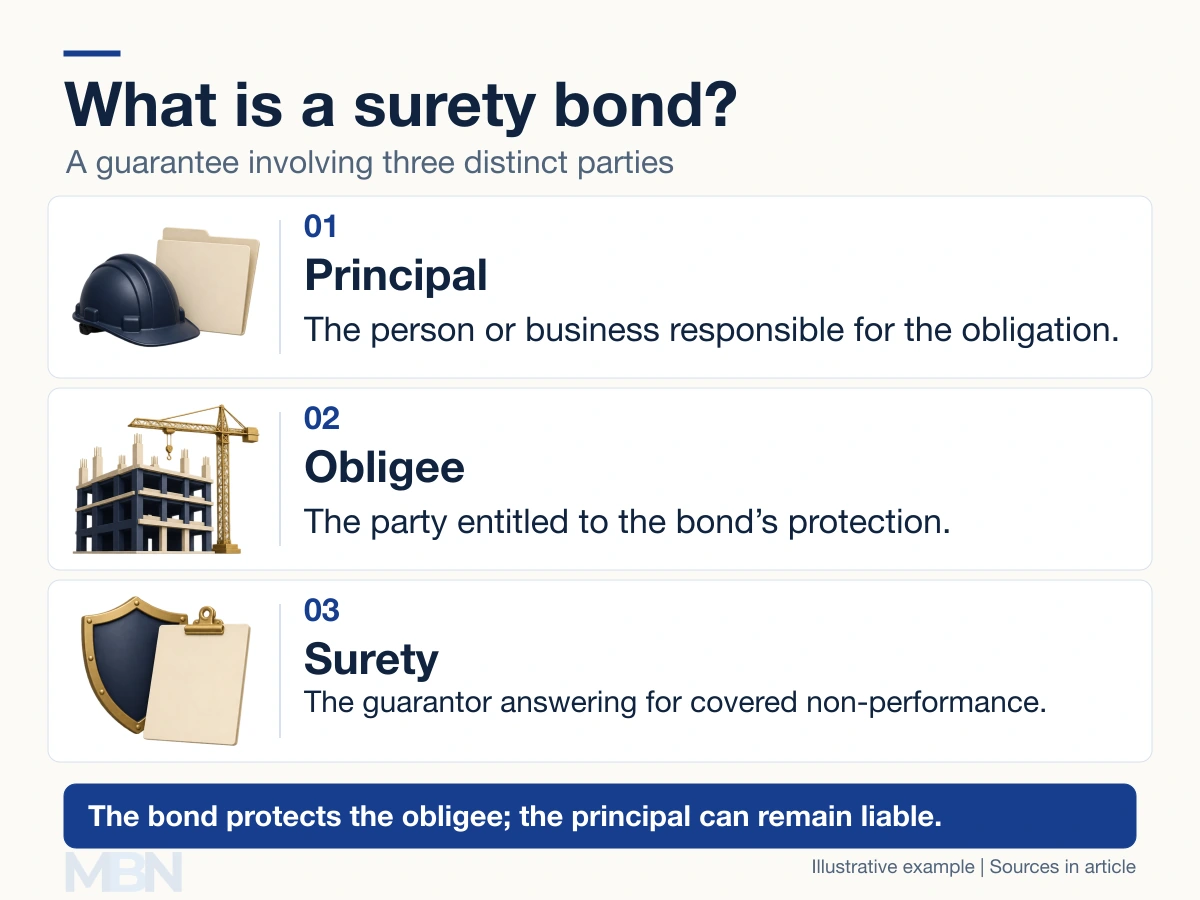
The California Department of Insurance glossary describes these relationships. The principal is responsible for the underlying obligation, the obligee receives the protection, and the surety provides the guarantee. The obligee need not be a government agency.
How contract bonds differ
A performance bond backs the contractor’s contractual performance. A payment bond protects eligible suppliers and subcontractors against covered non-payment. A bid bond supports the successful bidder’s obligation to enter the contract and provide required bonds.
The US Small Business Administration explains these categories and its programme supporting eligible small-business contract bonds. A licence or permit bond instead concerns specified legal or regulatory obligations. These different products do not all cover the same losses.
What happens after default?
A claimant must meet the bond’s requirements. Default does not automatically produce a cheque for the full bond amount. Depending on the instrument, resolution may involve arranging completion, financing performance, settling a valid payment obligation or disputing a claim.
The bond amount, often called its penal sum, states a relevant liability limit under the instrument. Coverage, other obligations, expenses and the effect of that limit require the actual wording and law to be considered.
The premium is not the bond amount
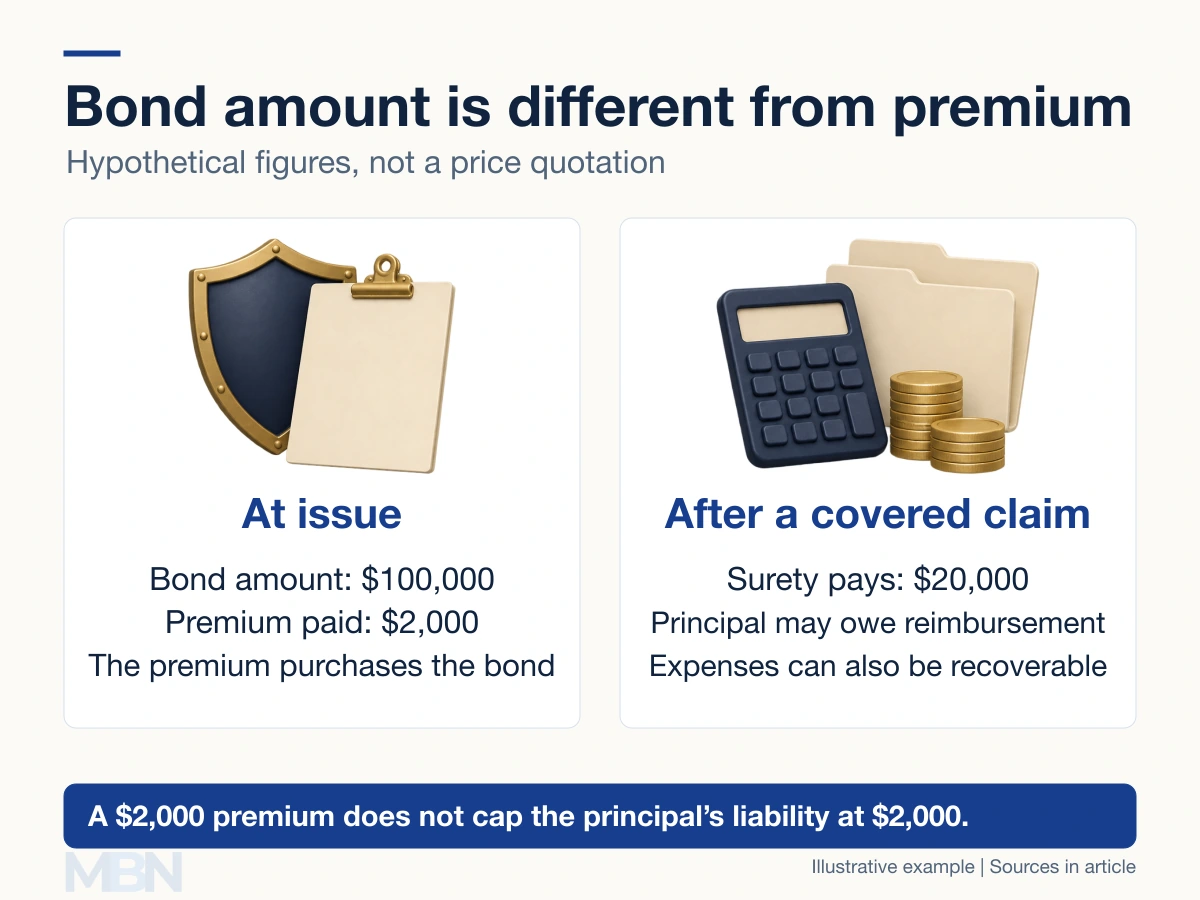
Suppose a hypothetical bond has a $100,000 amount and a $2,000 premium. The principal pays $2,000 to obtain it; that does not place $100,000 in a freely spendable loan account.
If the surety pays an approved $20,000 covered claim, the principal may have to reimburse it. Paying the premium does not limit that reimbursement exposure to $2,000. These figures illustrate the distinction and are not standard market prices.
A public-agency explanation of surety indemnity describes reimbursement by the principal and other indemnitors. An indemnitor is a person or organisation agreeing to repay the surety for covered losses or expenses. The precise obligations depend on the agreement and law.
Why it differs from ordinary first-party cover
Although surety business is commonly regulated within insurance, the commercial arrangement typically leaves the principal ultimately responsible for its own bonded obligations. It should not be described as insurance that simply absorbs the principal’s default loss after the premium is paid.
Other uses and regulatory requirements
For lost share certificates, an indemnity bond can protect the issuer and transfer agent if the missing certificate later appears. The bond is the undertaking; its premium is the charge for obtaining it. They are not two separate definitions of “surety bond”.
Bail bonds are another specialised use, with rules varying by jurisdiction. They should not be treated as the model for every business bond.
For US federal procurement, FAR Part 28 sets requirements and exceptions for bonds and alternative protections. Not every federally funded project has an identical requirement. Treasury also maintains a current authorised corporate-surety list for federal bonds. Bond requirements and terminology differ across countries.
Last checked and updated on November 6, 2026 by the MBN editorial team.