
A syndicated loan is financing provided by a group of lenders to a borrower under a common facility agreement. Each lender takes an agreed share, allowing the financing requirement and credit exposure to be spread across institutions.
A bilateral loan has one lender. Syndicated facilities can involve banks and nonbank institutions, as BIS research explains. Borrowers can include companies, public bodies and project-finance entities.
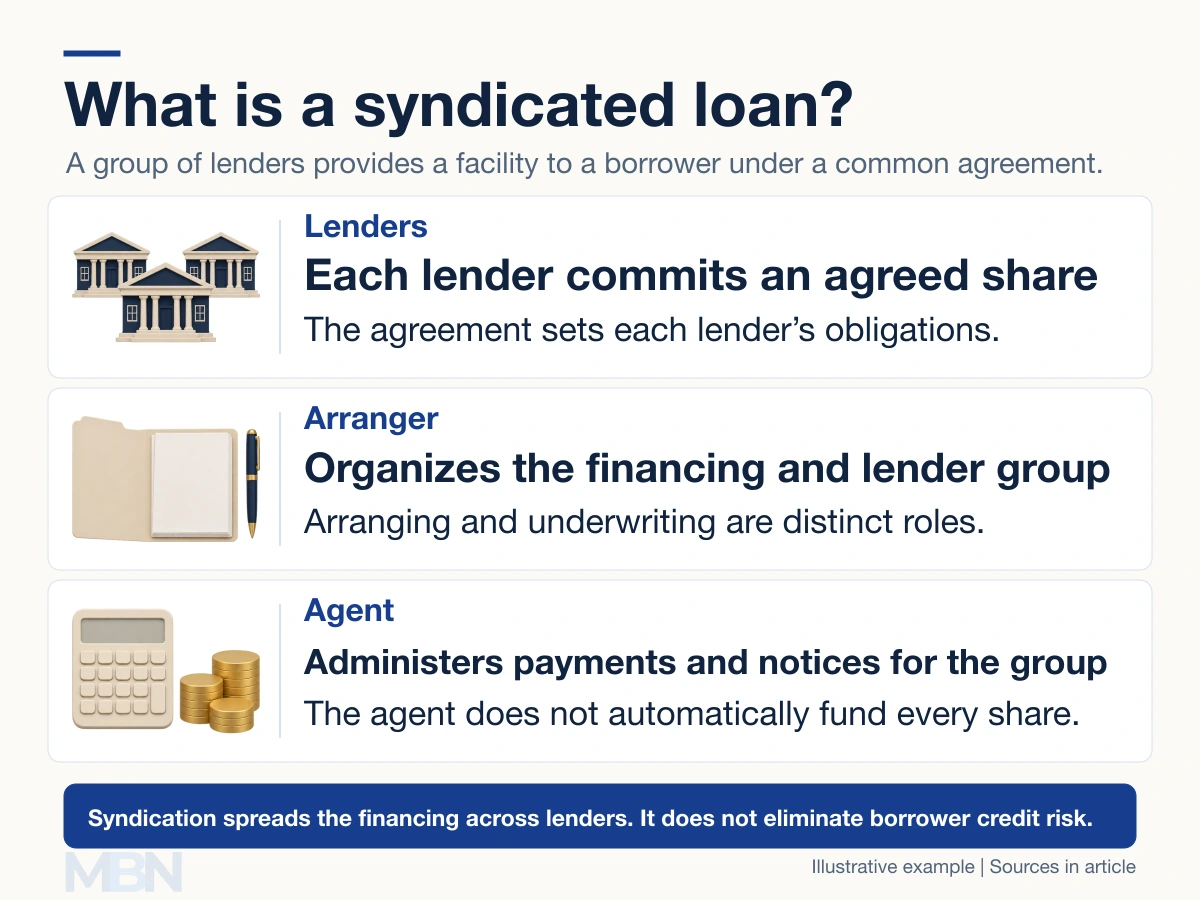
Who does what?
The arranger helps structure the financing and assemble the lender group. An administrative or facility agent handles specified tasks after signing. One institution may hold both roles, but the responsibilities differ.
The Loan Market Association describes a common agreement with separate lender obligations. The LMA also distinguishes payment administration from holding and enforcing security, which may be assigned to a security agent.
An underwriter may commit to provide financing before distributing shares to other lenders. Arranging a loan does not always mean guaranteeing that the entire requested amount will be raised.
A simple funding example
Suppose a fictional company draws a $100 million loan. Lender A provides $40 million, B provides $35 million and C provides $25 million. Together they fund the same $100 million facility.
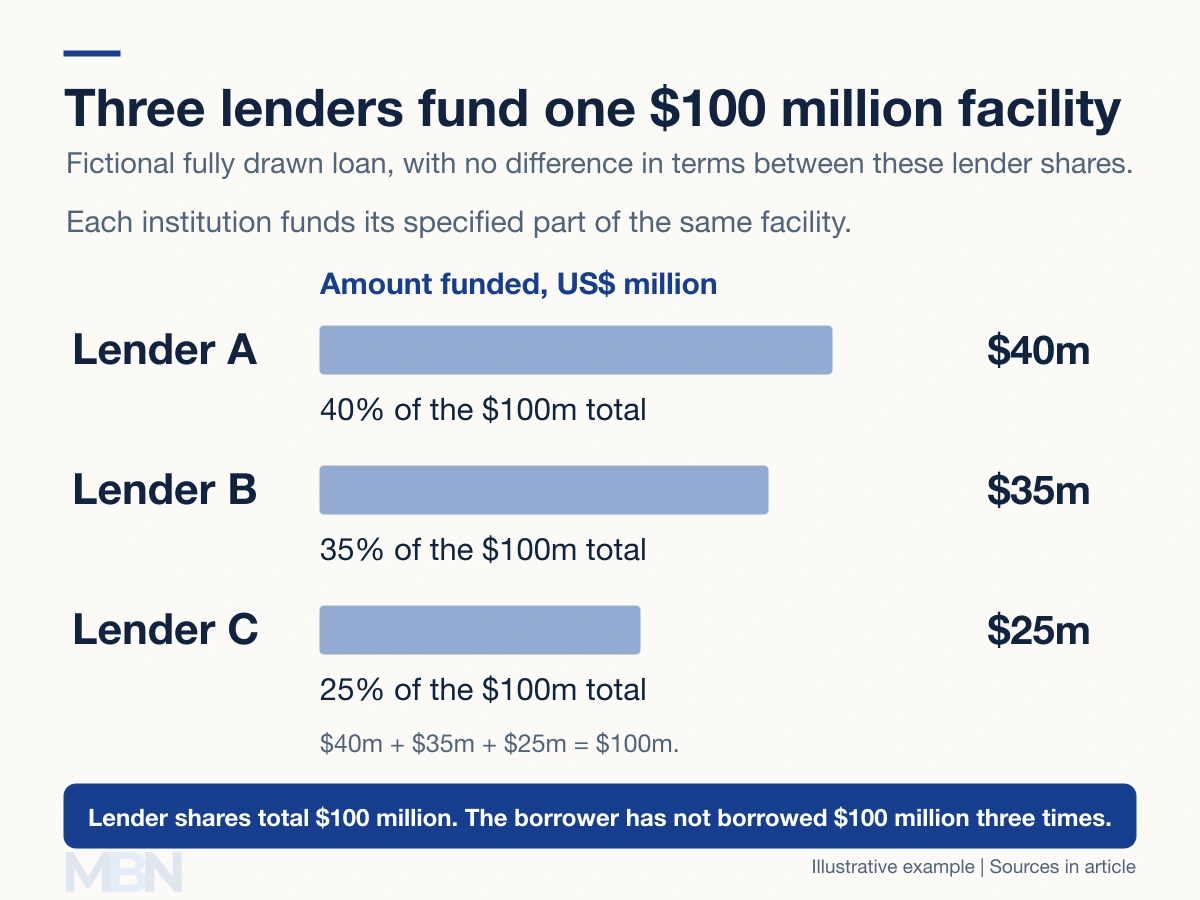
The agent can coordinate the borrower’s payments and distribute amounts under the agreement. A committed amount is not necessarily drawn immediately: a revolving facility may permit borrowing, repayment and redrawing within agreed limits.
How is interest determined?
Facilities can contain term loans, revolving credit or several tranches with different terms. Rates can be fixed or floating. A floating rate may add a margin to a specified benchmark, subject to floors and other contractual provisions.
LIBOR is no longer a current published benchmark: the FCA confirms that its final synthetic settings ended on September 30, 2024. The New York Fed publishes SOFR, an overnight Treasury-secured borrowing measure; contracts may specify a compounded or term-based convention. The LMA’s corporate lending documentation incorporates Term SOFR.
As a simplified example, an assumed 5% reference rate plus a 2.5-percentage-point margin gives 7.5% before fees. Actual interest depends on the contract, day-count basis and interest period.
Are these loans always senior or secured?
No. Syndication describes the lender group, not a universal insolvency priority. Security, guarantees, subordination and applicable law determine the relevant rights. A loan does not automatically rank ahead of every bond merely because banks participate.
A historical financing example
The Panama Canal expansion opened on June 26, 2016. Its authority records $2.3 billion of partial financing agreed with five international financial institutions in December 2008. That was partial project funding, not evidence that the entire project cost came from one syndicated bank loan.
Last checked and updated on November 4, 2026 by the MBN editorial team.