
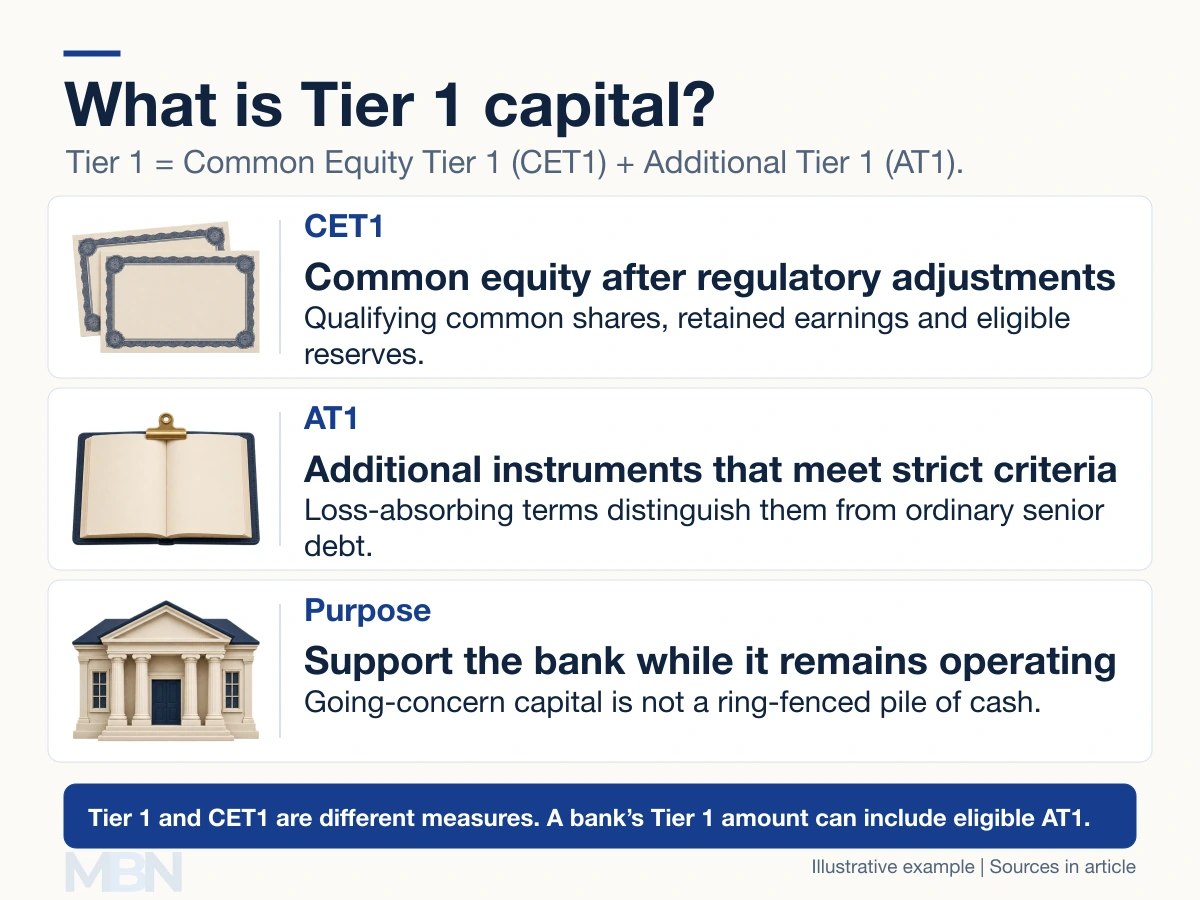
Tier 1 capital is a bank’s qualifying going-concern regulatory capital: Common Equity Tier 1, or CET1, plus Additional Tier 1, or AT1, after the required adjustments. Going-concern means designed to absorb losses while the bank remains operating.
The BIS capital-definition summary distinguishes Tier 1 from Tier 2, which provides gone-concern protection when a bank becomes nonviable or is wound down. Neither category is simply a cash reserve held in a vault.
What is Common Equity Tier 1?
CET1 principally comprises qualifying common shares, associated share premium, retained earnings and eligible reserves, with regulatory adjustments. The Bank of England’s capital-data definitions describe the main components.
Accounting equity and CET1 need not match. Goodwill is deducted under Basel rules. Other intangibles, deferred tax assets and investments in financial institutions have specified treatments and thresholds. An adjustment can reduce eligible capital; it is not automatically an extra asset to add.
What does AT1 add?
The Basel framework sets separate eligibility criteria for AT1 instruments. These instruments are subordinated, perpetual and subject to loss-absorption requirements. Distributions are discretionary and noncumulative: a canceled coupon need not become an amount payable later.
AT1 can face principal write-down or conversion into common equity under the applicable terms and rules. It should not be treated like an ordinary deposit or a conventional senior bank bond. Exact triggers and creditor rights depend on the instrument and jurisdiction.
A Tier 1 capital example
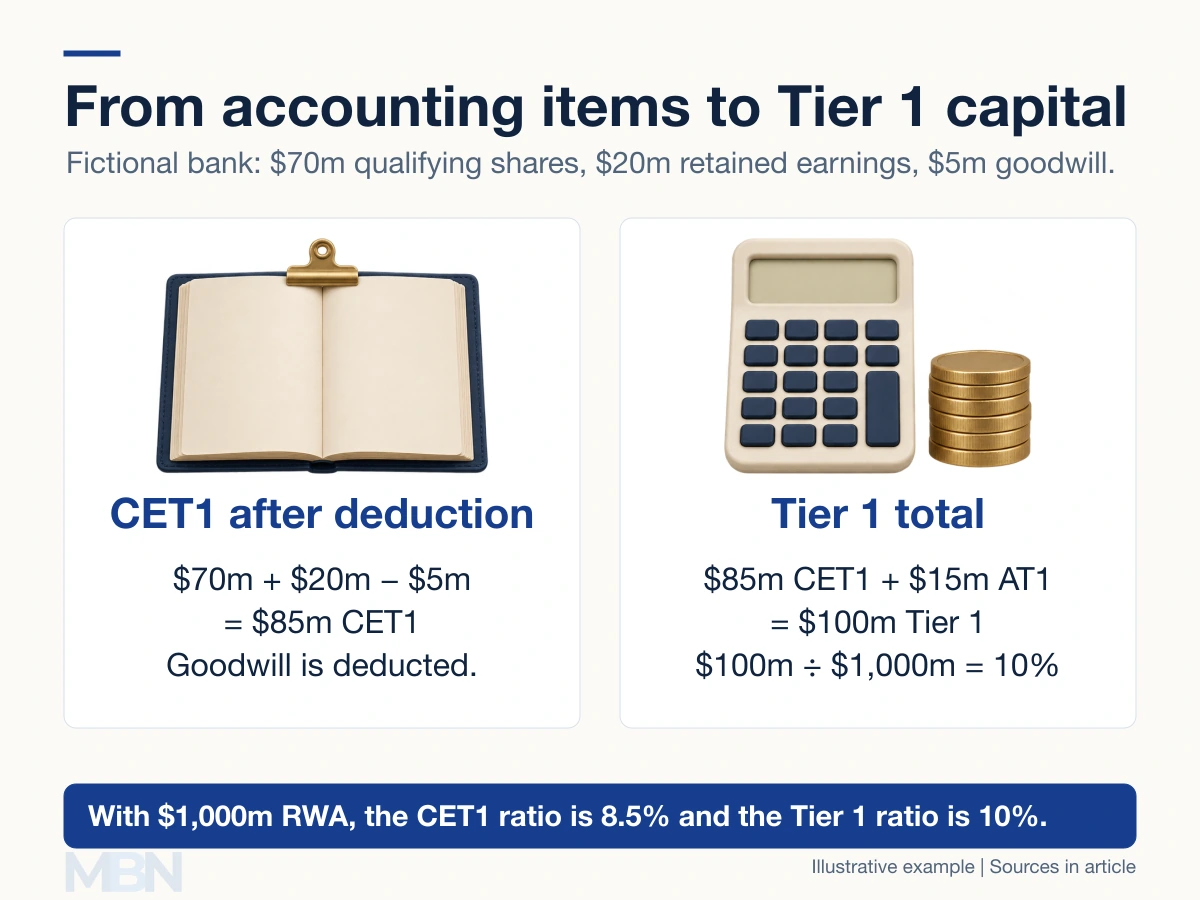
Assume a fictional bank has $70 million of qualifying common shares and share premium, $20 million of retained earnings, and $5 million of goodwill to deduct. With no other items or adjustments, CET1 is $70 million + $20 million − $5 million = $85 million.
Add $15 million of fully eligible AT1 and Tier 1 becomes $100 million. The $5 million goodwill deduction is not reversed when AT1 is added.
How is the Tier 1 ratio calculated?
The risk-based ratio is Tier 1 capital ÷ risk-weighted assets × 100. Risk-weighted assets, or RWA, measure exposures under regulatory methods, including relevant credit, market and operational risks.
If the example bank has $1 billion of RWA, its Tier 1 ratio is 10%. Its CET1 ratio is 8.5%. Adding $20 million of eligible Tier 2 would make total capital $120 million and the total capital ratio 12%, while leaving Tier 1 at 10%.
What requirements apply?
The Basel risk-based minimums are 4.5% CET1, 6% Tier 1 and 8% total capital, before applicable buffers and other requirements. These are different tests. The Basel Committee sets international standards; national authorities implement them through their own rules.
The leverage ratio also uses Tier 1 capital but a different, non-risk-weighted exposure measure. A bank’s Tier 1 amount, risk-based Tier 1 ratio and leverage ratio should therefore be identified separately.
Last checked and updated on November 4, 2026 by the MBN editorial team.