
The time value of money is a framework for comparing cash amounts received or paid at different dates. It accounts for the opportunity to earn a return over time, using an appropriate rate and stated assumptions.
With a positive discount rate, money received today has a higher calculated value than the same nominal amount received later. The principle helps explain savings, loans, leases, annuities and investment appraisal.
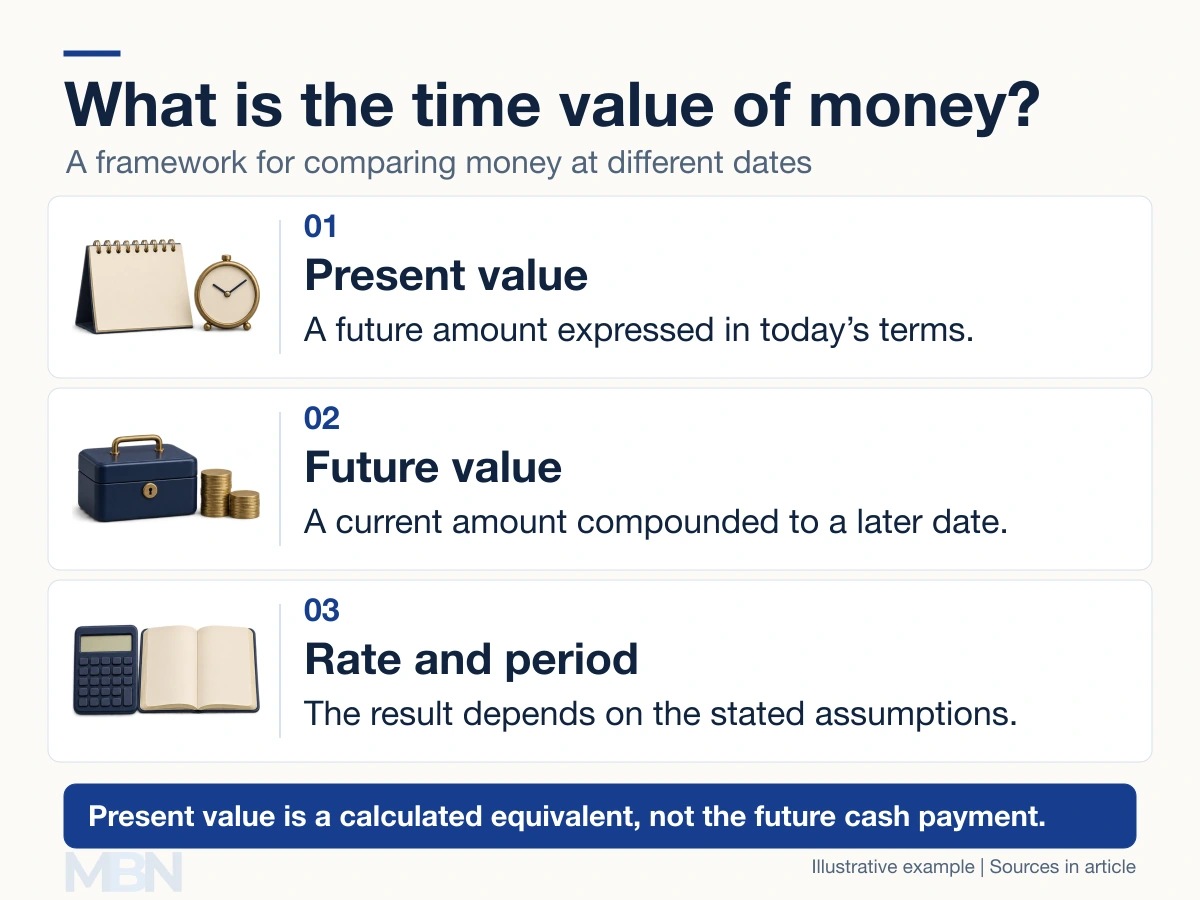
Present value and future value
Future value compounds a current amount forward. Present value discounts a future amount back to a chosen earlier date. Present discounted value is a result of that calculation, rather than an exact synonym for the entire time-value concept.
OpenStax’s finance text gives the lump-sum relationship: future value = present value × (1 + r)^n. Here r is the rate per period and n is the number of periods.
Rearranging gives present value = future value ÷ (1 + r)^n. These formulas assume a constant periodic rate and compound growth. The rate period and the number of periods must match.
What $1,000 today can become
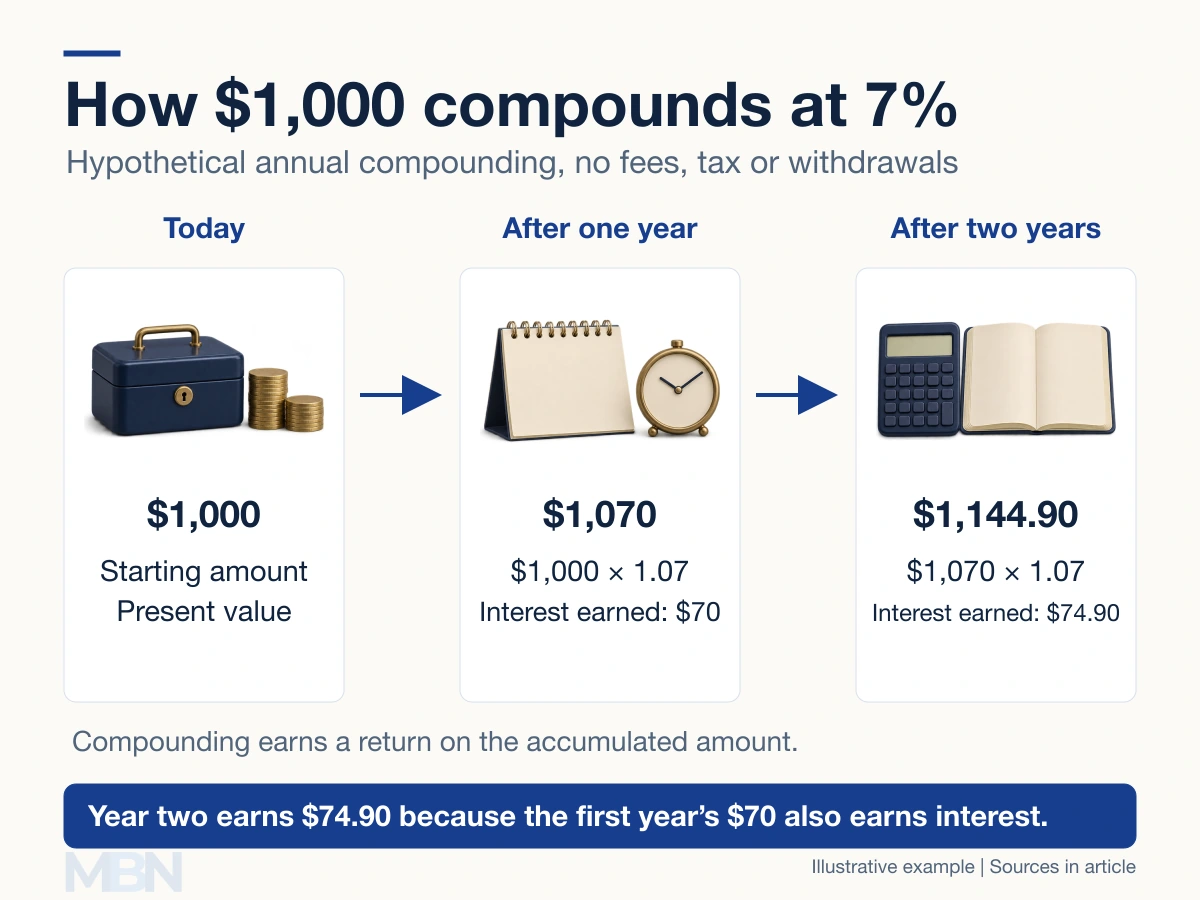
Assume $1,000 earns 7% per year with annual compounding, no fees, no tax and no withdrawals. After one year it becomes $1,000 × 1.07 = $1,070.
After a second year it becomes $1,070 × 1.07 = $1,144.90. The second year’s $74.90 interest is larger than the first year’s $70 because the first year’s interest also earns a return.
What $1,000 received later is worth today
Now consider a different question: what is the present value of a $1,000 payment due in one year, using a 7% annual discount rate?
The answer is $1,000 ÷ 1.07 = $934.58, rounded. That means $934.58 invested today at the assumed rate would grow to approximately $1,000 in a year. The actual payment next year remains $1,000; it does not become a $934.58 payment.
OpenStax’s discounting explanation shows how future cash amounts are converted into comparable present-value terms.
The rate matters
A discount rate should fit the payment’s timing, risk and valuation purpose. A risky project does not automatically merit the same rate as an insured deposit. The 7% used here is illustrative, not a current interest-rate quotation.
At a zero discount rate, an unchanged nominal payment has the same present and future value in this calculation. A negative rate can reverse the usual ordering. Not every bank account earns positive interest, and fees can reduce the amount received.
Inflation and purchasing power
The European Central Bank distinguishes nominal interest from real returns, which take inflation into account. A larger cash balance need not buy proportionately more goods and services.
Inflation and discounting should be treated consistently. ACCA’s investment-appraisal guidance explains matching nominal cash flows with nominal discount rates, or real cash flows with real rates. Adding a separate inflation reduction to a calculation already made consistently can double-count its effect.
Several payments can be compared too
For a series of payments, discount each to the same valuation date and add the results. Payment timing matters, including whether installments arrive at the beginning or end of a period. Capital budgeting applies this approach to project cash flows.
Last checked and updated on November 5, 2026 by the MBN editorial team.