
Toxic assets is an informal term for troubled financial assets that are difficult to value or sell, often after severe doubts arise about their expected repayments. The label became prominent during the 2007–2009 financial crisis.
Nasdaq’s glossary connects the term with illiquid, hard-to-value mortgage-backed securities and other structured investments. It does not mean that every asset whose price falls is toxic, that its value is zero, or that further declines are inevitable.
Credit losses, valuation and liquidity
Credit risk concerns whether borrowers make the payments owed. Valuation concerns what an asset is worth given expected payments and risks. Liquidity concerns whether it can be sold promptly without a substantial price concession.
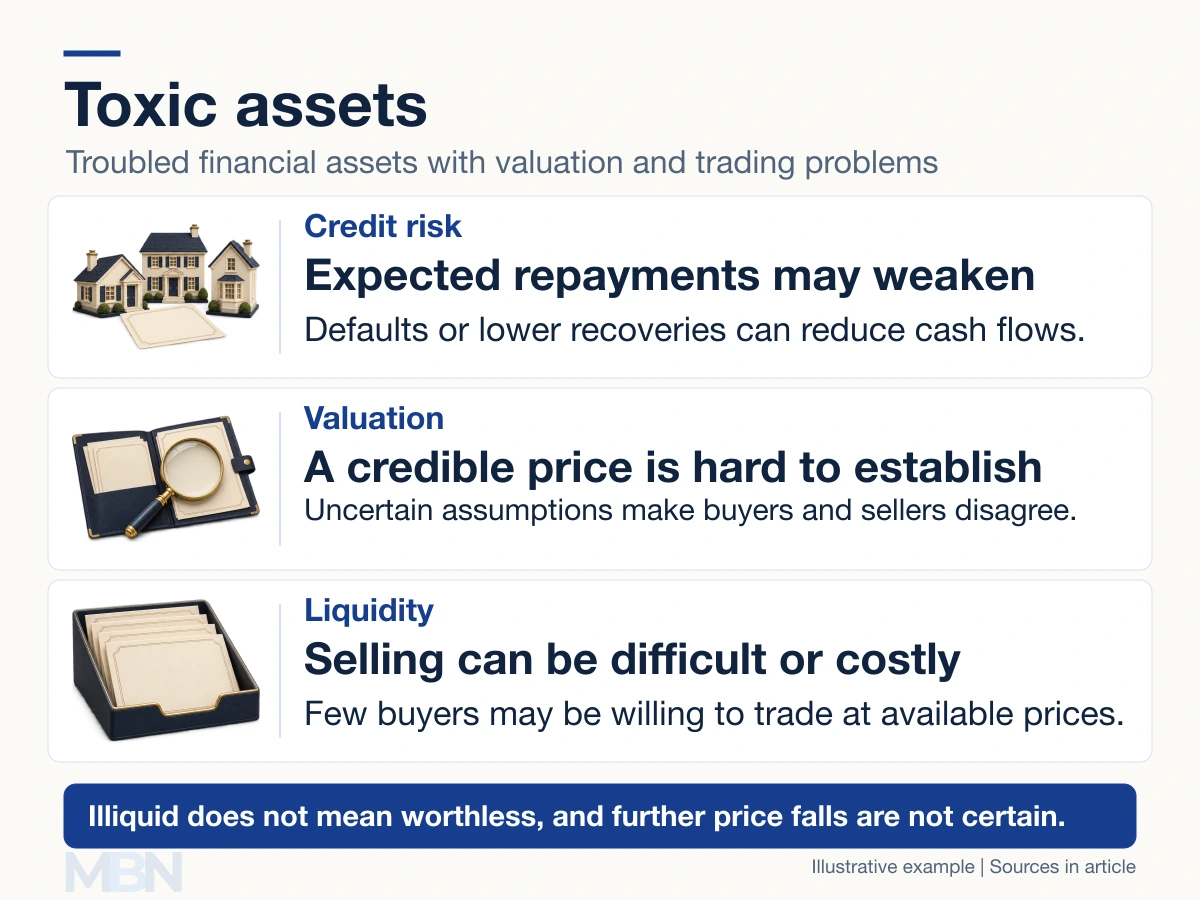
These problems can reinforce one another. If buyers cannot confidently assess losses, they may offer much less than sellers expect or avoid trading. A market described as frozen can have very little activity; this is different from an exchange formally suspending all trading.
An IMF account of the subprime-market turmoil describes how complex structures and reduced liquidity made valuation difficult. A lack of market transactions does not itself establish that the underlying borrowers will pay nothing.
A mortgage is not automatically a mortgage-backed security
A mortgage loan is an asset of the lender. It does not become a mortgage-backed security merely because the lender advances money or sells that individual loan.
In a simplified securitization, multiple loans are gathered into a pool and securities are issued with claims linked to the pool’s cash flows. The SEC explains that basic mortgage pass-through securities give investors proportional interests in principal and interest payments from a mortgage pool. More complex structures allocate payments differently.
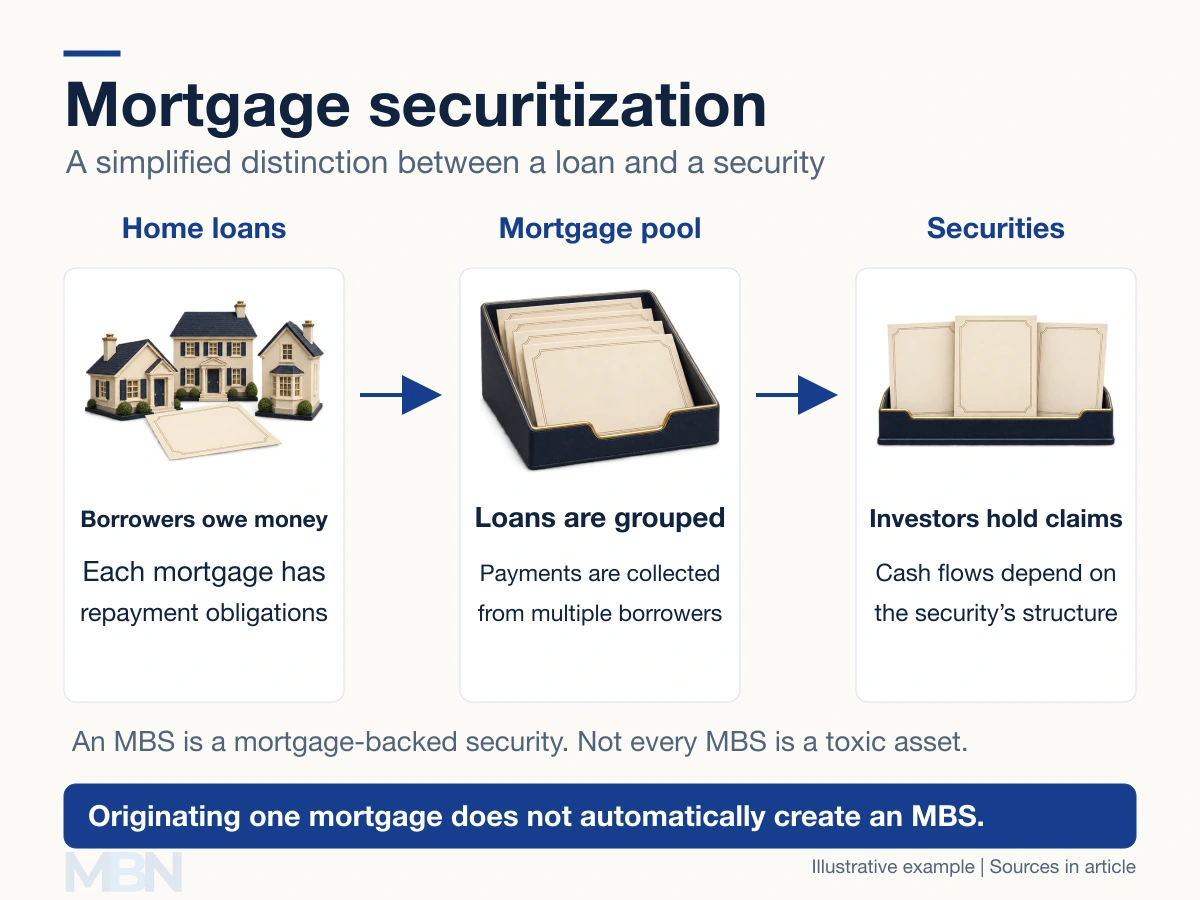
If some borrowers default, the effect on a security depends on recoveries, guarantees, credit protection and payment priorities. One missed mortgage payment does not automatically stop every investor’s payments or make every security in the pool worthless.
Why these assets mattered in the financial crisis
Losses on housing-related investments combined with uncertainty about their value and difficulty trading them. In September 2008, US Treasury Secretary Henry Paulson described illiquid mortgage assets losing value as a central weakness in the financial system.
That historical description does not make all mortgage-backed securities toxic. Their credit quality and structures differ. Nor did every highly rated asset become worthless during the crisis.
What a loss means for the holder
A decline in an asset’s recoverable or market value may require a write-down under the applicable accounting rules, reducing reported earnings or capital. A sale can also crystallize a loss.
The US banking agencies’ securities-classification guidance emphasizes analysis of credit quality and repayment capacity. An impaired asset does not automatically make its owner insolvent: the scale of the loss, the owner’s other assets and its loss-absorbing capital all matter.
Last checked and updated on November 10, 2026 by the MBN editorial team.